
3 Dividend Stocks With Yields Reaching 7%
Power grid spending just hit a record high as utilities rushed to add new transmission lines, and that surge in hard infrastructure investment puts reliable cash generators back in the spotlight. Investors are again paying attention to companies that share more of those steady cash flows through dividends. This article breaks down three income stalwarts with yields above 5% that have long records of keeping payouts coming.
The stocks covered below are just a starter pack, and the full Dividend Aristocrats screen surfaced 209 more listed businesses with similarly compelling income stories that are not in this article. To identify the highest conviction 5%+ yield candidates for your watchlist, head straight to the Dividend Aristocrats screener and analyze which dividend payers best fit your risk and return goals.
Sinotrans (SEHK:598)
Overview: Sinotrans is a Beijing based logistics group that runs contract logistics, freight forwarding and terminal services across sea, air and rail, helping customers move goods efficiently.
Market Cap: HK$53.48 billion
For income investors hunting for yield backed by real world assets, Sinotrans fits the Dividend Aristocrats theme through its long established contract logistics, freight forwarding and terminal operations. The analyst consensus Narrative on Simply Wall St adds useful context on how the business is trying to grow those cash flows.
"Global e-commerce volume is expanding rapidly, supported by Sinotrans's robust 77% revenue growth in its e-commerce segment and investments in cross-border fulfilment platforms, which positions the company to capture continued long-term revenue growth as digital retail penetration increases."
What happens if one quiet pressure on Sinotrans's profitability shifts at the same time income investors are counting on a near 7% yield?
If that shift worries you, read the full narrative for Sinotrans to see how Sinotrans balances yield, e-commerce momentum, and the pressures that could be quietly building.

Chow Sang Sang Holdings International (SEHK:116)
Overview: Chow Sang Sang Holdings International is a Hong Kong based jewellery group that manufactures and sells branded jewellery and watches through extensive retail stores, supported by wholesale precious metals and gemstone trading that help sustain its high dividend profile.
Operations: Chow Sang Sang generates about HK$23.6b from Retail of Jewellery and Watches and HK$658m from Wholesale of Precious Metals, with Mainland China and Hong Kong and Macau contributing most sales.
Market Cap: HK$9.1b
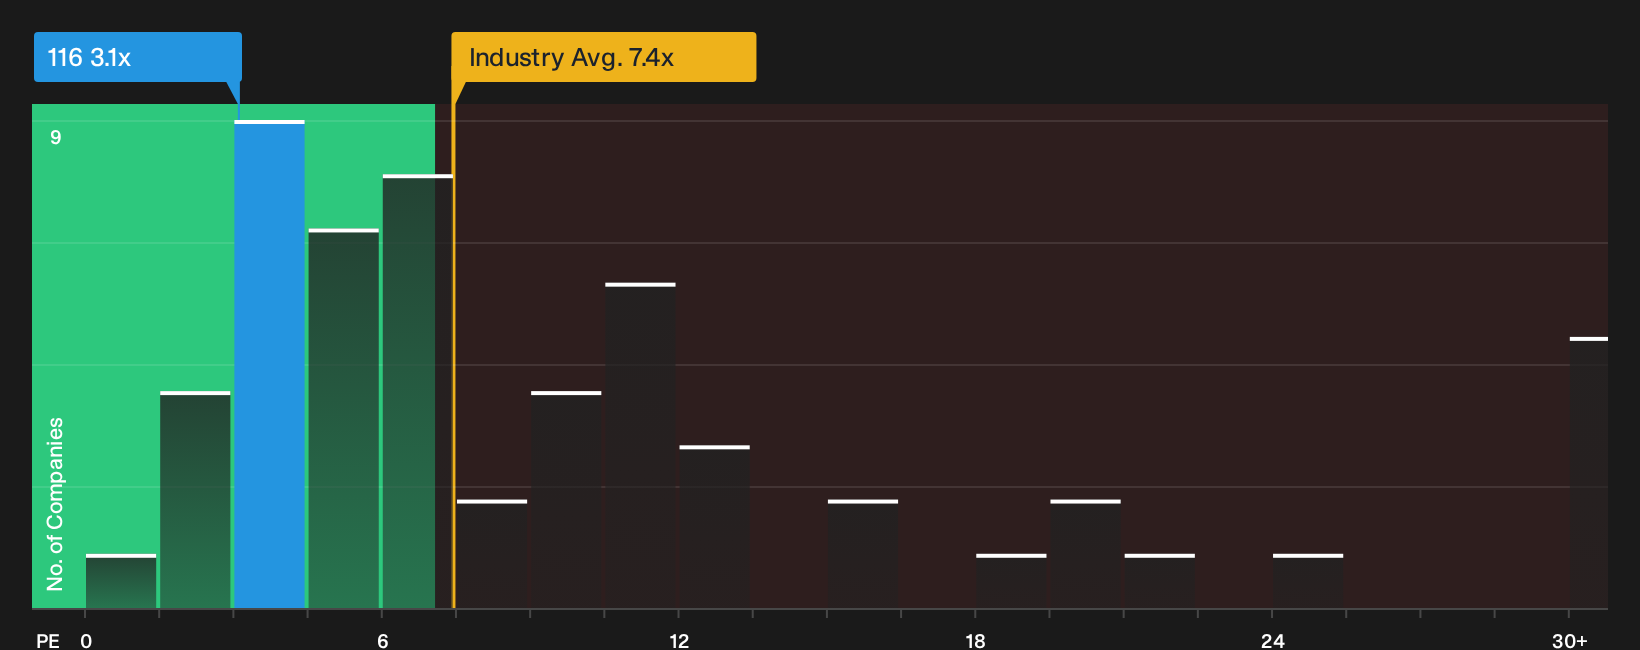
Income focused investors may be drawn to Chow Sang Sang because its jewellery stores produce sizeable, recurring cash inflows that support meaningful dividends. The stock trades on a low P/E of about 3.1x, and recent H1 2026 profit of roughly HK$2.1b to HK$2.2b backs the latest interim payout. However, one unresolved shift in future earnings pressure could decide how dependable that income stream really is.
That pressure point is exactly what the 3 key rewards and 2 important warning signs (1 is major!) could clarify for you, by showing where Chow Sang Sang’s income story may be stretching or accelerating.
Nippon Shokubai (TSE:4114)
Overview: Nippon Shokubai is a Japanese chemical manufacturer producing acrylics, superabsorbent polymers and construction related polymers that support steady industrial demand.
Market Cap: ¥354.7b
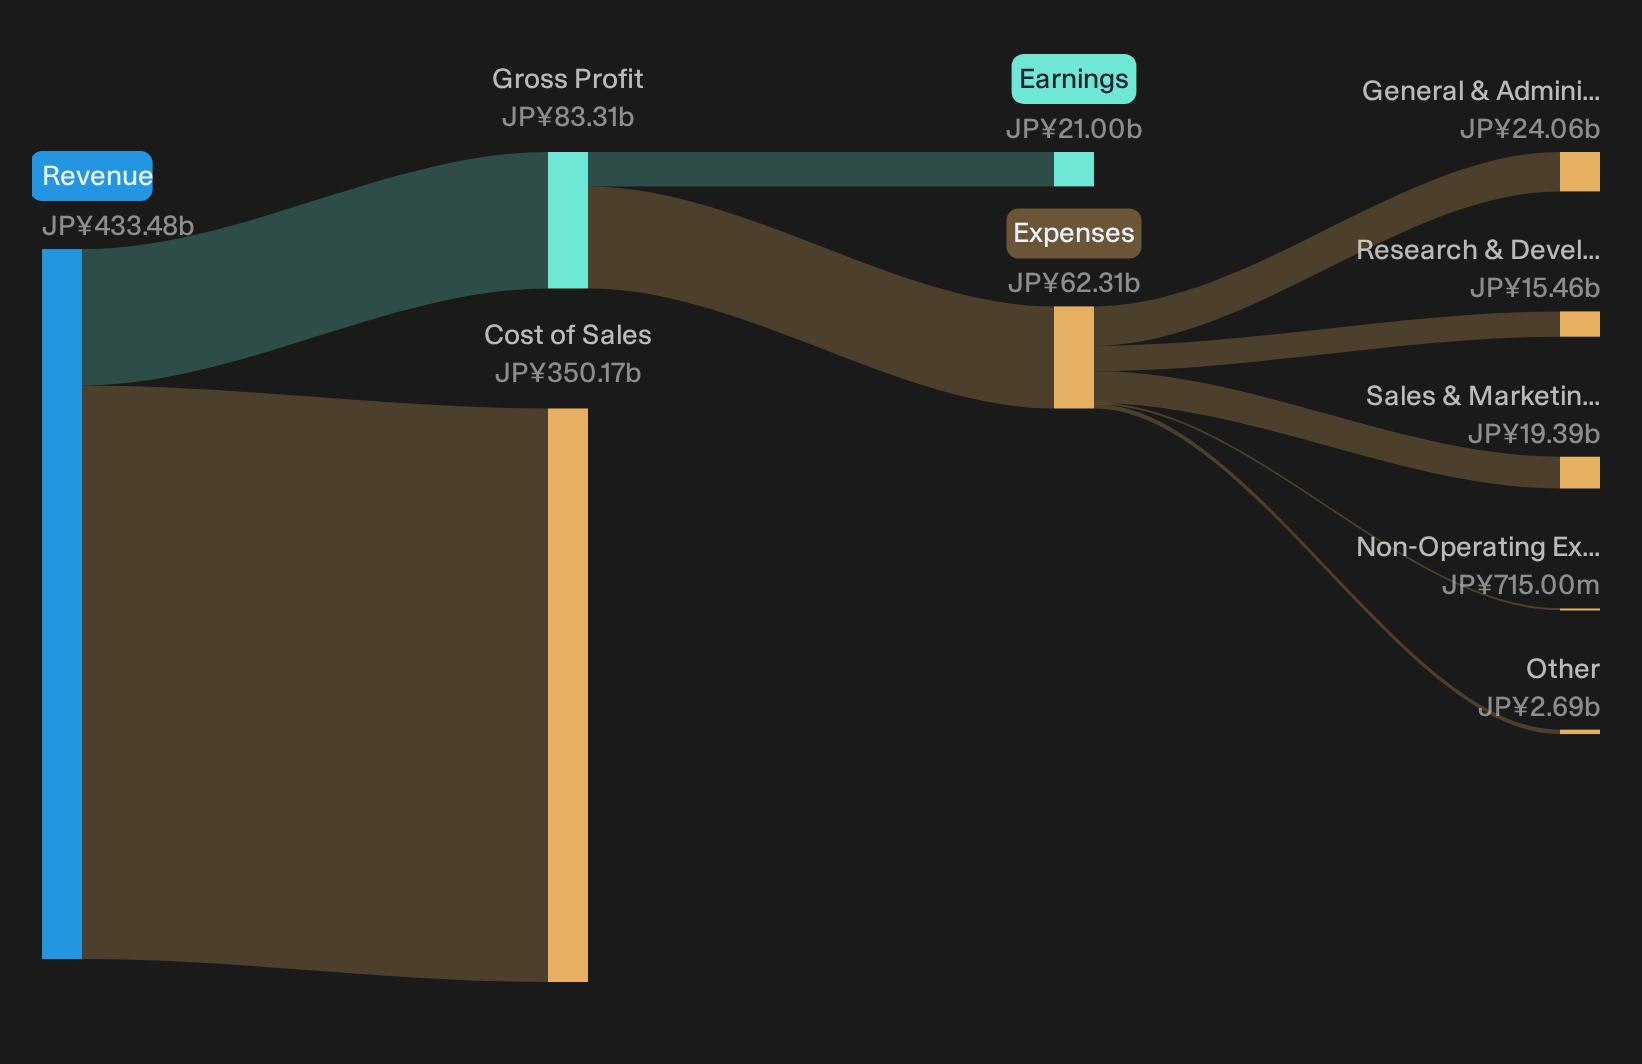
Nippon Shokubai offers a roughly 5.7% dividend yield, supported in part by polymers used in concrete admixtures and construction materials. Infrastructure projects tend to keep volumes relatively steady even when other chemical cycles cool. Income focused investors may still want to monitor how any increasing pressure on free cash flow coverage could affect the sustainability of that payout cushion.
That free cash flow question is the hinge, so go straight to the 3 key rewards and 1 important warning sign to see where Nippon Shokubai’s payout coverage could be shifting.
Seeking Alternatives Before Momentum Flies
Fresh income ideas can move quickly, and the strongest candidates may be identified early, before the crowd notices and yields start dropping. Scan these under-the-radar picks and consider them promptly.
- Target reliable paycheck potential by scanning a curated 212 dividend fortresses while yields still look attractive and dividend cushions remain under the radar.
- Review a focused 42 power grid technology and infrastructure stocks to explore structural infrastructure opportunities before these grid rebuild beneficiaries gain wider attention and pricing power shifts away from early movers.
- Use a carefully filtered list of solid balance sheet and fundamentals (195 results) to hunt for resilient growth-plus-cash-flow stories so you stay ahead of investors who only react once momentum is already established.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com