
Should Blockchain Ratings Pilot Require Action From Moody's (MCO) Investors?
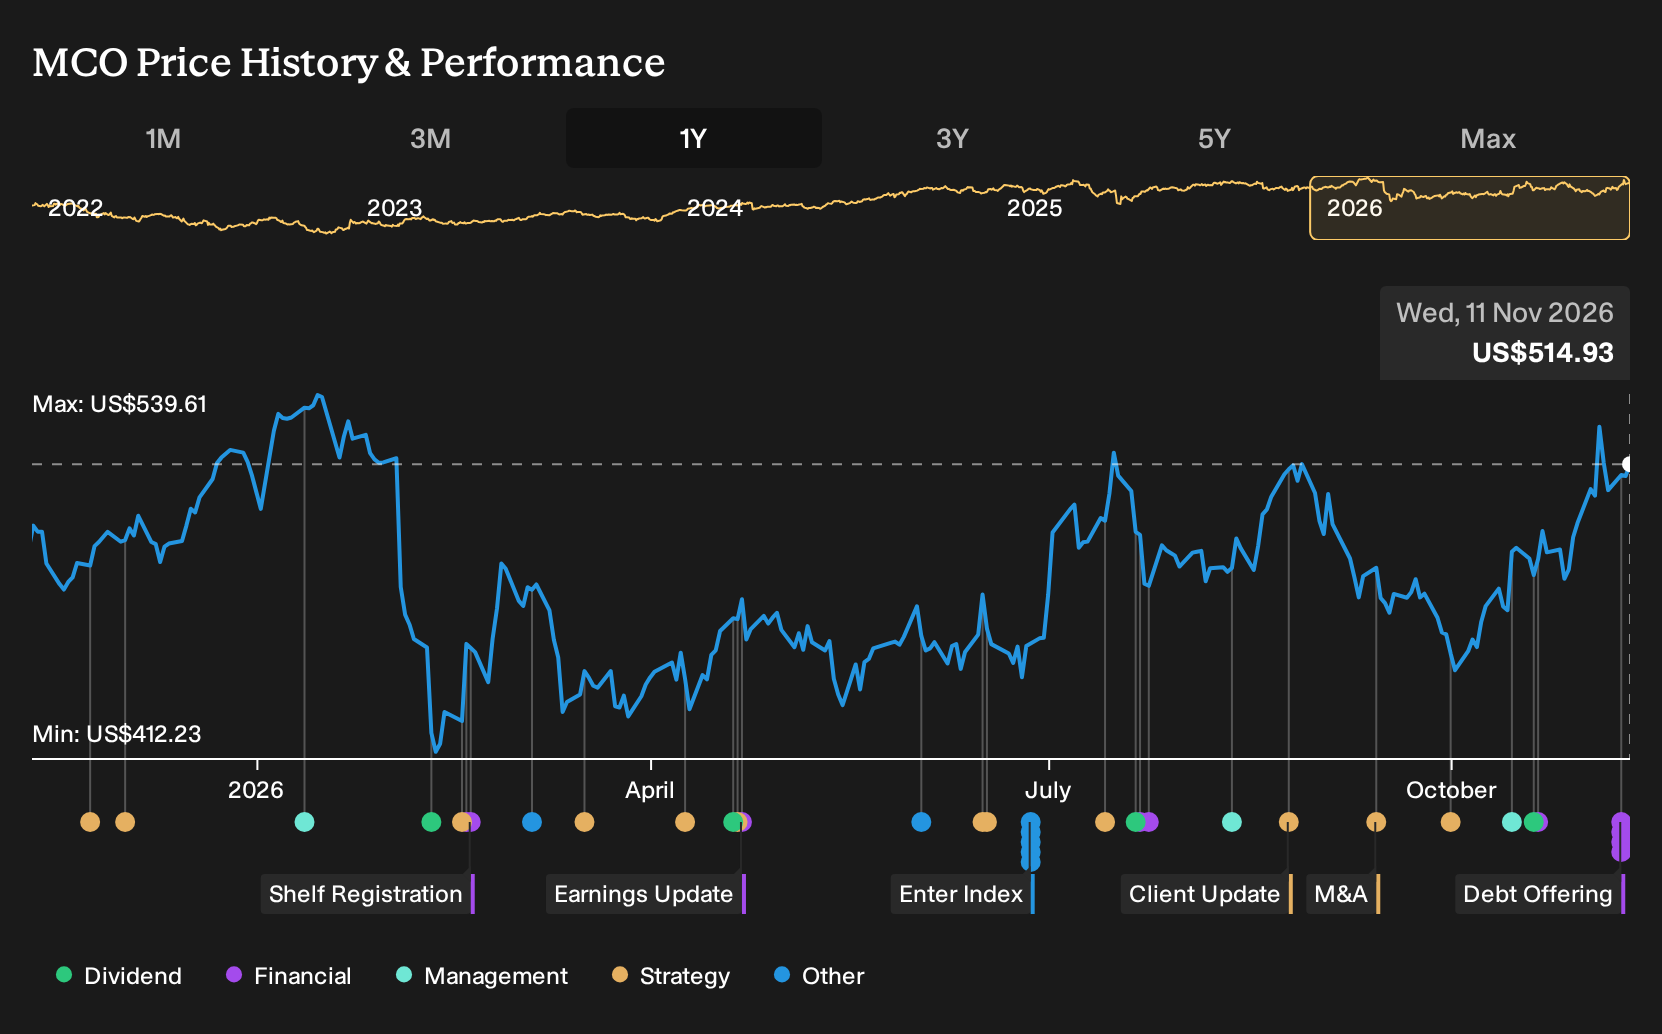
- Moody's has completed a €496.105 million fixed income offering of 4.125% senior unsecured notes due November 12, 2033, and has also added Merrill Lynch International and HSBC Bank plc as co lead underwriters on the deal.
- The business also finished a pilot with Chainlink that transmitted sample credit ratings across multiple blockchains, signaling that Moody's is testing how its rating infrastructure could plug into tokenized securities and digital asset workflows.
- We will now look at how Moody's toll booth style investment narrative connects to this Chainlink blockchain pilot on multichain ratings.
Track how Moody's moves from eurobond funding to multichain credit ratings by scanning a curated group of institutions exposed to similar themes in our list of solid balance sheet and fundamentals (23 results)
Moody's Investment Narrative Recap
Owning Moody's means believing the toll booth model on global debt can keep working, as OLetourneau, an investor in the Simply Wall St Community, puts it. The recent €496.105 million bond issue looks more like routine balance sheet management than a shift in the operating story. In the near term, the key catalyst is whether issuance volumes and demand for risk solutions keep supporting the current earnings base.
The biggest operational risk still sits with regulation. OLetourneau argues the real tail risk is regulators reducing reliance on formal ratings, not technology replacing analysis. The new eurobond adds to an already high debt profile, so execution on cash generation and refinancing remains important, even if this funding step alone is not a material change.
The Chainlink pilot on multichain ratings is the announcement that lines up most closely with the current toll booth narrative. Moody's used its Token Integration Engine with Chainlink's interoperability protocol to send sample ratings to several blockchains while keeping normal control processes. That keeps the core franchise intact while testing how ratings might follow tokenized bonds across different venues.
For catalysts, this blockchain work matters if tokenized securities workflows become more common and issuers still want the same Moody's stamp wherever those assets trade. The operational question is execution, not hype. Investors will likely watch whether pilots like this turn into paid products within Moody's Analytics or support Moody's Investors Service volumes without adding new regulatory or technology risks.
On those terms, OLetourneau argues that Moody's narrative lands at a fair value of $529.00, built on 8.4% annual revenue growth and a 34.3% future profit margin. Together, these reflect an AI leveraged toll booth, where regulatory licensing still anchors pricing power.
Uncover why Moody's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Eight fair value models from the Simply Wall St Community cluster between about $438 and $562, which leaves Moody's trading anywhere from clearly cheap to stretched in some members' eyes. You are seeing that spread before factoring in the new €496.105 million bond or the Chainlink pilot, so treat fresh funding and digital projects as additional filters when comparing those viewpoints.
Explore 7 other Moody's fair value estimates, including one that suggests there could be as much as 15% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Moody's research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Moody's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Moody's overall financial health at a glance.
Looking for more investment ideas beyond Moody's?
Once you have a view on Moody's, it can help to compare that thesis with other companies that share similar qualities or offer a very different risk profile. The Simply Wall St Screener lets you quickly filter for traits that match how you like to invest, whether that is resilience, upside potential or income.
- For investors who care most about balance sheet strength and fundamental resilience, start with this curated list of solid balance sheet and fundamentals (23 results). It can help you find businesses that may better match your risk tolerance.
- If you want potential upside with quality as a guardrail, use the 19 high quality undiscovered gems to scan for lesser known companies that still show robust underlying metrics.
- Income focused readers can narrow in on stocks that prioritize cash returns to shareholders by reviewing the 6 dividend fortresses and seeing which yields and payout profiles fit their goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com