
Stewart Information Services (STC) Faces A Valuation Test As Growth Narrative Holds
Stewart Information Services (STC) has added veteran banking executive Michael Brown to its Board of Directors, with the appointment effective 4 November 2026, and has assigned him a seat on the Audit Committee.
For shareholders, the recent appointment comes after a tough stretch for Stewart Information Services. The share price is down 11.9% over the past month and 36.9% year to date. The 1-year total shareholder return has declined 37%, while the 3-year total shareholder return remains slightly positive at 5.6%. This suggests short-term momentum has faded even as longer-term holders have seen modest gains.
Scan how Stewart Information Services stacks up against other financially solid insurers by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) in the same corner of the market.
The question for Stewart Information Services now is simple. Does the sharp share price slide reflect real cracks in the business, or has sentiment just swung too far and left the valuation misaligned with fundamentals?
Most Popular Narrative: 37% Undervalued
On Simply Wall St, the analyst consensus Narrative sets a fair value for Stewart Information Services at $69.75, compared with the latest close at $44.12. This frames the recent price slide against a materially higher modelled value built from Street forecasts and a 7.24% discount rate.
Expansion of the Real Estate Solutions segment, which recently recorded revenue growth of 56% in Q1 2026 and 75% in Q2 2026 along with adjusted pretax margins progressing into the roughly 12.5% to 14% range, positions this lender-focused business to contribute more to consolidated revenue and to support ongoing adjusted margin improvement.
See why 2 investors see Stewart Information Services as 37% undervalued.
Result: Fair Value of $69.75 (UNDERVALUED)
Still, the Stewart Information Services narrative faces pressure from weak existing home sales and higher operating expenses, which could limit the benefit of commercial and Real Estate Solutions growth.
Find out about the key risks to this Stewart Information Services narrative.
Another View: Stewart Information Services Through A Cash Flow Lens
The analyst narrative frames Stewart Information Services as undervalued relative to a $69.75 fair value, yet the SWS DCF model tells a different story. On that cash flow based view, the shares at $44.12 trade above an estimated value of $36.37, which points to an overvalued outcome instead. For an investor weighing these two yardsticks, the real question is which set of assumptions feels more realistic for the next phase of the housing cycle.
To see how this cash flow approach is built and what would need to change for the result to move closer to the analyst target, Look into how the SWS DCF model arrives at its fair value..
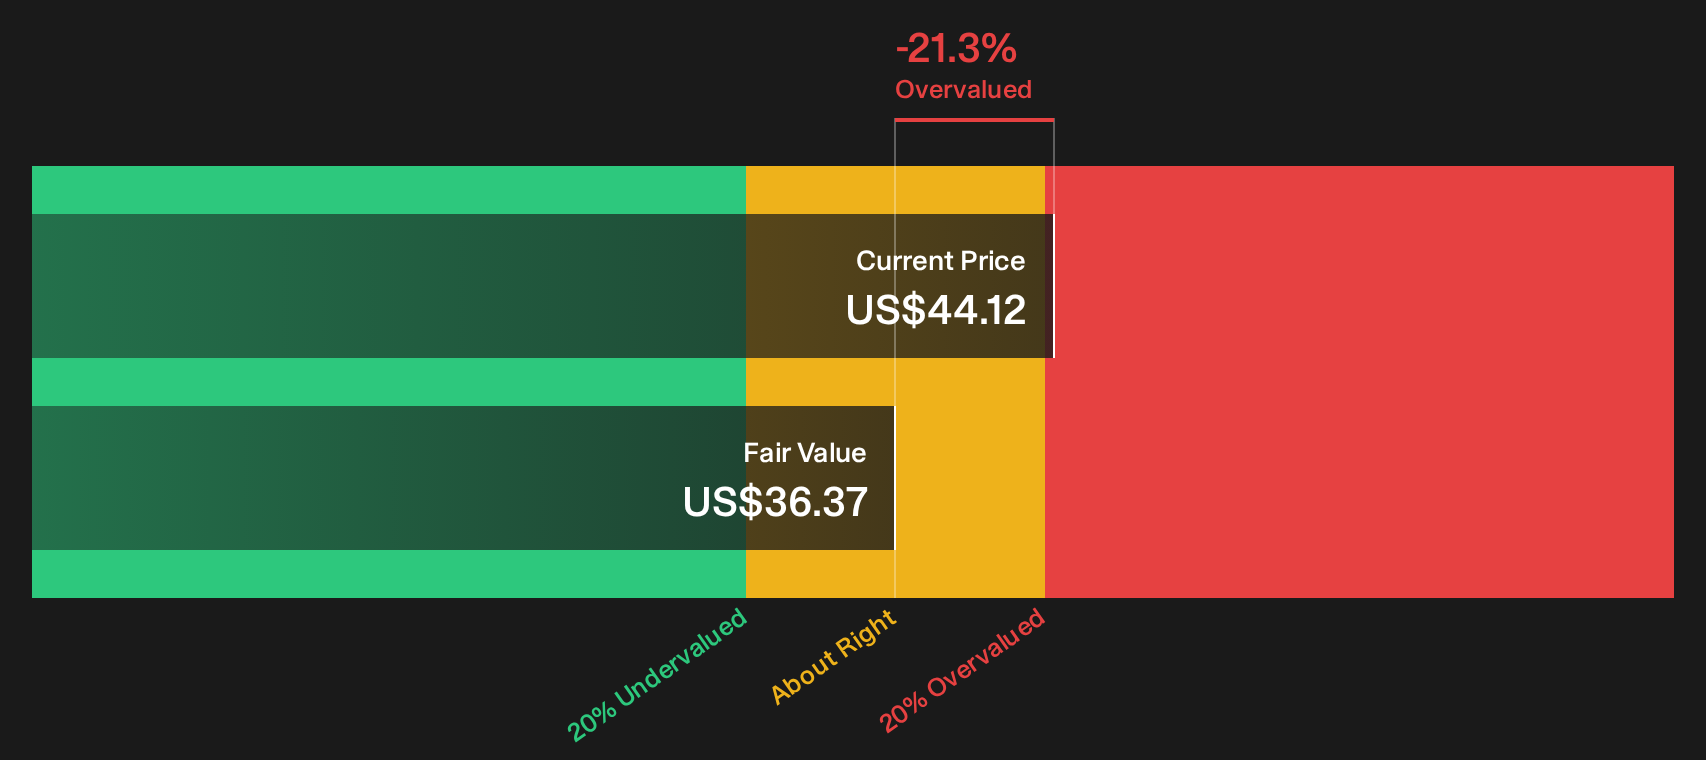
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stewart Information Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Stewart Information Services is clearly mixed right now, so act while the data is fresh and test the story against your own expectations using the 6 key rewards.
Looking for more Stewart Information Services sized ideas?
If you stop with Stewart Information Services, you only see one angle. Let the screener surface fresh ideas before the next big move slips away.
- Target steadier compounding by checking companies screened for resilient finances and lower risk profiles through the 30 resilient stocks with low risk scores.
- Hunt for potential bargains by scanning the 32 high quality undervalued stocks that pair stronger fundamentals with prices that trail underlying metrics.
- Pressure test your income watchlist by reviewing the 6 dividend fortresses that combine higher yields with more robust balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com