
Stantec And 2 Canadian Undervalued Stocks To Watch
Global power grid construction recently surged by 50%, highlighting how critical long term infrastructure and electrification spending has become worldwide. That kind of steady, utility style investment story is exactly where strong cash generation often shows up before share prices catch up. For investors looking at Canadian stocks, this article spotlights three businesses that appear priced below the cash flows their operations support, based on SWS DCF work.
The three stocks below are a small sample of what screens well on cash generation today. The full Simply Wall St search surfaced 5 more businesses with similarly compelling cash flow stories that are not covered in this article. To go beyond this short list, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the highest conviction cash flow ideas priced below their estimated fair value based on SWS DCF work.
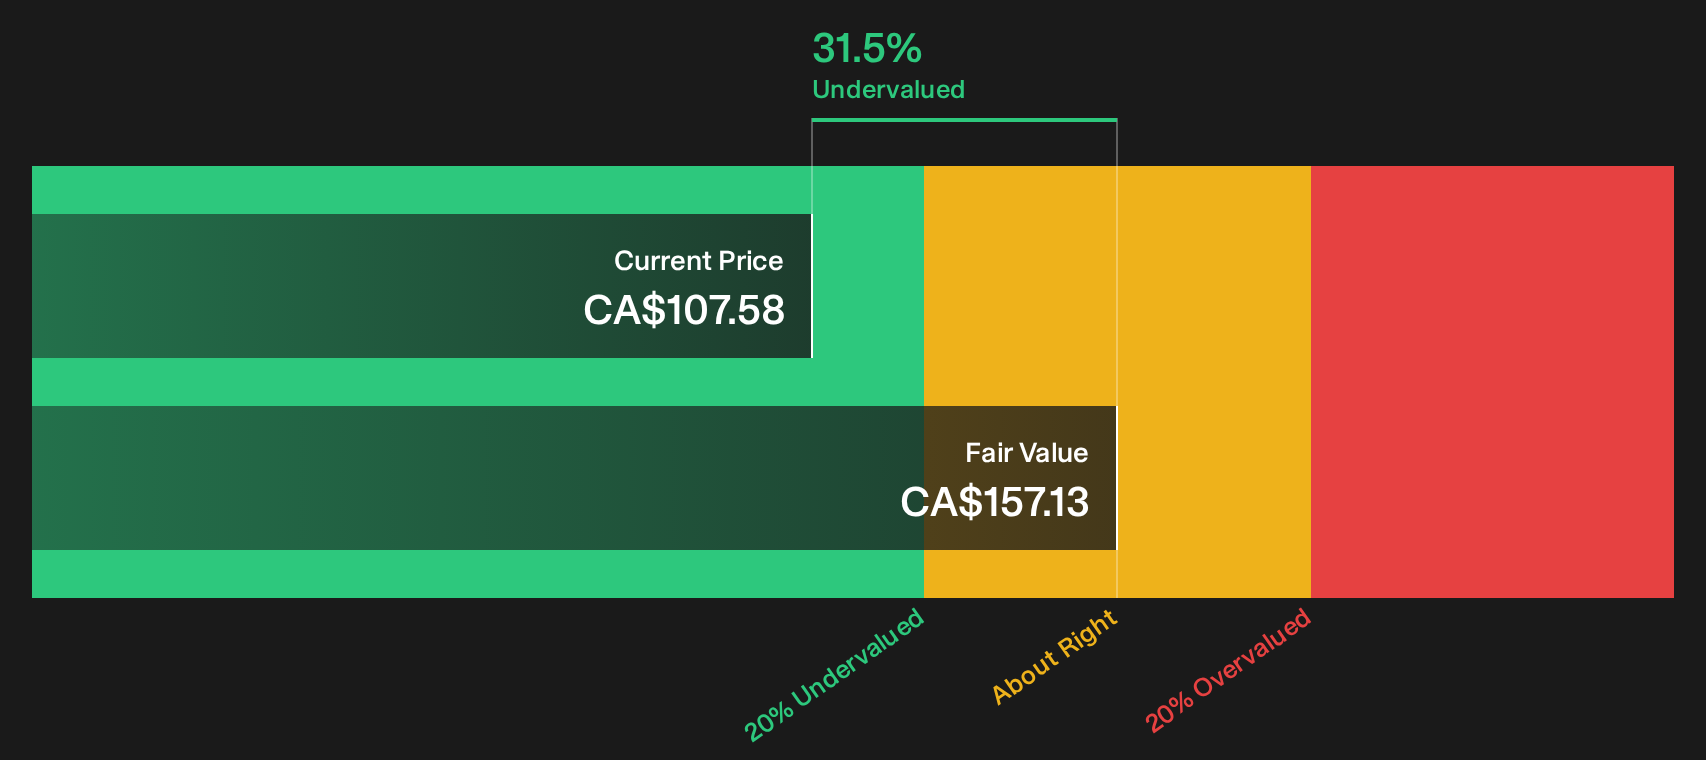
Stantec (TSX:STN)
Overview: Stantec is a global design and consulting firm that helps public and private clients plan, engineer, and manage long lived water, infrastructure, building, and energy projects that can support durable, contract backed cash flows.
Operations: Stantec generates about CA$3.6b of revenue from the United States, CA$1.6b from Canada, and roughly CA$1.7b from global operations.
Market Cap: CA$12.1b
Stantec matters in this cash flow focused screener because its water and infrastructure advisory work often runs on long contracts. The analyst consensus Narrative on Simply Wall St argues that this project backlog and earnings profile are not fully reflected in the current share price.
"Ongoing investment in digital transformation, including AI enabled proposal and project tools together with expansion of global delivery centers such as the Indian Global Delivery Center that has reached roughly 2,000 staff, is contributing to higher project margins and multi quarter adjusted EBITDA margin expansion and can continue to support further margin and earnings improvement."
The real swing factor for Stantec now is how one pressure on future cash conversion affects the pace of margin progress investors expect.
That margin puzzle is exactly what the full narrative for Stantec unpacks, showing how contract quality, pricing power, and capital discipline could reshape Stantec's cash story.
Barrick Mining (TSX:ABX)
Overview: Barrick Mining is a Toronto based miner that explores, develops, and produces gold and copper deposits that drive its long term cash flow story.
Operations: Barrick Mining generates most of its revenue from large gold and copper operations including Carlin at US$5.3b, Cortez at US$3.2b, and Pueblo Viejo at US$2.9b.
Market Cap: CA$91.9b
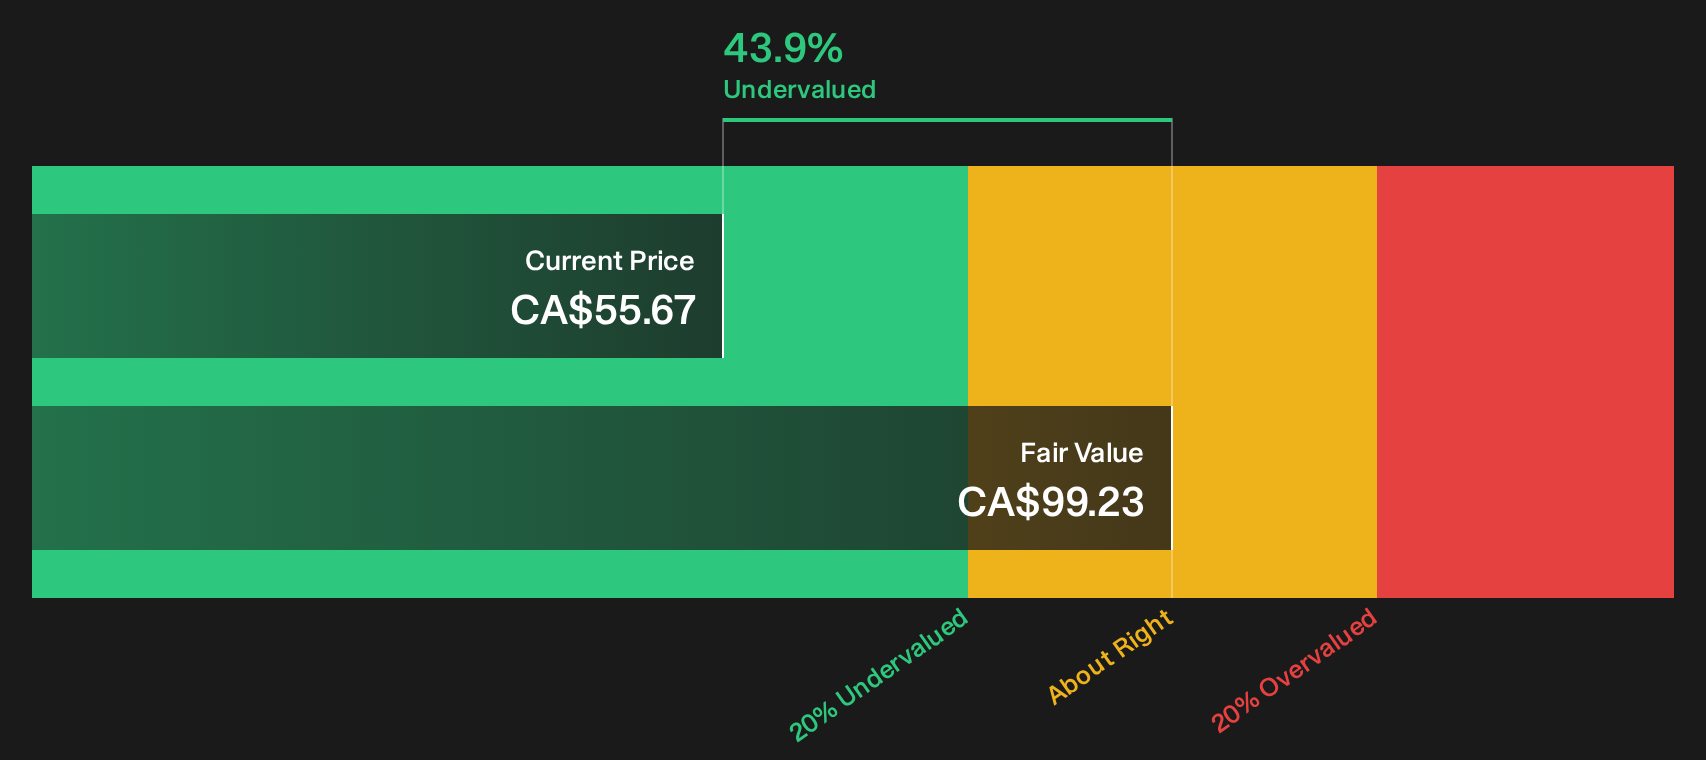
For a cash flow focused investor, Barrick Mining matters because its biggest gold and copper hubs are already throwing off sizeable mine level cash. In addition, the analyst consensus Narrative on Simply Wall St argues that the market price is not yet giving full credit for that output or the project pipeline behind it.
"Agreement with Newmont to restructure the Nevada Gold Mines joint venture, including bringing Fourmile and Newmont’s Mike and Fiberline assets into the JV and resolving historic disputes, is expected to let Barrick Mining reconfigure processing capacity, reduce ore trucking and pursue higher throughput in Nevada, which would directly affect group revenue and unit cash costs."
The real fulcrum for Barrick Mining now is how one shift in capital allocation between growth projects and cash returns reshapes future margins.
That capital shuffle is exactly what the full narrative for Barrick Mining breaks down, separating hype from hard cash flow as Barrick Mining evaluates growth, payouts, and risk at each major hub.
CGI (TSX:GIB.A)
Overview: CGI delivers end to end IT and business process services, with long term managed contracts that support recurring, predictable cash flows.
Market Cap: CA$23.9b
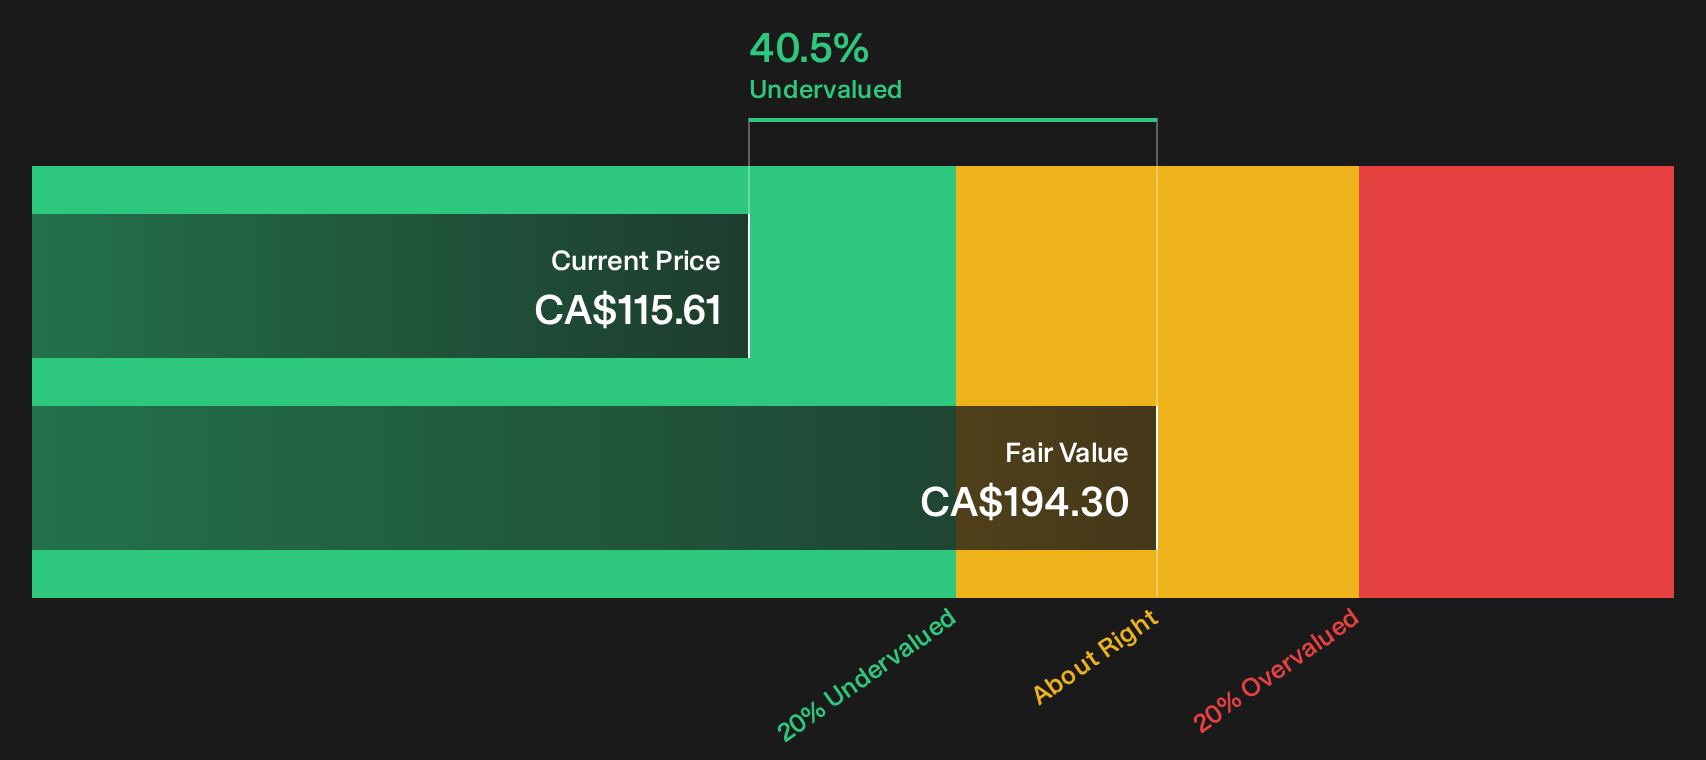
For a cash flow focused investor, CGI matters because its managed IT and business process work converts multi year client commitments into recurring money coming in. The analyst consensus Narrative on Simply Wall St argues that this contract base is not yet fully reflected in the share price.
"The ongoing acceleration in digital transformation initiatives, particularly in cloud migration, AI-driven automation and data analytics, continues to boost client demand for CGI's managed services and proprietary IP across both public and private sectors, which is likely to support sustained revenue growth and a rising mix of recurring earnings."
What happens to that cash flow story now depends on how one pressure on future contract mix and pricing plays out for CGI.
That pressure point is exactly where the full narrative for CGI picks up, mapping how CGI's contract mix, pricing power and cash conversion could be quietly accelerating beneath the surface.
Seeking Fresh Alternatives Before They Fly
Fresh cash flow stories can start breaking out before most investors even notice the momentum. Some of the best ideas stay under the radar for now. Consider conducting research early.
- Spot under-covered payers built to keep sending out distributions and scan a curated pool of income ideas through the 3 dividend fortresses.
- Track the companies building tomorrow's digital rails as capital shifts into real-world blockchain use cases through the curated 23 cryptocurrency and blockchain stocks.
- Hunt for resilient operators quietly reinforcing global transmission, generation and grid stability inside the focused 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com