
Sportradar Group (SRAD) Reaffirmed Full Year Guidance, Is The Stock Cheap?
Sportradar Group (SRAD) drew fresh attention after reporting third quarter 2026 results and confirming full year guidance, with management projecting constant currency revenue growth of 19% to 21% and outlining a €1,518 million to €1,533 million revenue range.
Sportradar Group’s latest guidance landed against a weak year-to-date share performance, with the share price down 43.31% since January and the 1-year total shareholder return declining 42.50%, even though the 3-year total shareholder return is positive at 28.72%.
Scan how Sportradar Group’s guidance compares with other sports and media data players by checking the hand picked 19 high quality undiscovered gems that investors are currently scrutinizing.
The sharp slide in Sportradar Group’s share price now sits against guidance that still points to sizeable revenue expansion ahead. Is more of the value already reflected, or is the larger part of the opportunity still in front of you?
Most Popular Narrative: 26.8% Undervalued
Sportradar Group’s last close of $13.22 sits well below the analyst consensus Narrative on Simply Wall St, which pegs fair value at $18.07 based on detailed revenue, earnings and discount rate assumptions.
Integration of IMG sports rights and long term exclusive data and AV deals such as Wimbledon and Euroleague Basketball, combined with multi year prediction market agreements that extend Sportradar Group data into new use cases, provide multi year visibility on content monetization and can support revenue and margin resilience.
See why 23 investors see Sportradar Group as 27% undervalued.
Result: Fair Value of $18.07 (UNDERVALUED)
Still, the Sportradar Group story only holds if legal actions and ongoing regulatory or tax pressure do not erode margins or weaken key customer relationships.
Find out about the key risks to this Sportradar Group narrative.
Another View: Sportradar Group On Sales Based Valuation
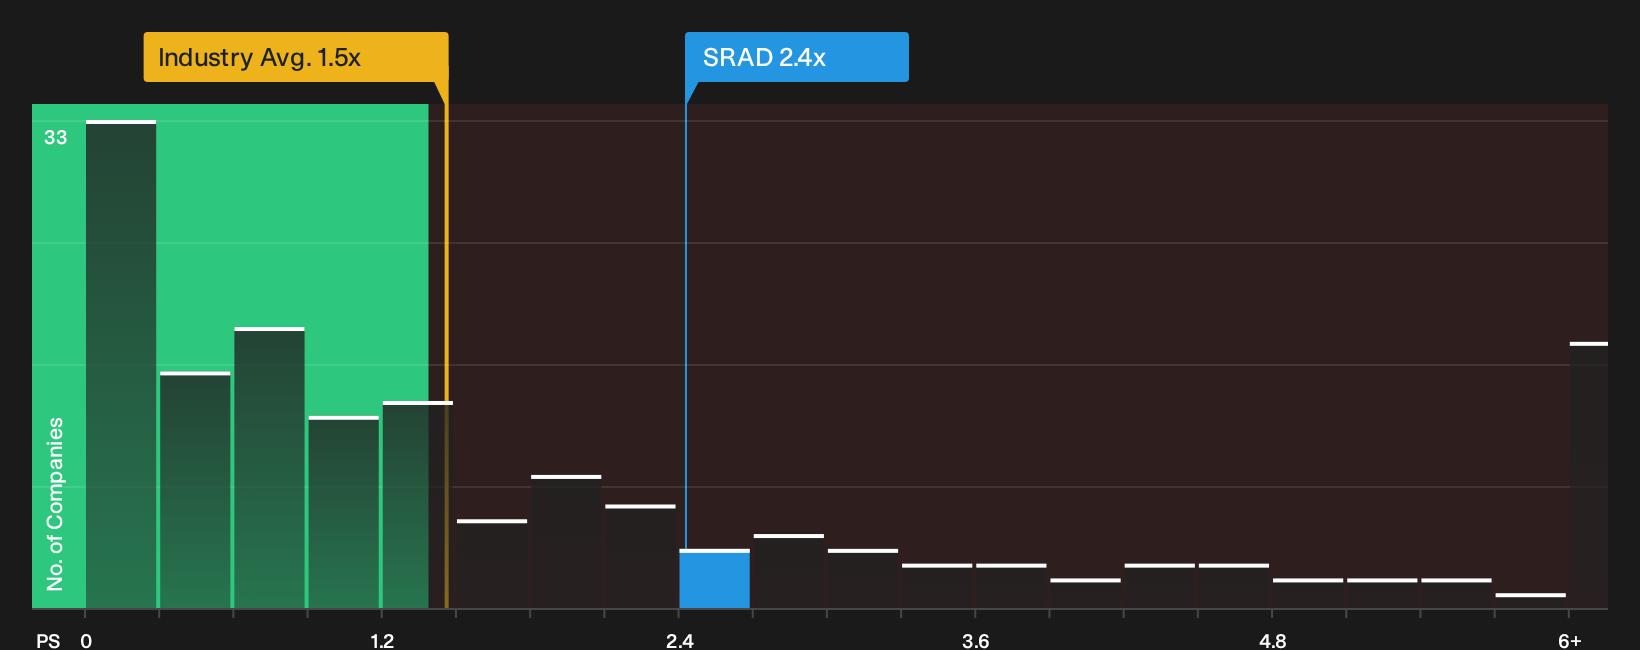
While our DCF model points to Sportradar Group trading at a 46.2% discount to an estimate of future cash flow value of $24.59, the P/S picture is less generous. The stock changes hands at 2.4x sales compared with a fair ratio of 1.1x and a US Hospitality average of 1.4x, which means the market is already assigning a richer revenue tag than both the sector and that fair ratio suggest. Which signal do you trust more when cash flow and sales are telling different stories?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Sportradar Group story can make it hard to trust any single signal, so move quickly, inspect the data yourself, and pressure test the bull and bear cases. Then gauge the balance of upside and downside by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Sportradar Group style investment ideas?
If Sportradar Group has sharpened your focus on valuation and quality, do not stop with a single ticker. Broaden your watchlist now so you are not late to the next setup.
- Target potential mispricings by scanning a focused set of 32 high quality undervalued stocks that combine solid fundamentals with attractive entry points.
- Prioritize resilience and sleep better at night by filtering for 30 resilient stocks with low risk scores that emphasise financial strength and lower historical risk scores.
- Hunt for quality away from the crowd by tracking a curated pool of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com