
Tecnoglass Holdings (TGLS) Could Be 15% Undervalued On Raised 2026 Revenue Outlook
Tecnoglass Holdings earnings spark renewed investor focus
Tecnoglass Holdings (TGLS) is back on investor screens after reporting third quarter 2026 results that combined higher sales with lower net income, along with a higher full year revenue outlook.
The latest earnings have been released during a sharp short-term rebound for Tecnoglass Holdings. The stock has a 1-month share price return of 24.55% and a 7-day move of 10.35%. However, the year-to-date share price is still down 9.22%, and the 1-year total shareholder return stands at 2.91%.
Scan how Tecnoglass Holdings compares to other construction and industrial suppliers showing strong momentum and upgraded outlooks using our curated list of 19 high quality undiscovered gems.
Bulls point to Tecnoglass Holdings raising its revenue outlook and the stock’s sharp rebound, while bears focus on the drop in net income and earnings per share. Which side does the current valuation lean toward?
Most Popular Narrative: 15% Undervalued
The analyst consensus Narrative on Simply Wall St sees Tecnoglass Holdings trading below its inferred fair value of $55.75, compared with the latest close at $47.24. That view rests on a detailed read of backlog, tariffs, and capital allocation.
Ongoing urbanization and population migration in the Americas, combined with Tecnoglass Holdings’ continued move into new U.S. regions, is feeding into a record US$1.4b project backlog and sustained book to bill above 1x, which can support future revenue and earnings as this work converts to sales.
See why 22 investors see Tecnoglass Holdings as 15% undervalued.
Result: Fair Value of $55.75 (UNDERVALUED)
Still, the Tecnoglass Holdings story could look very different if aluminum tariffs and Colombian peso strength keep squeezing margins, or if the US$1.4b backlog starts to shrink.
Find out about the key risks to this Tecnoglass Holdings narrative.
Another view on Tecnoglass Holdings valuation
On earnings and price targets, Tecnoglass Holdings looks undervalued against the US$55.75 fair value often cited by analysts. The SWS DCF model presents a stricter view, with an estimate of future cash flow value at US$43.58, below the current US$47.24 share price. Which signal do you trust more for the long haul?
Look into how the SWS DCF model arrives at its fair value.
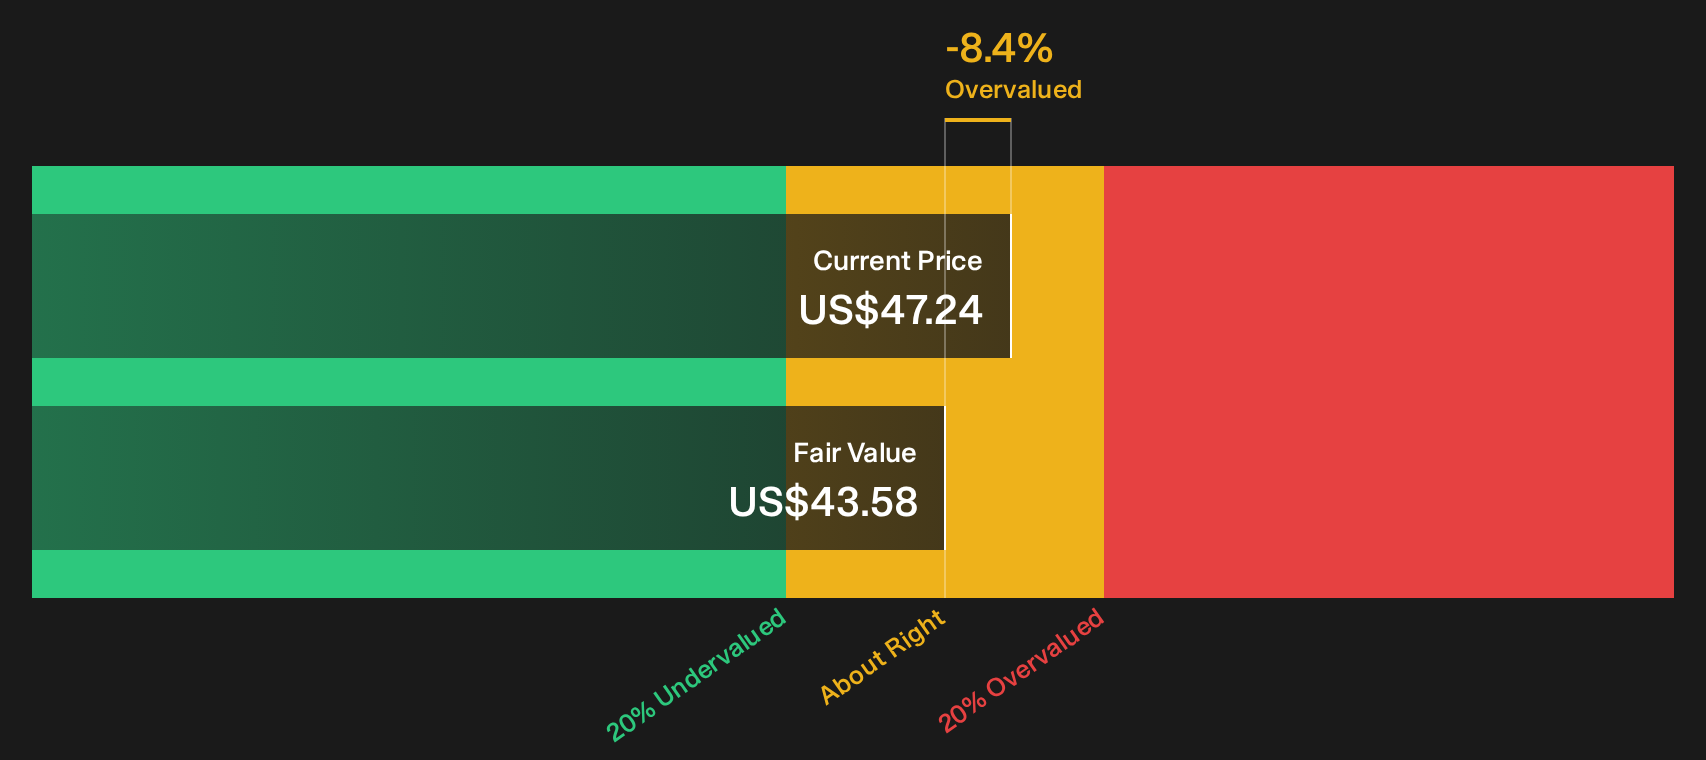
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tecnoglass Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or an early inflection point: either way, Tecnoglass Holdings is giving you plenty of data to test your own thesis quickly. Start with the headline balance of 3 key rewards and 1 important warning sign.
Looking for more Tecnoglass Holdings style opportunities?
If Tecnoglass Holdings has sharpened your focus, do not stop here. Broader idea hunting with structured screeners can highlight overlooked opportunities and sharpen your overall portfolio decisions.
- Target quality at a discount and review a curated group of 32 high quality undervalued stocks that combine appealing pricing with solid underlying fundamentals.
- Prioritize resilience in tougher markets and scan 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- Aim for durability plus income and inspect 6 dividend fortresses that pair higher yields with balance sheet support for ongoing payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com