
UK Stock Market Today: FTSE 100 Futures Edge Lower On Higher For Longer US Rates
The Morning Bull - UK Market Morning Update Thursday, 12 Nov 2026
UK stocks look set for a cautious open, with sentiment leaning defensive as investors absorb hotter than expected US inflation data. The dominant driver today is the shift toward higher for longer US interest rate expectations.
October US CPI and core CPI both came in above forecasts, reviving concerns that US policy may stay tight for longer than markets hoped. This matters because US rates often anchor global borrowing costs and risk appetite, including in the UK.
Higher for longer US yields can push up the floor for UK gilt rates, lifting funding costs for households and businesses. That pressures interest sensitive areas such as housing and stretches equity valuations that rely heavily on distant cash flows.
The open question now is whether upcoming US data such as PPI and jobless claims confirm this stickier inflation trend or offer relief. That data path will shape whether today’s cautious tone in UK markets becomes a new baseline or fades.
Stocks to Watch Before the Opening Bell
Diageo (DGE)
Indian customs have impounded more than 40 containers of Diageo Scotch whisky in a dispute over whether bulk concentrates qualify for reduced tariffs under the UK India trade deal. Officials are applying a 150% duty to these shipments. Investors will be watching for clarity on how this affects Diageo’s access to a key growth market and any changes to the trade agreement.
Glencore (GLEN)
Yancoal Australia has renewed coal trading agreements with Glencore through 2029, including a sales cap of $1.07b for 2027 that then adjusts to $500m in 2028 and $550m in 2029. There is also scope for Yancoal to buy up to $250m of coal from Glencore each year. The refreshed contracts give clearer visibility on medium term trading volumes.
Unilever (ULVR)
The UK Competition and Markets Authority has raised serious concerns about the planned $44.8b to $65b merger between McCormick and Unilever’s food division, flagging risks to competition in dry cooking mixes and sauces. Regulators have set an 18 November deadline for remedies. Unilever has responded by cooperating with the CMA and putting the Colman’s brand up for sale to ease those concerns.
Top Movers
- ASOS (LSE:ASC) jumped 6.88% after an Investec upgrade to Buy and news of a renewed GXO logistics contract.
- Funding Circle Holdings (LSE:FCH) climbed 6.84% following another upgrade to full year profit guidance driven by strong SME borrowing demand.
- Watches of Switzerland Group (LSE:WOSG) advanced 5.86% after reporting 15% H1 revenue growth and lifting its FY27 guidance and margin outlook.

Top Losers
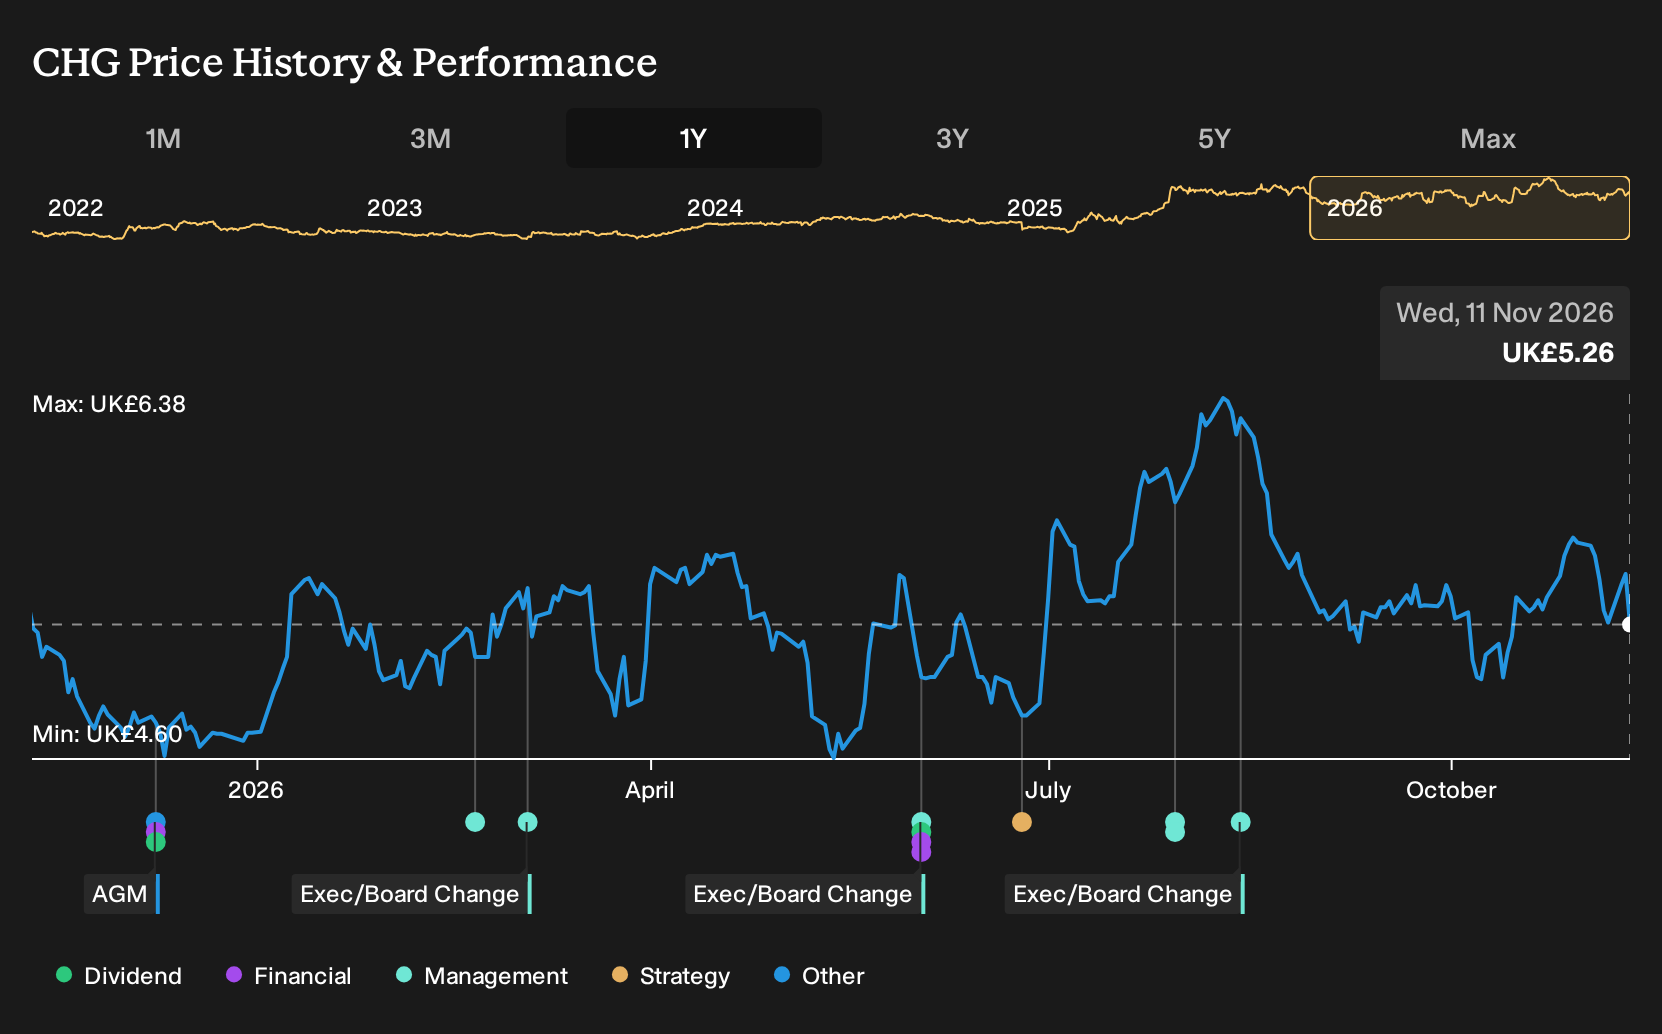
- Chemring Group (LSE:CHG) fell 4.54%.
- Taylor Wimpey (LSE:TW.) declined 4.49% after cutting 2026 home completions guidance and highlighting pressure from higher mortgage rates.
- Ferrexpo (LSE:FXPO) dropped 3.67% after suspending Ukrainian production because power supply disruptions halted normal mining operations.
On The Radar
UK macro data and a dense run of domestic earnings over the next few days focus attention squarely on growth, inflation and how UK companies are handling higher funding costs.
- UK Q3 GDP releases Thu 12 Nov. Quarterly growth consensus stands at 0.7% with 1.9% year on year, so a softer print could reinforce pressure on UK domestic cyclicals, while a firmer outcome may steady gilt yields and the pound.
- UK September activity and trade set Thu 12 Nov. Monthly GDP at 0% consensus, industrial output forecast around a 0.3% fall and a goods trade gap near £19.2b will help shape how investors treat exporters versus more inward facing sectors.
- WH Smith Thu 12 Nov. Full year 2026 results put the spotlight on travel outlets versus high street stores, with revenue trends and margin commentary likely to guide expectations for UK consumer spending and travel related shares.
- Burberry Group Thu 12 Nov. First half 2027 figures will focus on sales momentum in luxury fashion and margins in key regions, which is relevant for how investors treat premium consumer brands listed in London.
- UK October CPI Wed 18 Nov. Headline inflation is forecast at 3.5% with core at 2.9%, and a reading meaningfully above or below those marks could sway Bank of England rate expectations and interest rate sensitive UK sectors.
Sector & Industry Watch
Real Estate: Higher mortgage costs hit sentiment
Real Estate has eased slightly over the past week after a stronger month, while the latest RICS report points to the bleakest short term house sales outlook since 2023. Higher mortgage rates mean stretching for a new home is harder, which feeds directly into estate agents, landlords and listed housebuilders.
The fresh RICS House Price Balance reading out today is the key signal for this group, because a softer result would underline that pressure on transaction volumes is still in place.
Consumer Discretionary: Retailers caught between data and rates
Consumer Discretionary has slipped over the last seven days even after a better 30 day patch, with names such as Taylor Wimpey reminding investors how exposed the sector is to borrowing costs. The company cutting its 2026 completions outlook links directly back to higher mortgage rates and a weaker autumn selling season.
For anyone holding UK focused retailers, housebuilders or leisure stocks, this morning’s UK Q3 GDP release is the swing factor to watch, since it shapes views on how confident households feel heading into Christmas spending.
Airlines: Strong week as easyJet heads for exit
Airlines have built on recent strength over the past week, helped by sector wide gains and easyJet shareholders backing the £5.7b Apollo takeover. A private equity buyer stepping in suggests continued interest in UK listed carriers even as wider consumer data stay mixed.
The trend meets an important test with today’s UK Q3 GDP numbers, because any surprise on growth will quickly filter into expectations for holiday and business travel budgets.
Energy and Oil and Gas: Sector drifts while oil stays in focus
Energy and Oil and Gas are down over the last seven and thirty days despite clearly positive year to date and 12 month returns. Moves in BP and Ithaca Energy show how quickly share prices can react when crude prices shift or geopolitical headlines point to possible supply risks.
The near term catalyst is tonight’s US crude inventory data from the EIA, since a sharp build or draw can move global oil benchmarks that feed straight into revenue expectations for UK producers and refiners.
Telecom: Softer shares as ad spending wobbles
Telecom has retreated over the last week even though 12 month performance for the sector remains positive, with ITV flagging weaker fourth quarter advertising demand. When marketers trim budgets, companies that rely on TV and media ad slots often feel it quickly in revenue and profit.
For investors in Telecom and media stocks the macro release that matters most is next week’s UK labour market and wage data, because pressure on household incomes tends to affect choices around phone, broadband and streaming contracts.
Find Tomorrow's Top Performers
With higher mortgage rates putting fresh pressure on UK housing and consumer sectors, start your next idea hunt with this list of 208 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com