
What BAWAG Group Holders Got Right
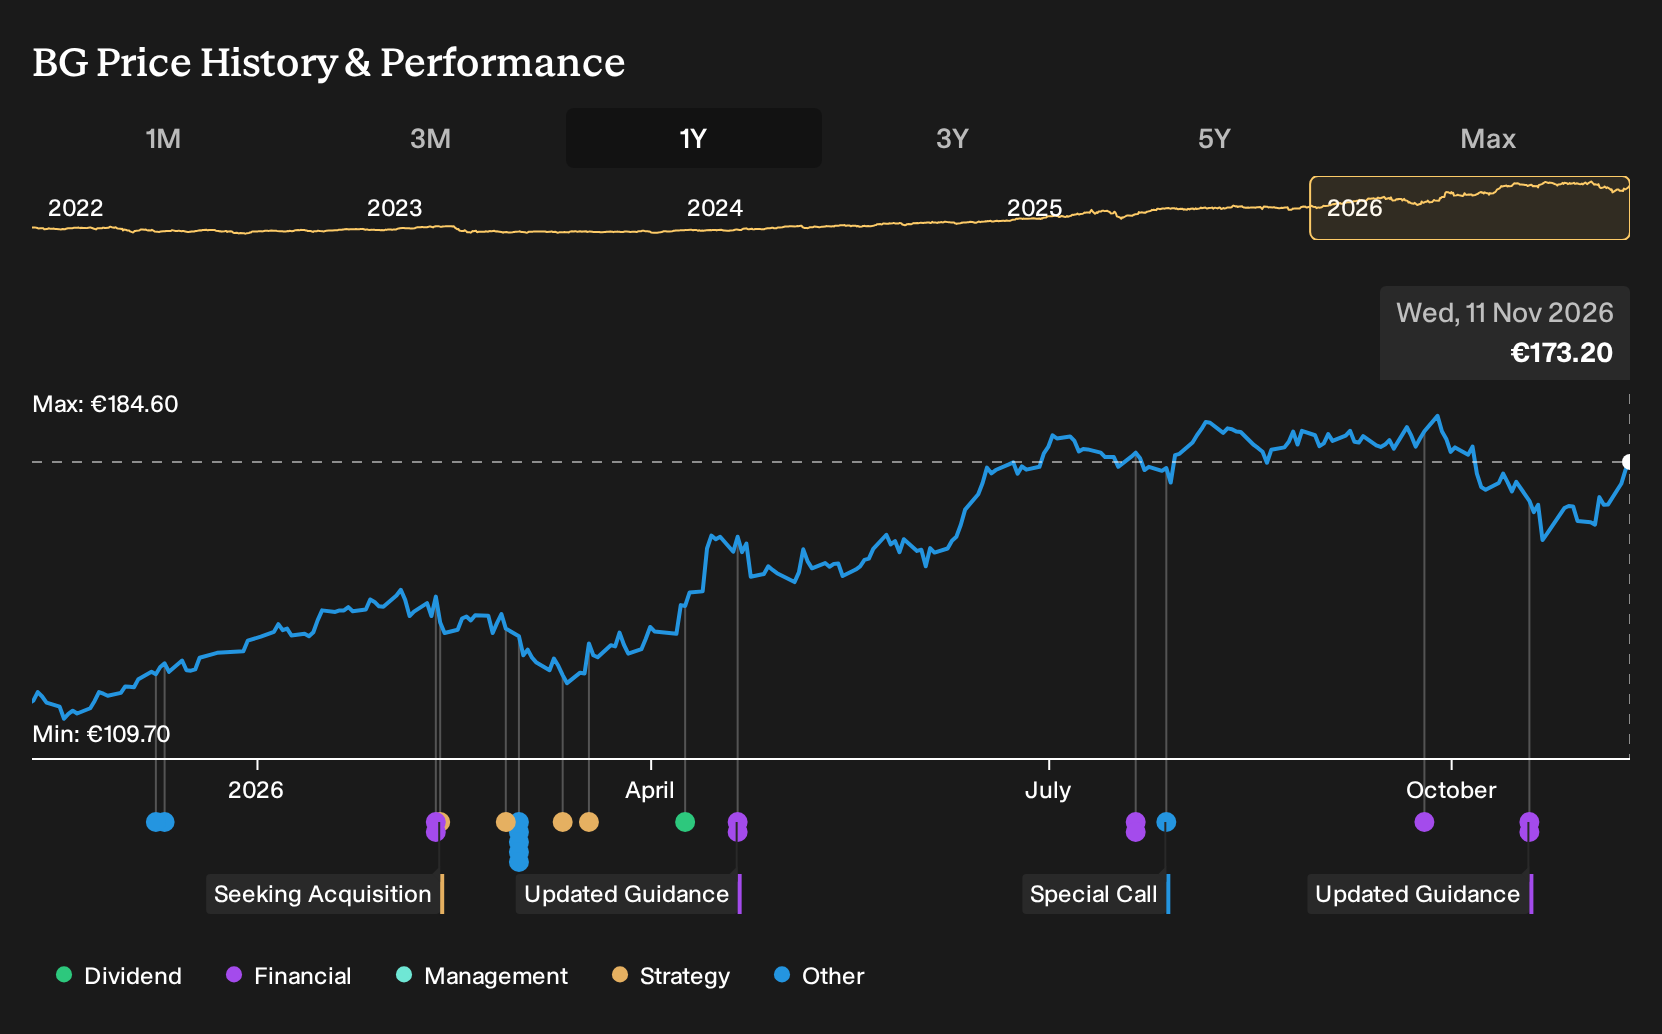
Regulatory approval from the European Central Bank for BAWAG Group’s planned acquisition of Permanent TSB turned a theoretical consolidation story into a concrete cross border deal. For BAWAG Group shareholders, the return over the past year was 55.3%, including dividends. If you had been weighing a purchase back on 2025-11-11, what would you have needed to believe about digital execution, integration risk and European banking consolidation before that approval arrived?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made BAWAG Group harder to judge, start where the gap is still open and scan 197 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On BAWAG Group
The shares cost €114 at the start of the period, and anyone looking at BAWAG Group then had to choose between two very different stories about digital banking and consolidation in Europe.
On the bullish side, one narrative put Fair Value at €141, or 24% above the start price. This view assumed BAWAG's digital banking platform and integrations would help revenue increase 14.6% a year with earnings reaching €1.1b by 2028.
The bearish view set Fair Value at €79, or 31% below the start price, and focused on risks. That case assumed fintech competition and reliance on DACH and Netherlands markets would limit revenue growth to 5.8% a year and justify only an 8.1x P/E in 2028.
What The Evidence Around BAWAG Group Actually Tested
The key event was ECB approval for BAWAG Group’s planned Permanent TSB purchase, which backed parts of the optimistic consolidation story. At the same time, Q3 2026 results showed revenue at €526.2m and net income at €247.5m, with net margin at 47.0%. That combination supported the optimistic case on profitability, while still leaving long term integration risk open.
The useful lesson is to tag any takeover story to hard follow up checks. For similar banks, track post deal revenue, net profit and margin against what management outlined on announcement day.
What BAWAG Group's Run Up 55% Has Not Resolved
BAWAG Group now trades at €173, after a 55.3% total return over the past year. The bullish analyst Narrative on Simply Wall St still places its Fair Value above that level, based on a view that earnings power and capital deployment remain underappreciated.
The crux is whether you believe the market fully recognises what disciplined deal making, a heavier unsecured mix and years of tech spend could mean for long run profitability. This Narrative argues today’s price still does not credit BAWAG sustaining a very lean cost base while absorbing PTSB and a riskier loan book.
"The shift in BAWAG Group’s loan book toward unsecured consumer, SME and especially credit card lending in markets such as Germany creates room for a richer asset mix, which can support higher net interest margin and fee income over time as the higher-yielding portfolio seasons. The extensive use of significant risk transfer structures on around €9 to €10b of mortgages and unsecured exposures provides scope to redeploy capital into new lending or fee businesses with different risk and return profiles, which can influence future earnings and return on tangible equity."
The price and this Narrative do not agree. → Uncover what this Narrative says BAWAG Group is actually worth
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 37% below our estimate - handles freight and customs work serving AI hardware and compliance logistics.
- Company 2 - 39% below our estimate - extends a dairy platform into nutrition, specialty ingredients and plant based offerings.
- Company 3 - 38% below our estimate - tackles complex technical disputes requiring deeper scientific and regulatory-focused analysis.
Those are three of them. See every one of the 193 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com