
Semtech Stock In Focus After Global IoT ESIM Launch
- Semtech has released its SGP.32 Smart Connectivity Premium eSIM, a global multi-network, multi-profile offering that combines Semtech and mobile network operator profiles in the AWS hosted AirVantage platform for orchestration, provisioning and lifecycle management across diverse IoT deployments.
- The single SKU, multi profile design, including the PowerSave eSIM for battery constrained devices, aims to simplify logistics, address permanent roaming restrictions and support resilient IoT connectivity across fixed and mobile uses through automated profile downloads and switches.
- We will look at how Semtech's investment narrative intersects with this multi profile eSIM launch that targets scalable global IoT deployments.
Semtech Investment Narrative Recap
To own Semtech, you need to believe the analyst consensus Narrative on Simply Wall St that AI data center optics and LoRa IoT remain the twin engines that justify higher R&D, portfolio reshaping and current valuation. The SGP.32 eSIM launch fits that view only at the margin. It supports IoT systems and connectivity, but does not change the center of gravity, which is high margin data center silicon.
In the near term, the key swing factor stays execution on that data center plan while holding gross margins close to the mix targets management has discussed. The biggest risk still sits in heavy R&D and portfolio clean up. If IoT platforms like AirVantage absorb capital and attention without matching returns, it could weigh on earnings progress and delay the multiyear margin story.
The SGP.32 Smart Connectivity Premium eSIM launch links directly to Semtech’s LoRa and IoT Systems and Connectivity ambitions. One SKU, a GSMA SGP.32 compliant eSIM applet and AWS hosted AirVantage orchestration all support the objective of scaling device counts without exploding operational overhead. That matters if IoT is going to meaningfully complement data center growth rather than remain a side business.
Among the recent developments, the Electronica 2026 presence is the one that sits closest to this story. Electronica is where customers evaluate concrete solutions, not just slides. Pairing a live SGP.32 demo with discussion of hyperscale optics, LoRa Plus and divestiture of lower return cellular modules gives Semtech an opportunity to show that IoT connectivity, cloud tooling and high end semiconductors can coexist in one tighter, higher margin portfolio.
Semtech Forecasts Behind the IoT Connectivity Story
Semtech's narrative projects US$3.0b revenue and US$1.1b earnings by 2029. Analysts are assuming revenue will rise at about 36.9% per year and earnings would need to climb by roughly US$946.0m from about US$154.0m today to reach that level.
The forecast path matters for how investors frame the SGP.32 Smart Connectivity Premium eSIM announcement. Analysts are working off revenue growth assumptions near 37% a year over the next three years, paired with margin expansion from roughly 13.1% today to 35.0% around 2029. That model underpins the expectation for earnings to move from about US$154.0m now to roughly US$1.1b, so the projected increase in profit is very large compared with where Semtech is starting.
Against that backdrop, SGP.32 and the AirVantage hosted orchestration stack sit in the supporting cast. The multi profile eSIM, global multi network reach and PowerSave option for battery constrained devices all point toward IoT connectivity that can scale without adding equivalent support costs. If that plays out in line with analyst assumptions, it would help the LoRa and IoT Systems and Connectivity segment pull its weight in a world where the market already expects data center oriented earnings to grow several times from current levels.
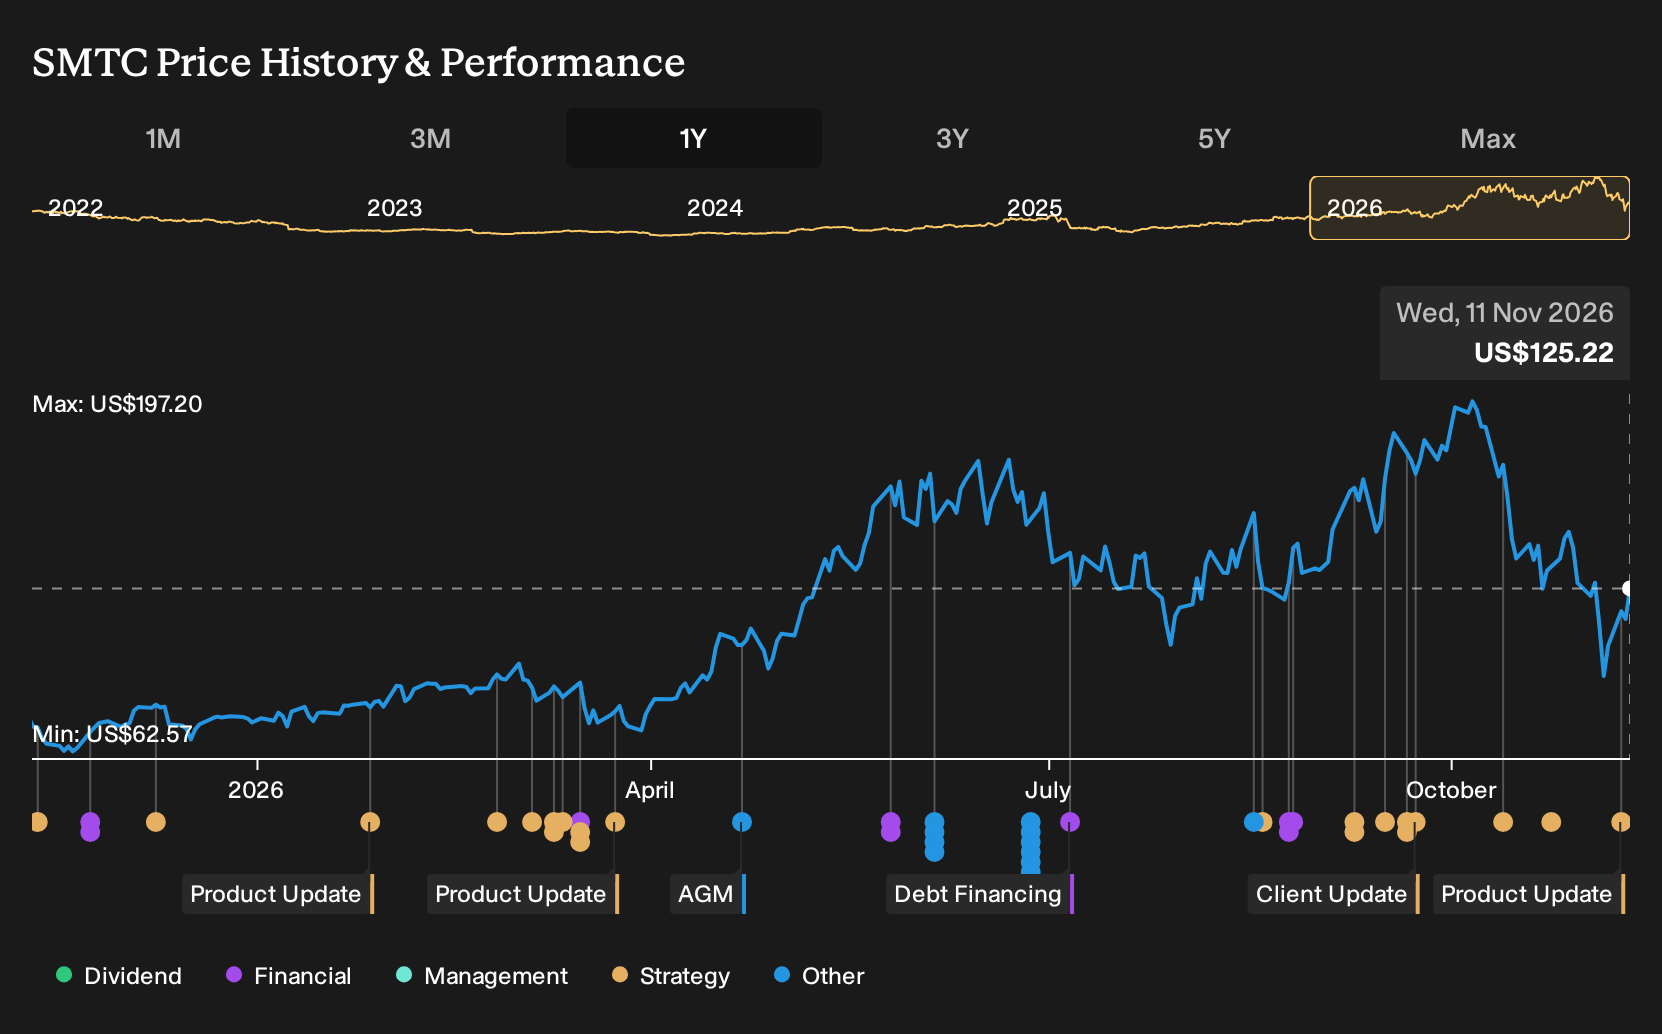
There is also a valuation layer to this story. Consensus numbers imply roughly US$3.0b in revenue and US$1.1b in earnings by 2029, with the stock trading on a P/E of 27.3x those projected profits compared with about 77.2x today and a US semiconductor sector average near 43.5x. The current analyst target of US$217.07, versus a share price of US$127.42, assumes that revenue, profit and margin trajectory holds together even as Semtech tries to fund SGP.32 driven IoT growth and heavy AI optics R&D out of the same cash flow pool.
Uncover how Semtech's fair value indicates a 73% potential upside to its current price.
Exploring Other Perspectives
Some of the lowest Semtech forecasts lean hard into a different worry. They focus on AI data center demand cooling, not on SGP.32 style IoT wins. Those analysts were still penciling in about US$2.9b revenue and US$1.1b earnings by 2029, yet pairing that with a lower 22.2x P/E. That more cautious stance shows how far opinions can spread. Use this SGP.32 launch as a reason to compare both stories and decide which assumptions feel more realistic to you.
Explore 2 other Semtech fair value estimates, including one that suggests it could be worth just $204.78!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Semtech research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Semtech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Semtech's overall financial health at a glance.
Looking For More Ideas Beyond Semtech?
If Semtech's SGP.32 story has you thinking about where else scaled connectivity, strong balance sheets and disciplined capital use might matter, it can help to scan a wider field of stocks that fit different risk and quality profiles using the Simply Wall St Screener.
- For investors who want quality and valuation working together, start with a curated set of companies that screen as 32 high quality undervalued stocks based on earnings, cash flow and balance sheet strength.
- If capital preservation ranks high on your checklist, focus on stability by checking a 30 resilient stocks with low risk scores that tend to score well on volatility, financial health and business risk indicators.
- When you are hunting for resilient businesses with room to grow, use a 19 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com