
3 US Bank Stocks That Could Benefit If Short Term Rates Stay Higher
Inflation is proving sticky, the Federal Reserve is again in the spotlight, and short-term interest rates are back to being a powerful force rather than background noise. When policy stays restrictive and cash suddenly pays more, some financial stocks feel the pinch while others quietly gain new ways to earn. This article unpacks that split and walks through 3 large U.S. bank and insurer stocks that screen as potential beneficiaries of higher short-term rates.
The three stocks below are a small sample of this idea, and the full screen surfaced 39 more large U.S. banks and insurers with equally compelling stories that are not covered here.
To go deeper on the full universe of rate beneficiaries, head straight into the U.S. Large Bank and Insurer Beneficiaries of Higher Short-Term Rates screener to identify, filter, and analyze the candidates that best fit your own portfolio thesis.
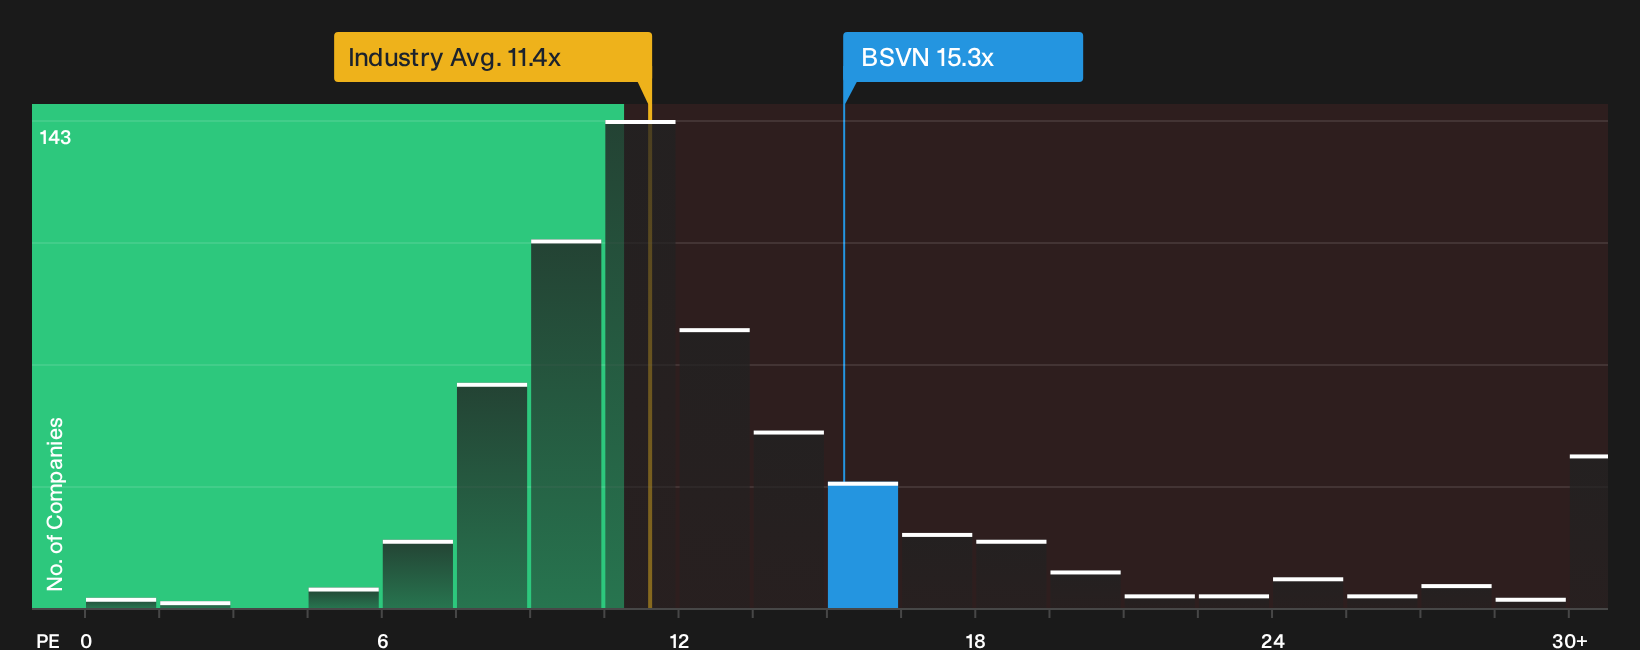
Bank7 (BSVN)
Bank7 plugs directly into the higher short-term rate story that drives this screener. Its loan and deposit engine is built on commercial relationships across Oklahoma, Texas and Kansas. The analyst consensus Narrative on Simply Wall St frames how that funding base might shape earnings power if policy stays tight.
"Planned use of Century’s lower cost core deposits and the option to reposition its securities portfolio, while aiming to keep core net interest margin in the roughly 4.40% to 4.55% range, could support relatively resilient net interest income across different rate scenarios."
What happens if one unseen pressure on funding costs moves faster than expected will matter a lot for how those ambitions translate into shareholder returns.
That funding risk cuts both ways, and the full narrative for Bank7 shows how Bank7’s earnings power could accelerate if that pressure eases rather than intensifies.
CVB Financial (CVBF)
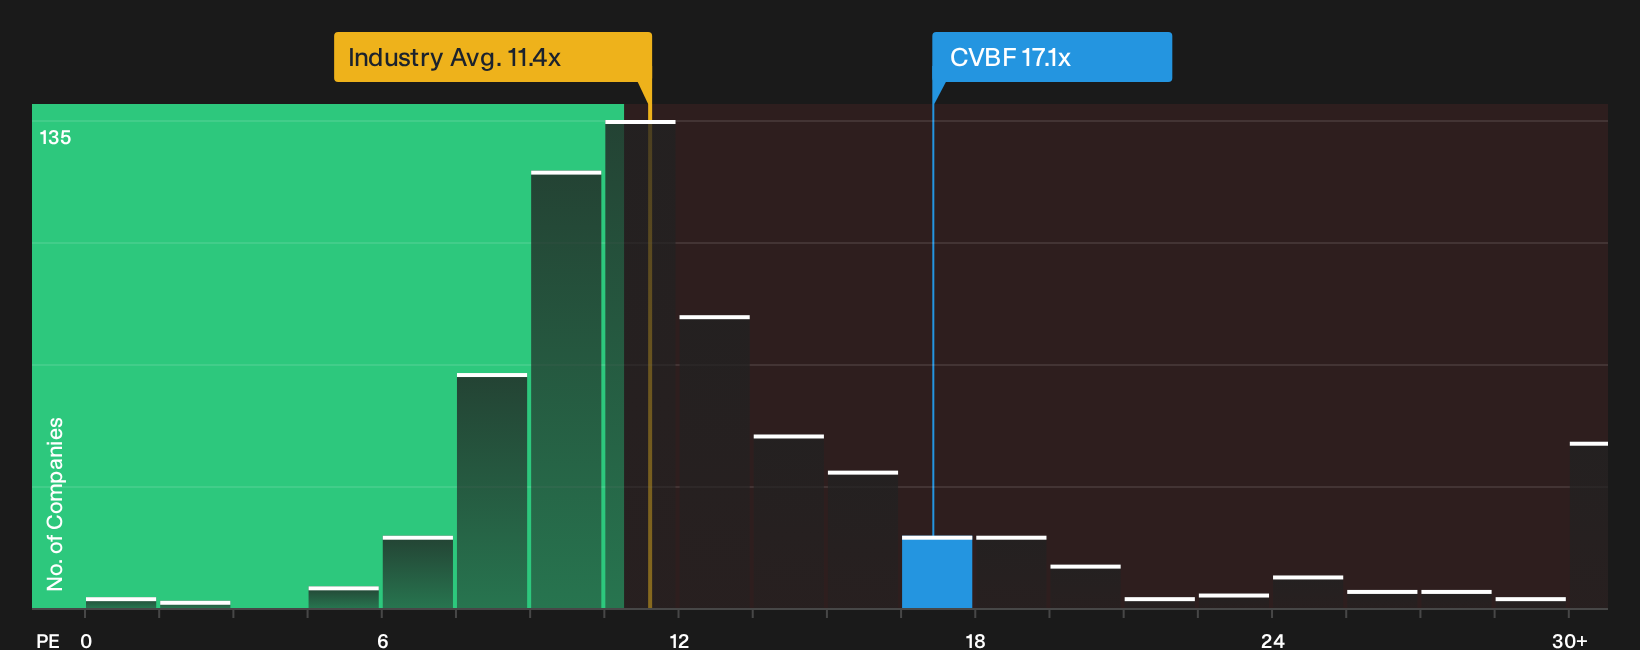
CVB Financial plugs into this higher short-term rate theme through its focus on business and personal banking in California, where loan and deposit repricing matter for earnings power. The analyst consensus Narrative on Simply Wall St explains why its balance of low-cost funding and lending scale has drawn attention.
"The decision to keep noninterest-bearing deposits at 53% of total deposits while holding the overall cost of funds at 0.96% positions CVB Financial to defend net interest margins and support earnings, assuming loan growth continues on this low-cost funding base."
What happens if one key assumption in that funding mix and loan growth equation shifts faster than expected could meaningfully influence shareholder outcomes.
CVB Financial is a US$3.95b California based bank holding company for Citizens Business Bank, earning about US$641 million from banking services to businesses and individuals in the United States, with the screener highlighting how its broad lending and deposit franchise ties directly into higher short-term rate economics.
If that funding mix does start to shift, the full narrative for CVB Financial shows where CVB Financial’s earnings power could accelerate or be masked by headline numbers.
Dime Commercial Bancshares (DCOM)
Dime Commercial Bancshares leans into the higher short-term rate theme as a commercial-focused bank, using its loan and deposit base to generate income from lending and fee services. It earns about US$458 million from community banking and carries a market value of roughly US$1.9b.
The analyst consensus Narrative on Simply Wall St points to a commercial lender whose sensitivity to higher policy rates is starting to show up in the numbers. One datapoint in particular captures how the balance sheet is positioned for a higher-for-longer rate backdrop.
"The scheduled repricing or maturity of about US$2.5b of fixed and adjustable-rate loans at an average rate of 4.25% over the next 18 months provides a clear path for higher earning asset yields, which is expected to feed into net interest margin and earnings over the next several years."
What happens if one unseen pressure on funding costs or credit quality moves quicker than expected could heavily influence how that margin story plays out.
If that margin story has your attention, the full narrative for Dime Commercial Bancshares explains how Dime Commercial Bancshares’ repricing profile and funding risks could translate into either accelerating or stalled earnings power.

Seeking Fresh Alternatives Before They Fly
New themes can build momentum quickly, and notable breakout stories are often identified early while they are still under the radar. Before the opportunity narrows, consider exploring potential options now.
- Target dependable income streams by scanning a curated set of potential high-yield opportunities through the 6 dividend fortresses before competition tightens around the same payouts.
- Look for quality at more attractive prices by running the 32 high quality undervalued stocks and identifying financially solid businesses that screens flag as potential value before sentiment changes.
- Focus on durability by using the list of solid balance sheet and fundamentals (23 results) so you can concentrate on financially grounded companies while broader market attention may still be limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com