
Raised Outlook Could Be A Big Moment For Watts Water Technologies Stock (WTS)
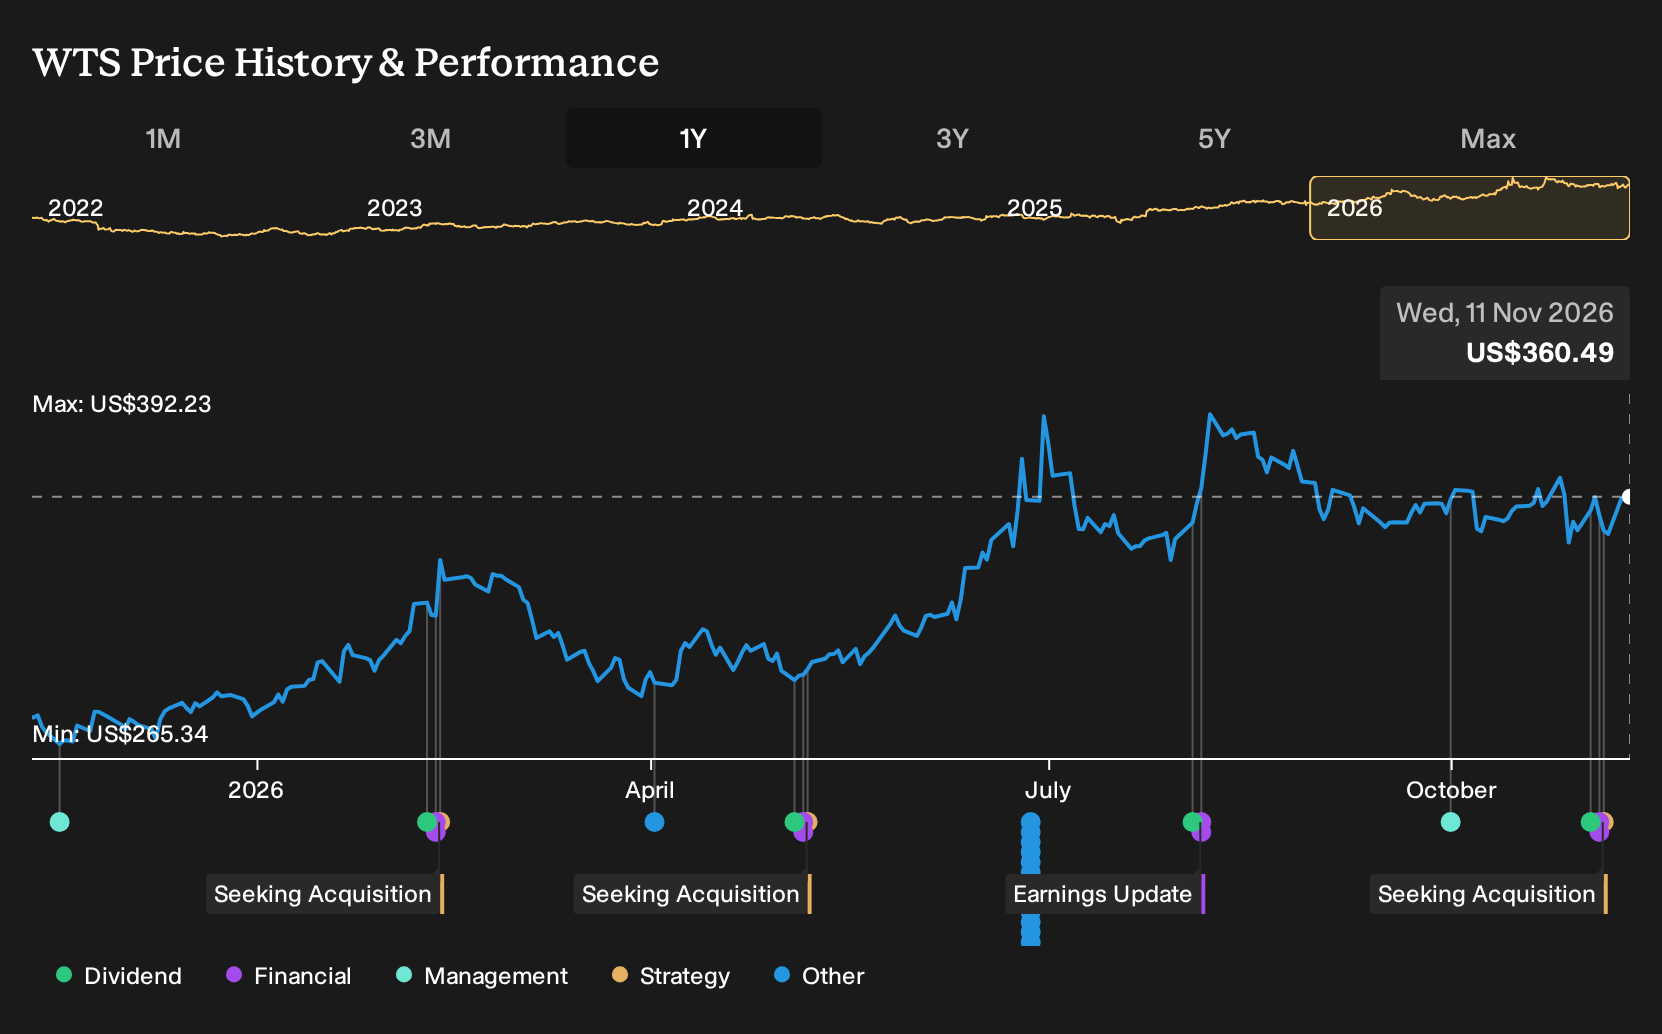
- Watts Water Technologies reported third quarter 2026 sales of US$728 million and net income of US$145.4 million, raised full year 2026 guidance for sales growth to a range of 17% to 18% and operating margin to a range of 21.6% to 21.7%, and affirmed a US$0.63 quarterly dividend payable in December 2026.
- Management highlighted a strong M&A pipeline and plans to deploy capital across internal projects, data center related inventory, factory automation and disciplined acquisitions, with the stated aim of supporting sustainable, profitable growth while continuing to return cash to shareholders.
- This article examines how the Watts Water Technologies investment narrative is influenced by the stronger margin outlook signaled in the raised 2026 guidance.
Scan beyond Watts Water Technologies and compare its acquisition driven playbook with a curated group of 19 high quality undiscovered gems pursuing growth through disciplined capital deployment.
Watts Water Technologies Investment Narrative Recap
To own Watts Water Technologies, you need to believe the business can keep turning its repair and replacement base, higher margin mix, and data center exposure into resilient cash generation while managing regional softness. The raised 2026 margin outlook and strong third quarter earnings suggest operations are currently tracking well against that belief.
The key short term swing factor is execution on data center related demand and the 80/20 product rationalization, which are central to the analyst consensus Narrative on Simply Wall St. The largest risk remains that European construction weakness or underwhelming benefits from product pruning leave margins and growth below current expectations.
The raised 2026 guidance is the announcement that most directly ties into this story. Management now expects full year sales growth of 17% to 18% and an operating margin of 21.6% to 21.7%. That sits alongside third quarter sales of US$728 million and net income of US$145.4 million, which provide a current snapshot of profitability.
For catalysts, that outlook frames how you judge future M&A, data center inventory investment, and factory automation spending. Execution risk cuts both ways. If integration, pricing, and cost control stay aligned with the new margin range, the guidance becomes an operational benchmark. Any stumble on acquisitions, Europe, or the 80/20 program would challenge it quickly.
Watts Water Technologies is framed around analysts expecting revenues of US$3.3b and earnings of US$545.4 million by 2029, based on an assumed 5.4% yearly revenue growth rate and an earnings increase of about US$98.4 million from current earnings of US$447.0 million.
Discover why Watts Water Technologies' fair value points to a 10% potential upside to its current price before that discount closes.
Exploring Other Perspectives
You see the data center story very differently if you follow the lowest analysts. They worry that rapid data center growth, now 8% of Watts Water Technologies sales, could reverse and leave recent investments exposed. Before this guidance upgrade, they were modeling about US$3.3b of 2029 revenue and roughly US$552.3 million of earnings. That is still solid, yet meaningfully more cautious than the baseline view. These estimates all pre date the latest guidance and M&A comments, so treat them as starting points and explore several viewpoints before deciding how this new information might reshape the picture.
Explore 4 other Watts Water Technologies fair value estimates, including one that suggests it could be worth just $360.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Watts Water Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Watts Water Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Watts Water Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Watts Water Technologies?
If the Watts Water Technologies story has sharpened your thinking on margins, capital allocation, and earnings quality, you can use that same lens to screen for other opportunities. The Simply Wall St Screener can help you quickly narrow the universe to stocks that fit the risk, return, and balance sheet profile you care about most.
- For investors who want income and resilience side by side, check out 6 dividend fortresses to find candidates that aim to pair higher yields with balance sheets built to handle stress.
- If downside protection matters most to you, start with 30 resilient stocks with low risk scores to focus on businesses with more measured risk profiles and sturdier fundamentals.
- When you want quality that is still flying under the radar, scan through 19 high quality undiscovered gems to look for companies that combine sound financials with less crowded shareholder registers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com