
Does Investor Day Update Change The Bull Case For Worthington Enterprises Stock (WOR)?
- Worthington Enterprises recently held its 2026 Investor and Analyst Day, outlining its post separation structure, financial profile, and long term opportunities across consumer, building products, and pressure containment platforms.
- Management described the Worthington Business System and higher margin building products acquisitions as central levers for reinvestment capacity and potential value creation across the portfolio.
- We will now look at how Worthington Enterprises' refreshed long term strategy from Investor Day could influence the existing investment narrative.
Scan how Worthington Enterprises' post separation focus compares with other potential compounders by running the hand picked 19 high quality undiscovered gems alongside your own watchlist.
Worthington Enterprises Investment Narrative Recap
To own Worthington Enterprises, you need to be comfortable with a mid cap manufacturer that is focusing on consumer and building products, where execution on the Worthington Business System and higher margin building offerings matters more than broad macro swings. The analyst consensus narrative on Simply Wall St emphasizes continued earnings growth and solid free cash conversion from this mix.
Right now, the near term swing factor is how efficiently Worthington Enterprises can integrate acquisitions like Elgen and LSI while keeping gross margin and adjusted EBITDA intact. The biggest risk is that steel price volatility, tariffs or construction softness could pressure ClarkDietrich equity income again, which would make the consolidated earnings picture more volatile.
The recent Investor and Analyst Day is the key announcement to focus on, because it outlined Worthington Enterprises’ post separation plan across consumer, building products and pressure containment. Management described its capacity for reinvestment using the Worthington Business System and higher margin building products as the core playbook for the next few years.
For catalysts, that update sits alongside product launches like SureSense and Balloon Time Mini, the data center ASME tank platform and big box partnerships with Tractor Supply and Walmart. The Investor Day message outlines expectations for how quickly these pieces might scale and how much integration or execution risk investors may wish to factor into their own assumptions.
What the Analyst Framework Implies for Worthington Enterprises
Worthington Enterprises' narrative projects US$1.7b revenue and US$230.1 million earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$66.6 million from current earnings of US$163.5 million.
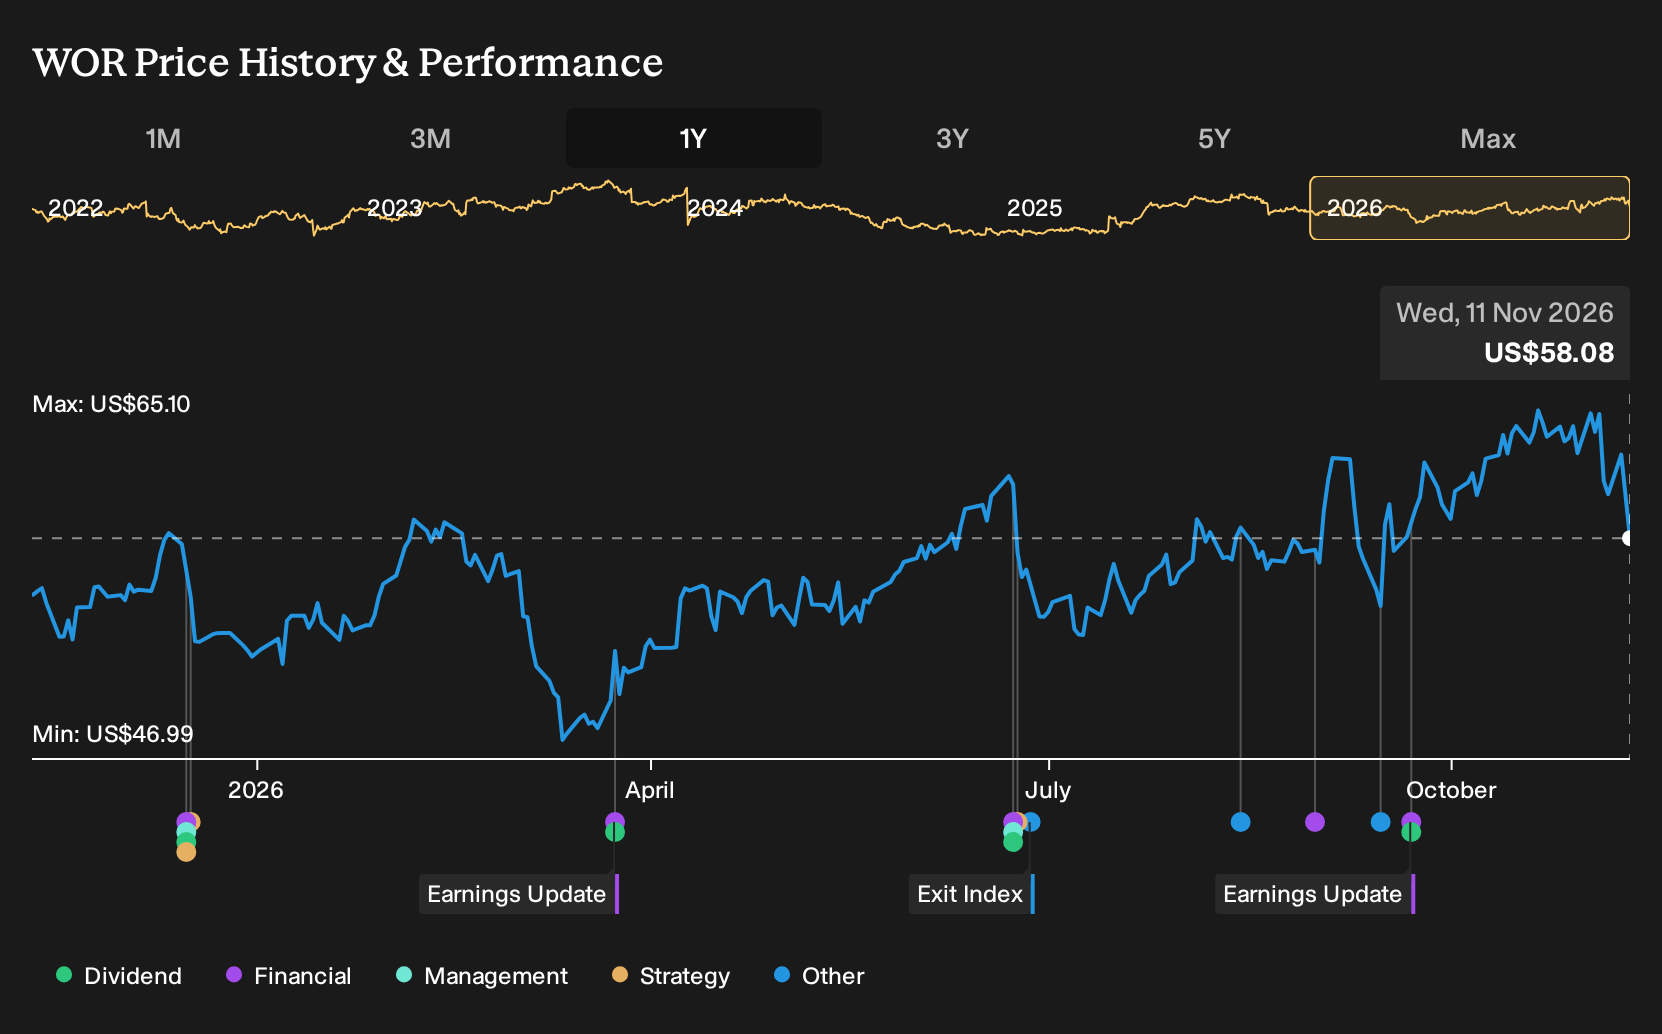
Uncover why Worthington Enterprises' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One friction point the more cautious analysts focus on is steel availability. Before this Investor Day update, the lowest forecasts already baked in revenue of about US$1.6b and earnings near US$232.6 million by 2029, paired with a lower 14.8x P/E. That group suggests Worthington Enterprises has less room for disappointment, so use this event to compare several viewpoints and stress test your own expectations.
Explore another Worthington Enterprises fair value estimate, including one that suggests it could be worth just $70.40!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Worthington Enterprises research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Worthington Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Worthington Enterprises' overall financial health at a glance.
Looking for more investment ideas beyond Worthington Enterprises?
Once you have a handle on Worthington Enterprises, it can help to widen the lens and see which other businesses fit the kind of quality, income, or resilience profile you are aiming for in your portfolio by using the Simply Wall St Screener.
- If your focus is on quality at a reasonable entry point, scan a curated lineup of companies trading below estimated value using the 32 high quality undervalued stocks.
- If dependable income is your priority, narrow in on potential high yield payers with the 6 dividend fortresses and see which businesses might align with your dividend goals.
- If capital preservation matters most, filter for companies with stronger balance sheets and steadier fundamentals through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com