
How Investors May Respond To Northrop Grumman Stock Conference Appearance
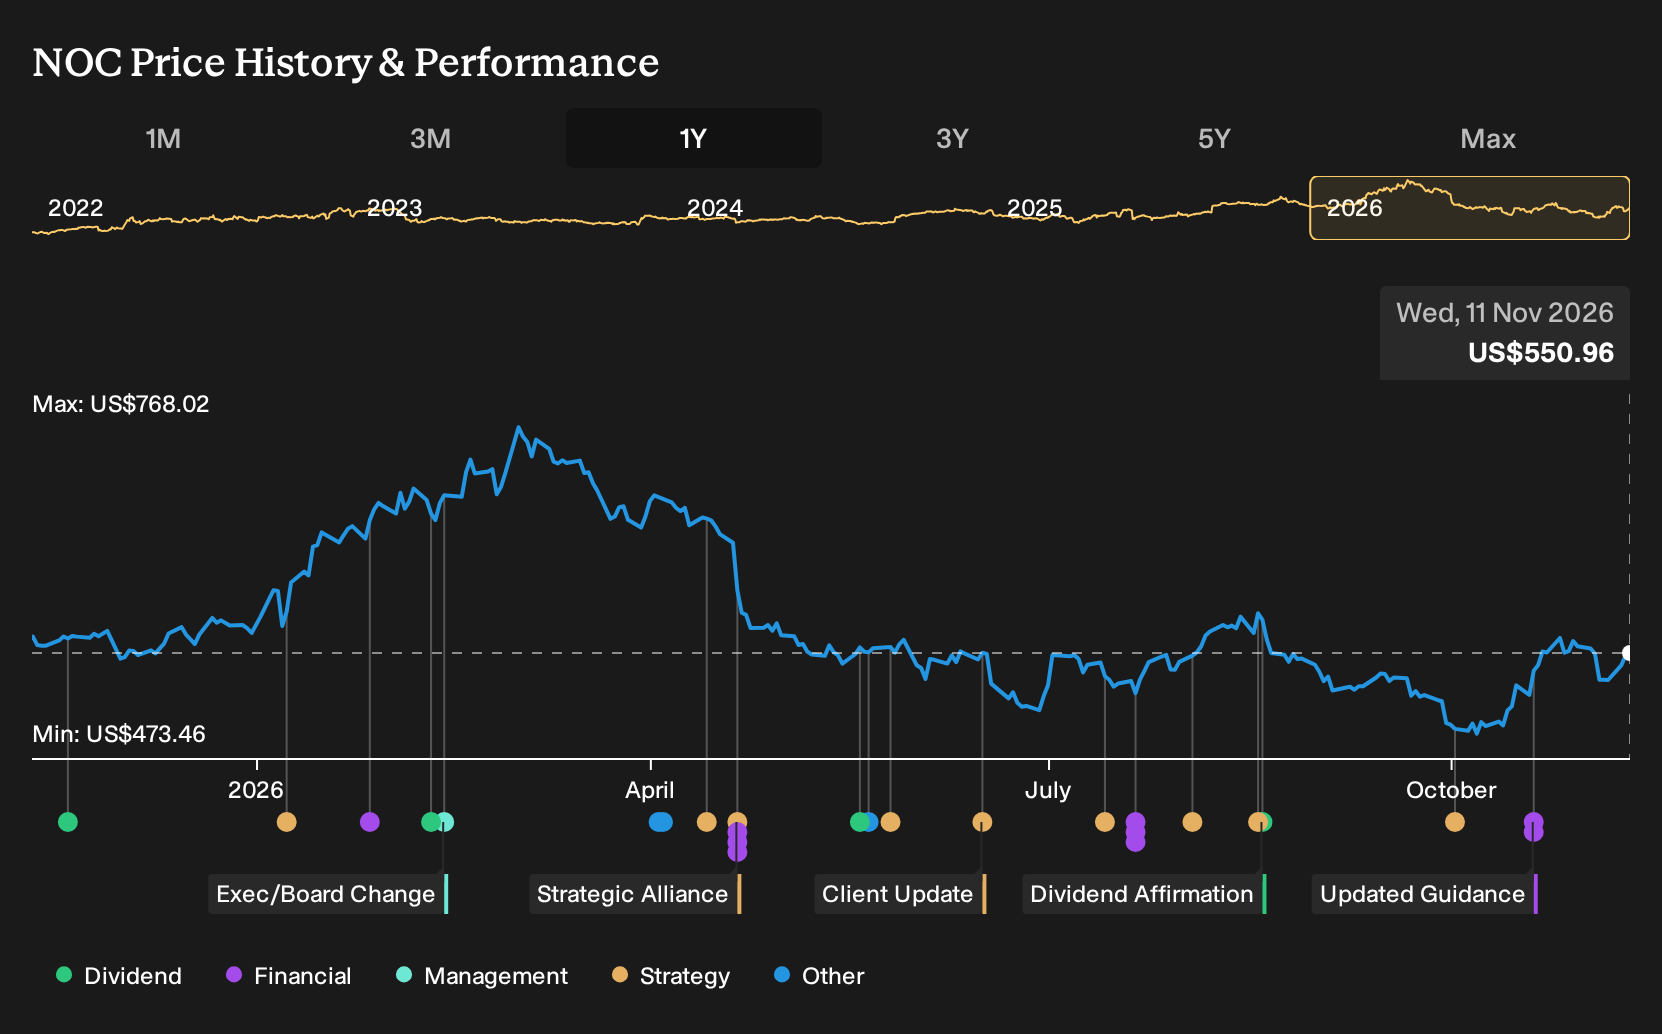
- Northrop Grumman recently presented at the Baird 2026 Global Industrial Conference in Chicago, where CEO Kathy Warden outlined the business to institutional investors.
- The presentation came as the company expands munitions and solid rocket motor capacity under multi year missile acceleration agreements worth up to US$10b.
- We will now look at how Northrop Grumman’s conference spotlight and capacity expansion could influence its longer term investment narrative.
Scan for other defense and aerospace stocks showing similar momentum in earnings revisions and technical strength by running the curated 32 high quality undervalued stocks alongside Northrop Grumman today.
Northrop Grumman Investment Narrative Recap
To own Northrop Grumman, you basically need to believe its record backlog, missile work and national security space franchises can keep feeding steady contract flow while margins hold up through big program ramps. The recent technical strength and earnings estimate revisions in the analyst consensus Narrative on Simply Wall St highlight that the near term story hinges on smooth execution more than fresh headlines.
Right now the key short term swing factor is whether high capital spending on munitions and solid rocket motor capacity turns into profitable volume without fresh contract issues. The biggest risk is still cost or schedule setbacks on complex fixed price programs at the same time as any cooling in U.S. defense budget support.
The most relevant piece of recent news for that debate is the expansion of munitions and solid rocket motor capacity backed by up to US$10b of multi year missile acceleration agreements. That is where Northrop Grumman is putting real money to work, and where investors are watching closely to see if higher throughput translates into solid segment profitability.
Those missile agreements tie directly into the catalysts described in the analyst consensus Narrative on Simply Wall St, which leans on munitions volume, B 21 and Sentinel production phases, and growing space activity to support future earnings. Execution against those contracts, plus managing debt and capex so free cash flow does not get squeezed too hard, will likely shape how durable the current “undervalued and good relative value” view really is.
Northrop Grumman's narrative projects US$52.1b revenue and US$4.8b earnings by 2029. That profile is built on analysts assuming 6.1% yearly revenue growth, along with an earnings increase of about US$0.3b from US$4.5b today.
Uncover why Northrop Grumman's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts margin risk front and center. The most bearish analysts worry that issues like the SiAW and GEM 63XL redesigns keep repeating, which is why they were only penciling in about US$49.9b of revenue and US$4.2b of earnings by 2029 before this conference news. That is a far more cautious Northrop Grumman story than the consensus. Use it as a reminder that opinions differ widely, and treat this latest capacity expansion as a fresh reason to compare several narratives before deciding what you believe.
Explore 2 other Northrop Grumman fair value estimates, including one that suggests it could be worth just $579.50.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Northrop Grumman research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Northrop Grumman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northrop Grumman's overall financial health at a glance.
Looking For More Investment Ideas Beyond Northrop Grumman?
If you want to cross check the Northrop Grumman thesis against other opportunities, broaden your watchlist using the Simply Wall St Screener. It can help you spot different types of businesses that match your risk tolerance, income needs, or preference for balance sheet strength.
- Prefer companies with stronger finances and less balance sheet stress, so short term shocks are easier to absorb? Then scan a curated list of solid balance sheet and fundamentals (23 results) that meet those criteria.
- If resilience is your priority and you want businesses with lower overall risk scores, turn to a hand picked 30 resilient stocks with low risk scores that may better fit a cautious approach.
- Looking for underfollowed opportunities with sound fundamentals and room for the story to develop? Then check out a focused 19 high quality undiscovered gems that could complement a position in Northrop Grumman.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com