
Ashland (ASH) Earnings And 2027 Outlook Put Fair Value Back In Focus
Ashland (ASH) drew fresh attention after its latest earnings release, which paired a fourth quarter net loss of US$16 million with full year net income of US$4 million and new 2027 guidance.
Ashland shares trade at US$76.72, with a 1 month share price return of 8.39% and a year to date share price gain of 28.19%. The 1 year total shareholder return of 57.51% points to strong recent momentum around the earnings, guidance and activist headlines.
Compare Ashland's recent earnings swing and activist interest with other materials players by scanning the 32 high quality undervalued stocks that combine stronger balance sheets with potential valuation gaps.
Ashland just delivered a sharp share price jump on fresh guidance and activist noise, yet the move still leaves a valuation gap on some metrics. How much of the possible upside already sits in the price, and how much is left?
Most Popular Narrative: 4% Undervalued
Ashland's most followed narrative on Simply Wall St puts fair value at $80.18, a touch above the recent $76.72 close, and frames that gap through the lens of sustainability, manufacturing efficiency and activist pressure. This analyst consensus Narrative blends earnings and revenue forecasts with an 8.03% discount rate to reach its view of where the stock could reasonably trade.
Strong commitment to R&D and platform based product development, highlighted by the transformed vegetable oil and multifunctional starch platforms, new life sciences excipients and growth in biofunctional actives, is already tied to early commercial orders and pipelines that point to future revenue contribution and earnings leverage as these technologies scale.
See why 2 investors see Ashland as 4% undervalued.
Result: Fair Value of $80.18 (UNDERVALUED)
Still, the Ashland story can change quickly if operational problems at plants such as Hopewell, or an unfavorable outcome from ongoing securities investigations, weigh more heavily on sentiment.
Find out about the key risks to this Ashland narrative.
Another View: Ashland On Earnings Multiples
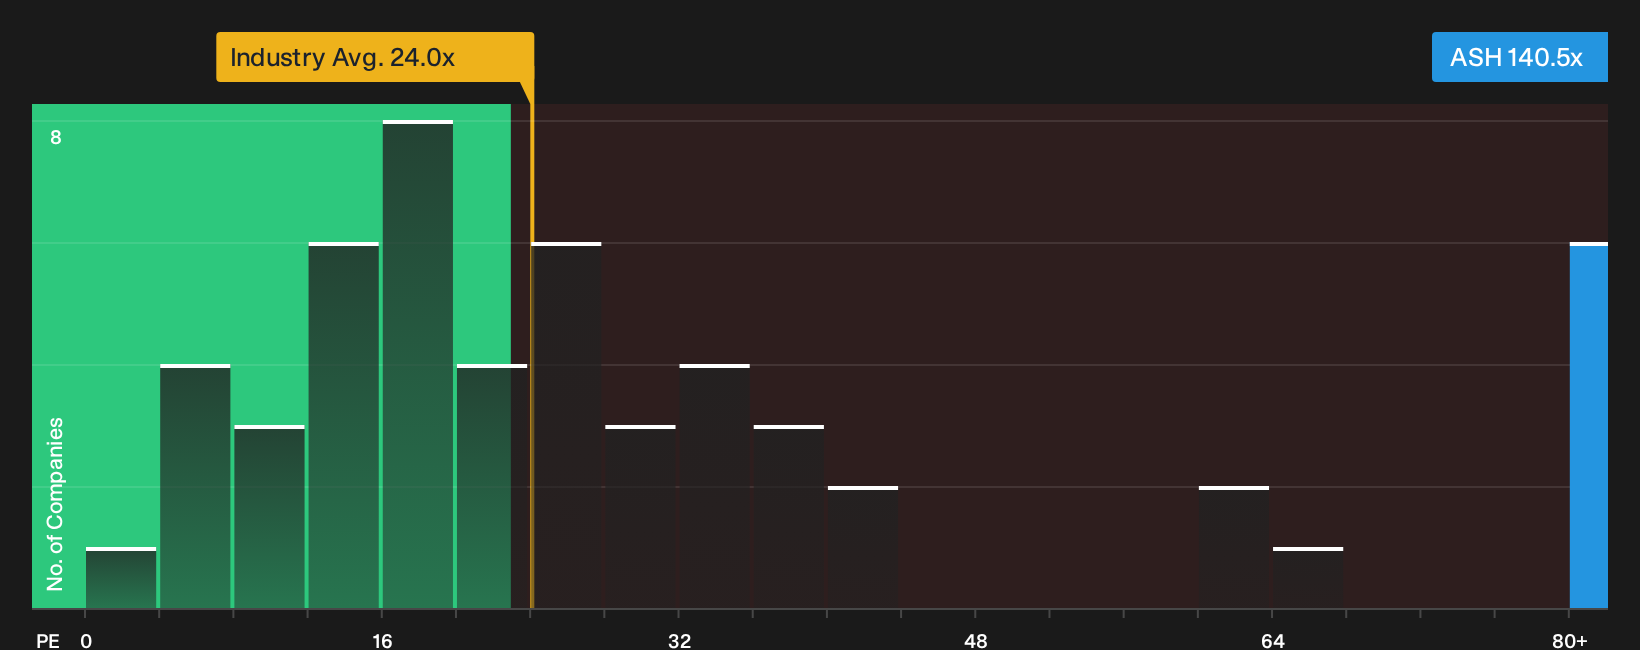
The cash flow based fair value suggests Ashland still has room, yet the P/E picture tells a different story. At roughly 140.5x earnings against a fair ratio of 27.7x, the stock trades on a very rich multiple, and both peers at 21.4x and the wider US Chemicals group at 24x sit far lower. That kind of gap can reward investors if earnings catch up, but it can also unwind quickly if expectations cool. Which side of that trade are you really considering?
See what the numbers say about this price in the full valuation breakdown, including how that P/E gap compares across Ashland's peers, by checking the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Ashland's valuation story so far. If you want to move quickly and form your own view, consider both sides with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ashland?
If Ashland has you thinking about what else might be out there, do not stop your research here. Broaden your watchlist and keep your options open.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when sentiment shifts.
- Hunt for mispriced opportunities using a 19 high quality undiscovered gems that may not yet be widely followed but still show strong fundamentals.
- Dial down volatility by reviewing a 30 resilient stocks with low risk scores that focuses on companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com