
Japanese AI Chip Stocks Worth Watching As Higher Rates Test Balance Sheets
Japan’s hotter October wholesale inflation and rising rate expectations have put both pressure and possibility on the same stage. Higher funding costs and squeezed import margins can punish weaker balance sheets, while resilient demand for AI hardware and semiconductors continues to pull capital toward the firms that actually supply the picks and shovels. This article walks through three Japanese semiconductor and AI-hardware stocks exposed to that mix of risk and potential reward.
The three stocks covered below are just a sample, and the full screen pulled out 21 more Japanese semiconductor and AI-hardware supply chain companies with equally compelling stories that are not discussed here. To identify your own highest-conviction semiconductor and data center hardware ideas, head straight into the Japanese semiconductor and AI-hardware supply chain stocks screener.
TOWA (TSE:6315)
TOWA is a Kyoto based specialist in semiconductor manufacturing equipment and high precision molds that feed directly into chip packaging for AI accelerators and data center hardware, complemented by smaller medical device and laser processing operations, and carries a market value of about ¥177.3b.
TOWA plugs straight into the screener theme because its tools and precision molds are used in making and packaging chips that end up in AI servers and data centers. This provides focused exposure to that capital spending cycle, although one unresolved funding pressure could heavily influence how much of that demand turns into durable earnings power.
To see how that funding risk compares with the packaging opportunity, go straight to the 1 key reward and 1 important major warning sign for the full picture contained in the details.

SAMCO (TSE:6387)
SAMCO manufactures plasma etching, thin film deposition and cleaning equipment used in semiconductor production, giving direct exposure to wafer processing that feeds AI chips and data centers. The Kyoto based group has a market value of about ¥55.8b.
As a pure play supplier into chip fabrication equipment, SAMCO links tightly to the screener’s semiconductor backbone, while AI related demand supports its order book. Investors seeking leveraged exposure to that volume story may view the key consideration as how readily the business can fund growth if credit conditions tighten further.
That funding question sits right at the heart of SAMCO’s story, so tap into the 3 key rewards and 1 important major warning sign to see how capital needs and upside potential really line up.
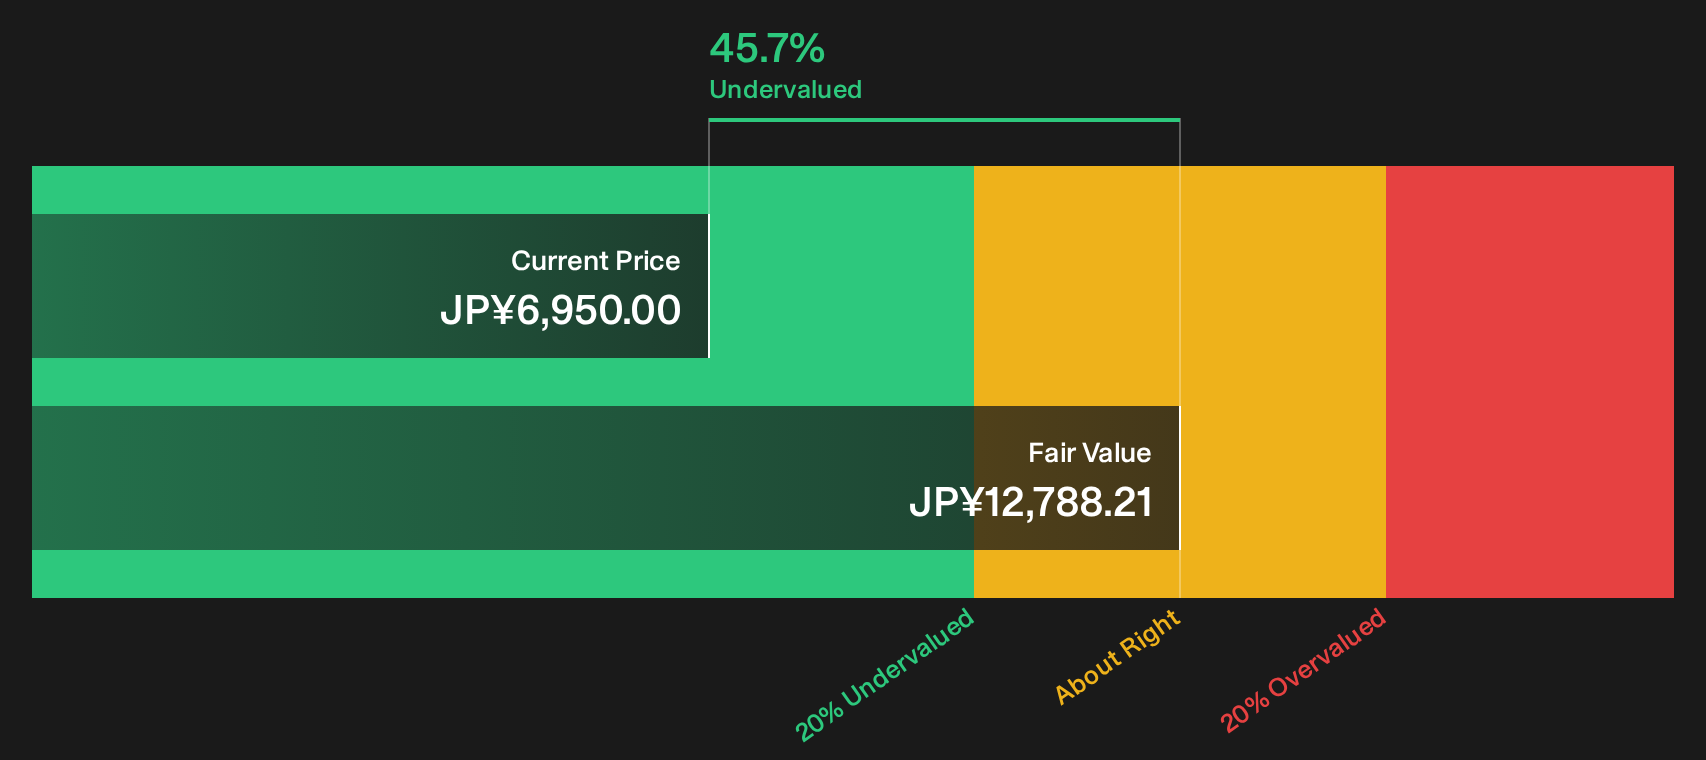
Shibaura Mechatronics (TSE:6590)
Shibaura Mechatronics is a Yokohama based supplier of semiconductor production gear and related systems that plug directly into the capex cycle for AI chips and advanced devices, alongside flat panel display tools and niche equipment, and the stock carries a market value of about ¥191.7b.
Shibaura Mechatronics provides focused exposure to the semiconductor equipment side of the screener, where AI chip fabs and advanced packaging lines decide how much they spend on cleaning, etching and bonding tools. Forecasts in the market currently indicate expectations for earnings and revenue growth, but outcomes remain closely tied to changes in the cost of borrowed capital.
That sensitivity to borrowing costs makes it worth checking the 1 key reward and 2 important warning signs (1 is major!) to see whether Shibaura Mechatronics’ AI exposure outweighs the funding squeeze risk.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time momentum headlines hit, early entry windows are already dropping. Scan these curated shortlists while they are still under the radar for now, act now.
- Target reliable cash generators that can weather funding shocks by reviewing a curated list of solid balance sheet and fundamentals (23 results) before attention and pricing move away from quality.
- Track where practical AI momentum is already flowing by scanning 42 profitable AI stocks that aren't just burning cash that are building real earnings instead of relying only on hopeful funding stories.
- Position ahead of the power infrastructure build out by studying 42 power grid technology and infrastructure stocks that could benefit if grid upgrades gain traction, rather than reacting after the surge.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com