
How Ocean Tracking Integration At Descartes Systems Group (TSX:DSG) Has Changed Its Investment Story
- Descartes Systems Group reported that its MacroPoint Advanced Ocean Visibility tool is now tied into SAP Business Network Freight Collaboration and SAP Business Network Global Track and Trace, giving SAP users near real-time, container-level ocean shipment data within existing transportation workflows.
- The integration uses standardized APIs and harmonized logistics data from the Descartes Global Logistics Network. This could deepen Descartes Systems Group’s role in multimodal visibility for customers that already rely on SAP for freight management.
- We will now look at how Descartes Systems Group’s investment narrative is affected by embedding its ocean visibility directly into SAP.
Scan logistics and supply chain leaders that are moving on similar themes to Descartes Systems Group by checking our hand-picked list of list of solid balance sheet and fundamentals (5 results)
Descartes Systems Group Investment Narrative Recap
To own Descartes Systems Group, you need to be comfortable with a logistics software specialist that leans heavily on recurring revenue, acquisitions and its role in trade compliance and visibility. The analyst consensus Narrative on Simply Wall St expects mid-teens earnings growth, so the key short term catalyst remains execution on organic service growth while integrating acquired platforms cleanly.
The biggest operational risk still sits around exposure to trade policy swings and volume sensitive transactional services, plus rising competition in AI and cloud based logistics tools. The new SAP ocean visibility tie up looks helpful for relevance and stickiness, but it does not fundamentally change those near term risks.
The freshest development that ties most closely to this SAP integration is the MacroPoint Advanced Ocean Visibility connection itself. Shippers using SAP Business Network now see container events, from gate moves to loading milestones, inside their existing freight workflows, which speaks directly to the firm’s push for multimodal visibility at scale.
For catalysts, this type of embedded visibility can support the story analysts are already modelling around digital transformation, higher recurring services and analytics or automation on top of standardized data. Execution risk remains around global trade volatility and competitive pressure, so the real test is sustained customer adoption of these deeper integrations.
Descartes Systems Group's current narrative presents the SAP integration as part of a broader analyst model that points to revenues of $1.0b and earnings of $275.4 million by 2029. This model is built on 11.3% yearly revenue growth and an earnings increase of about $111.6 million from $163.8 million today.
Uncover why Descartes Systems Group's fair value indicates a 6% potential downside to its current price, leaving little room for error.
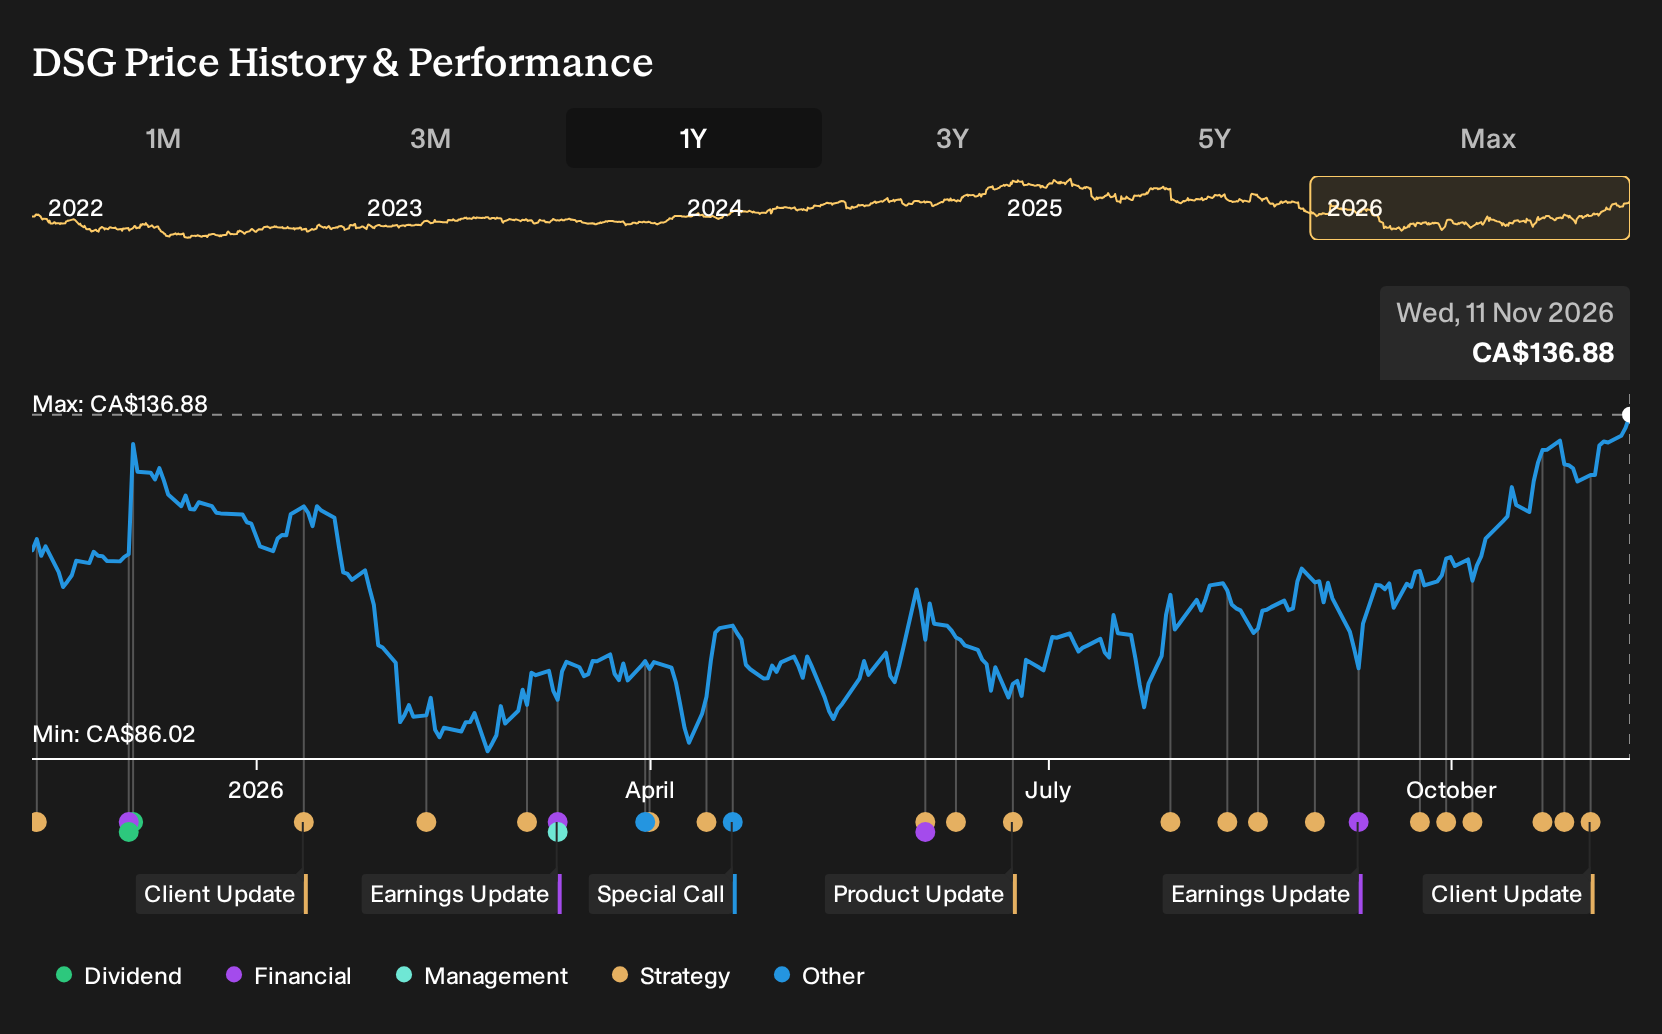
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between $128.28 and $166.91, so retail opinions on Descartes Systems Group already span a wide valuation band. When you set that beside the new SAP integration and ongoing trade policy and competition risks, it becomes clear why views diverge. Explore those alternative takes before deciding where you sit.
Explore 2 other Descartes Systems Group fair value estimates, including one that suggests as much as 6% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Descartes Systems Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Descartes Systems Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Descartes Systems Group's overall financial health at a glance.
Looking for more investment ideas beyond Descartes Systems Group?
If Descartes Systems Group has sparked fresh questions about where to put capital to work next, it can help to scan a broader field of opportunities that match your risk profile and income needs. The Simply Wall St Screener lets you filter for fundamentals that matter to you, then compare candidates side by side before committing any fresh money.
- For investors who want growth potential without ignoring balance sheet strength, take a look at 7 high quality undiscovered gems that pair quality fundamentals with under-the-radar profiles.
- If capital preservation sits high on your priority list, focus on resilience and financial robustness using the 9 resilient stocks with low risk scores that filters for sturdier business models.
- Income focused readers who care about reliable cash returns can zero in on high-yield payers by screening through 3 dividend fortresses that meet your comfort level for risk and payout quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com