
Is Hamilton Output Growth Altering The Investment Case For Alliance Resource Partners Stock?
- In Q3 2026, Alliance Resource Partners’ Hamilton complex reported a 1.3 million short ton increase in coal production, leading the Illinois Basin within a US coal market where overall volumes rose 5.6% sequentially and were 1.6% lower year on year.
- This step up in Hamilton output came as some peers faced supply constraints at Allegheny Met’s Longview mine and at Dominion Terminal Associates, where a damaged stacker reclaimer affected operations. This sharpened attention on Alliance Resource Partners’ operational reliability and capacity to meet utility and industrial demand.
- The focus now turns to how Alliance Resource Partners’ stronger Hamilton complex production might influence the existing investment narrative built around cash flow durability.
Scan for other coal-linked operators that may benefit from similar supply tightness by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) alongside Alliance Resource Partners’ latest production shift.
Alliance Resource Partners Investment Narrative Recap
To own Alliance Resource Partners, an investor needs to be comfortable with a coal business where pricing has already started to normalize and where contract mix matters as much as tonnage. The analyst consensus Narrative on Simply Wall St leans heavily on continued mine efficiency and coal cost control, plus steady oil and gas royalty contributions, to underpin free cash flow. The latest Hamilton complex production strength supports that efficiency story more than it changes it.
The most immediate swing factor is whether Alliance Resource Partners can keep converting committed coal volumes and higher royalty output into stable margins as more lower priced index linked contracts replace older deals. The biggest operational risk remains further mine specific changes or closures similar to Mettiki, especially if coal pricing softens while unit costs or logistics issues creep higher.
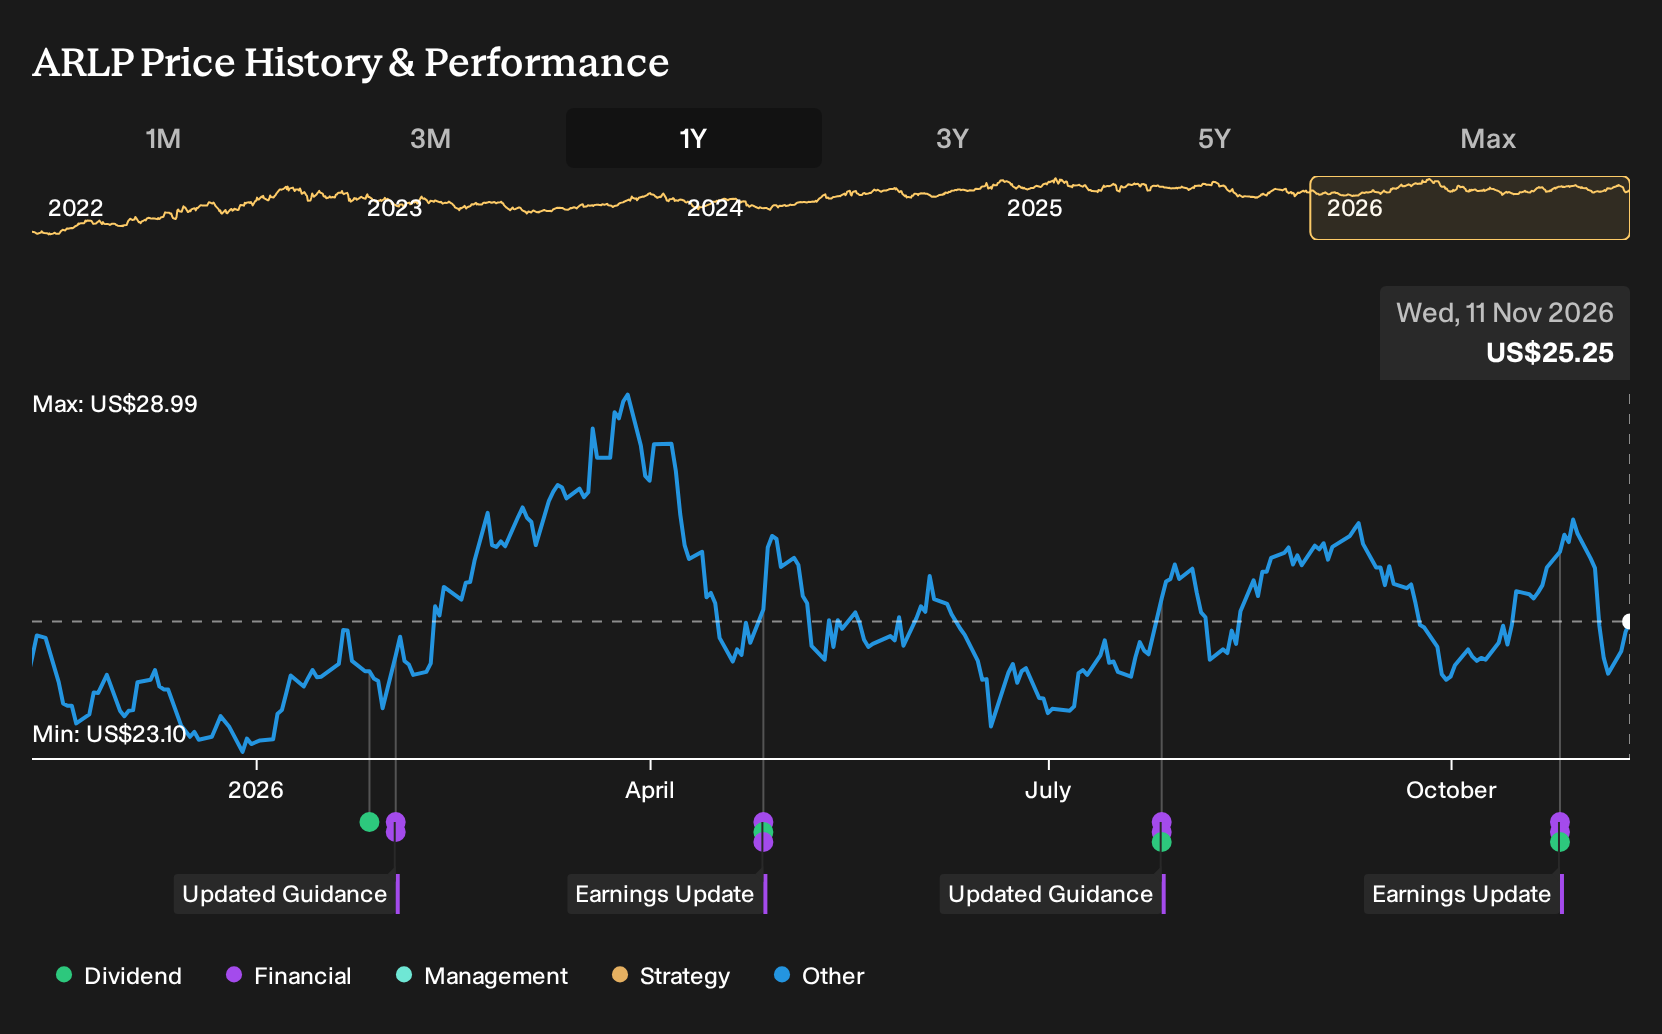
Recent commentary around upgraded 2026 oil, gas and NGL volume guidance, tied to more minerals interests and greater economic exposure to AllDale III and IV, sits closest to the current production story. Stronger Hamilton output reinforces the idea that coal cash generation can help fund this royalty build out, which the analyst consensus Narrative on Simply Wall St treats as a key earnings pillar.
For catalysts, the combination of near fully committed coal volumes for 2026 and 29.4 million tons already contracted for 2027 intersects with the royalty expansion theme. Reliable production at Hamilton matters because it backs those coal contracts, while the minerals portfolio gives another source of volume driven growth. Execution around both legs of the business will likely shape how much room Alliance Resource Partners has for future capital returns or reinvestment.
Alliance Resource Partners' current analyst narrative points to revenues of US$2.4b and earnings of US$401.5 million by 2029, based on forecast annual top line growth of 3.7% and an earnings increase of about US$138 million from the US$263.7 million reported today.
Discover how Alliance Resource Partners' fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value views on Alliance Resource Partners, stretching from about US$31 to roughly US$68 per unit, which already shows how far opinions can spread. When you compare that with risks like softer coal pricing or further mine changes, you get a wide decision set. Use those contrasting views to test your own thesis.
Explore another Alliance Resource Partners fair value estimate, including one that suggests up to 170% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alliance Resource Partners research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alliance Resource Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alliance Resource Partners' overall financial health at a glance.
Looking for more investment ideas beyond Alliance Resource Partners?
If you want to stress test your views on Alliance Resource Partners, it helps to weigh it against a broader watchlist of potential opportunities. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or mispriced quality so you can see where this partnership fits in your overall plan.
- For investors who care most about financial resilience and low leverage, start by scanning a list of solid balance sheet and fundamentals (24 results) that keeps an emphasis on sturdy fundamentals and cleaner balance sheets.
- If income is your priority and you want candidates that might support higher payouts, review a focused set of 6 dividend fortresses that clear a 5% yield hurdle while still maintaining underlying business strength.
- When you are hunting for mispriced quality with room for sentiment to catch up, run through a curated pool of 32 high quality undervalued stocks that combine solid cash generation with what may be attractive current pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com