
How Investors May Respond To Arrowhead Pharmaceuticals (ARWR) Positive Heart Conference Data
- Arrowhead Pharmaceuticals reported past clinical data at the 2026 American Heart Association meeting showing RNAi drugs plozasiran and ARO-DIMER-PA produced large reductions in triglycerides, LDL cholesterol and adjudicated acute pancreatitis events. The safety profiles are likely to be scrutinized closely by regulators and payers.
- The refinancing of Arrowhead Pharmaceuticals' US$400m term loan at a lower SOFR plus 5.5% rate and with no revenue sweeps reduces near-term financing constraints. This comes as cardiometabolic trial readouts begin to define the commercial potential of its RNAi platform.
- The next step is to examine how Arrowhead Pharmaceuticals' pancreatitis risk reduction data could reshape the existing investment narrative around its cardiometabolic portfolio.
Scan 36 healthcare AI stocks that could sit alongside Arrowhead Pharmaceuticals as cardiometabolic RNAi data and financing shifts reset expectations for what health-focused platforms might deliver next.
Arrowhead Pharmaceuticals Investment Narrative Recap
To own Arrowhead Pharmaceuticals, you need to believe its RNAi engine can turn strong lipid and pancreatitis data into durable commercial franchises while the business is still loss making. The analyst consensus narrative on Simply Wall St focuses on cardiometabolic and CNS assets eventually supporting revenue growth and a shift toward more typical biotech margins.
The AHA pancreatitis and lipid results sharpen the focus on plozasiran as the key near term catalyst, especially for broader severe hypertriglyceridemia use. The biggest risk remains high R&D and trial spending plus interest on the US$400m term loan, which could strain cash if product sales lag expectations.
The refinancing with Sixth Street looks most relevant right now because it directly affects how long Arrowhead Pharmaceuticals can fund this RNAi pipeline. Lowering the rate from 15% to SOFR plus 5.5% and extending maturity to November 2031 gives management more room to support plozasiran, zodasiran and ARO DIMER PA through expensive studies.
For investors, the near term story is a tight link between clinical catalysts and funding. Positive cardiometabolic data could help support that extended runway, while any delay in approvals or slower than expected uptake would leave the firm carrying sizeable debt and ongoing losses for longer with fewer obvious self help levers.
Arrowhead Pharmaceuticals' current analyst narrative points to revenue of US$1.0b and earnings of US$194.9m by 2029, built on an assumed 14.9% yearly increase in revenue and an earnings swing of roughly US$514.9m from a reported loss of US$320.0m today to the forecast profit level.
Uncover why Arrowhead Pharmaceuticals' fair value indicates a 118% potential upside to its current price, which could narrow quickly as sentiment shifts.
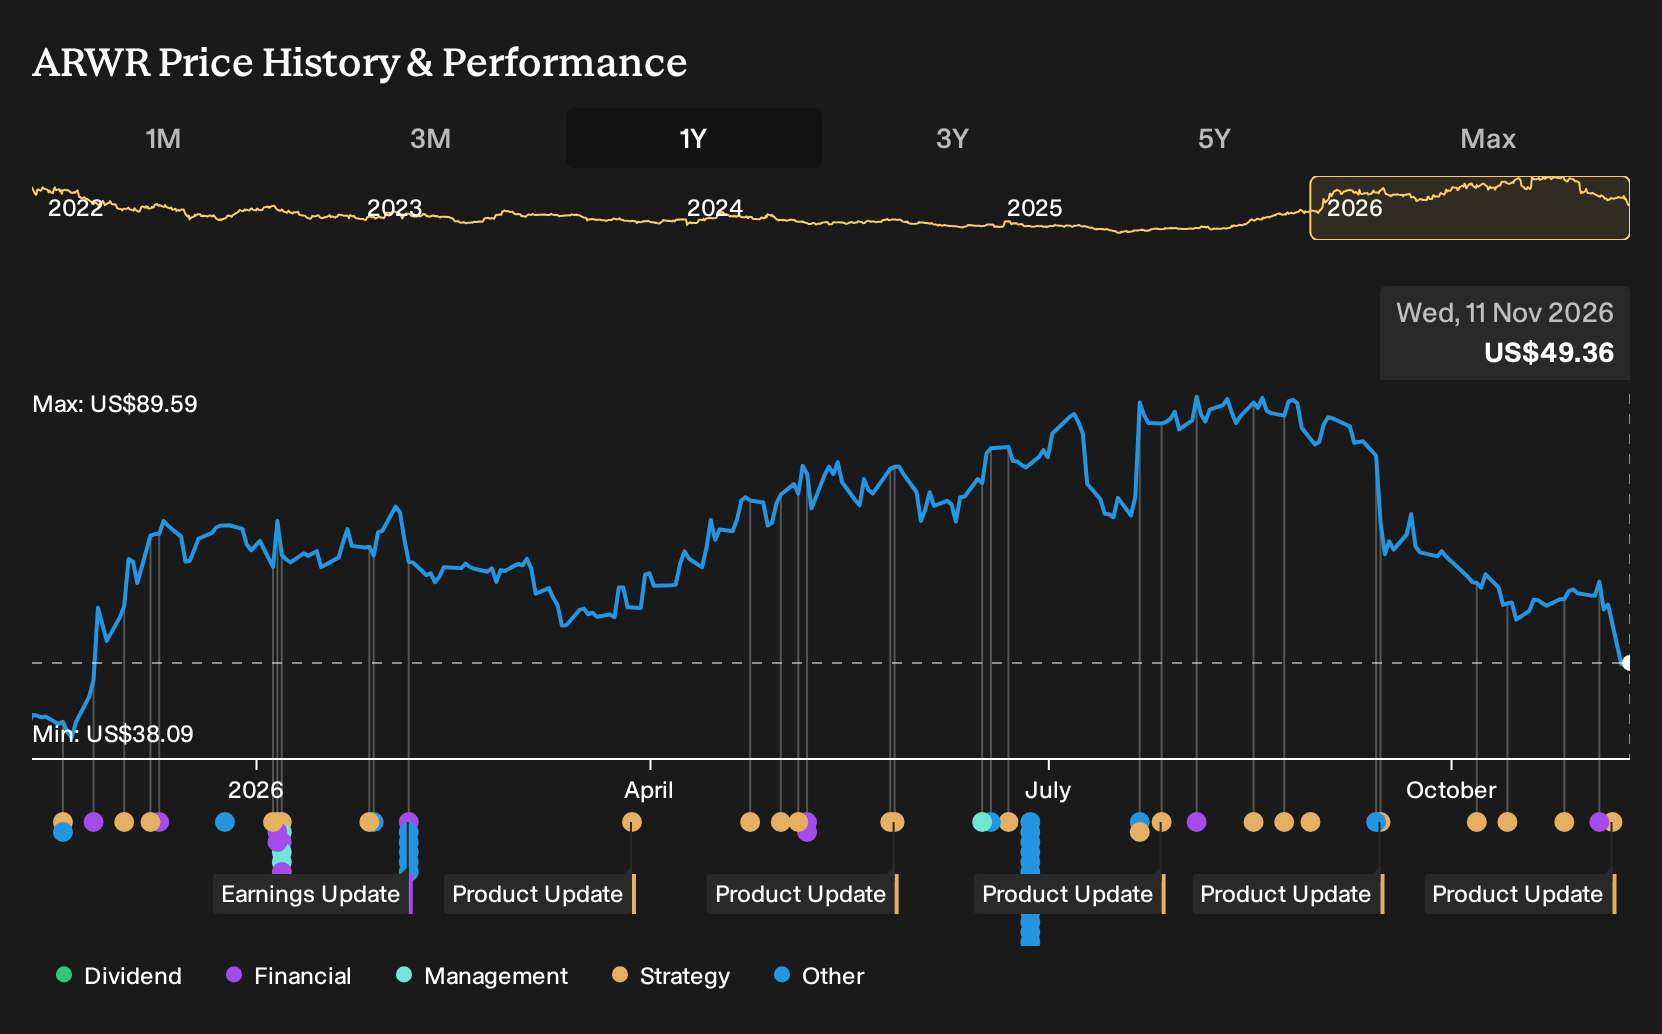
Exploring Other Perspectives
One sharp contrast is the bearish focus on slower plozasiran uptake into severe hypertriglyceridemia. Before this AHA and refinancing news, the lowest analysts were working off revenue of about US$915.9m and earnings of roughly US$157.6m by 2029, which is a clear step down from consensus. That gap shows how widely Arrowhead Pharmaceuticals opinions can differ, so it can help you to explore both sets of assumptions and decide which story feels closer to your own read of the data.
Explore 3 other Arrowhead Pharmaceuticals fair value estimates, including one that suggests it could be worth just $107.71!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Arrowhead Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Arrowhead Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arrowhead Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arrowhead Pharmaceuticals?
Once you have a handle on Arrowhead Pharmaceuticals, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that actually matches your own goals rather than someone else's checklist.
- If capital preservation is front of mind, consider starting with a basket of resilient companies by checking out 30 resilient stocks with low risk scores that have historically paired sturdier balance sheets with lower risk scores.
- If you care more about dependable cash returns, income focused investors often begin with 6 dividend fortresses that combine 5%+ yields with an emphasis on stability.
- If you want to hunt for potential future leaders before the crowd, you could scan 19 high quality undiscovered gems that already show strong fundamentals but still fly under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com