
Hinge Health (HNGE) Stock Looks Rich After Its 188% One Year Run
Hinge Health has delivered a powerful run, with the stock up 187.6% over the past year, which puts fresh focus on whether that share price still lines up with the earnings behind it. With recent headlines around record results and raised full-year revenue expectations, the key issue for you now is how much of that good news is already embedded in the current valuation.
- The 187.6% one year gain has rapidly reset expectations. Any view on Hinge Health now starts with what investors are willing to pay for its earnings profile.
- Recent profit progress and a larger client base can support arguments for stronger and more durable earnings. This feeds directly into how rich or restrained an earnings multiple might look.
- There is a second opinion on Hinge Health worth weighing. See what analysts think Hinge Health's shares could be worth.
The issue now is whether Hinge Health's current price is adequately supported by its earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings question beyond Hinge Health, compare it with a wider group of 32 high quality undervalued stocks.
Is Hinge Health Getting Expensive on Earnings?
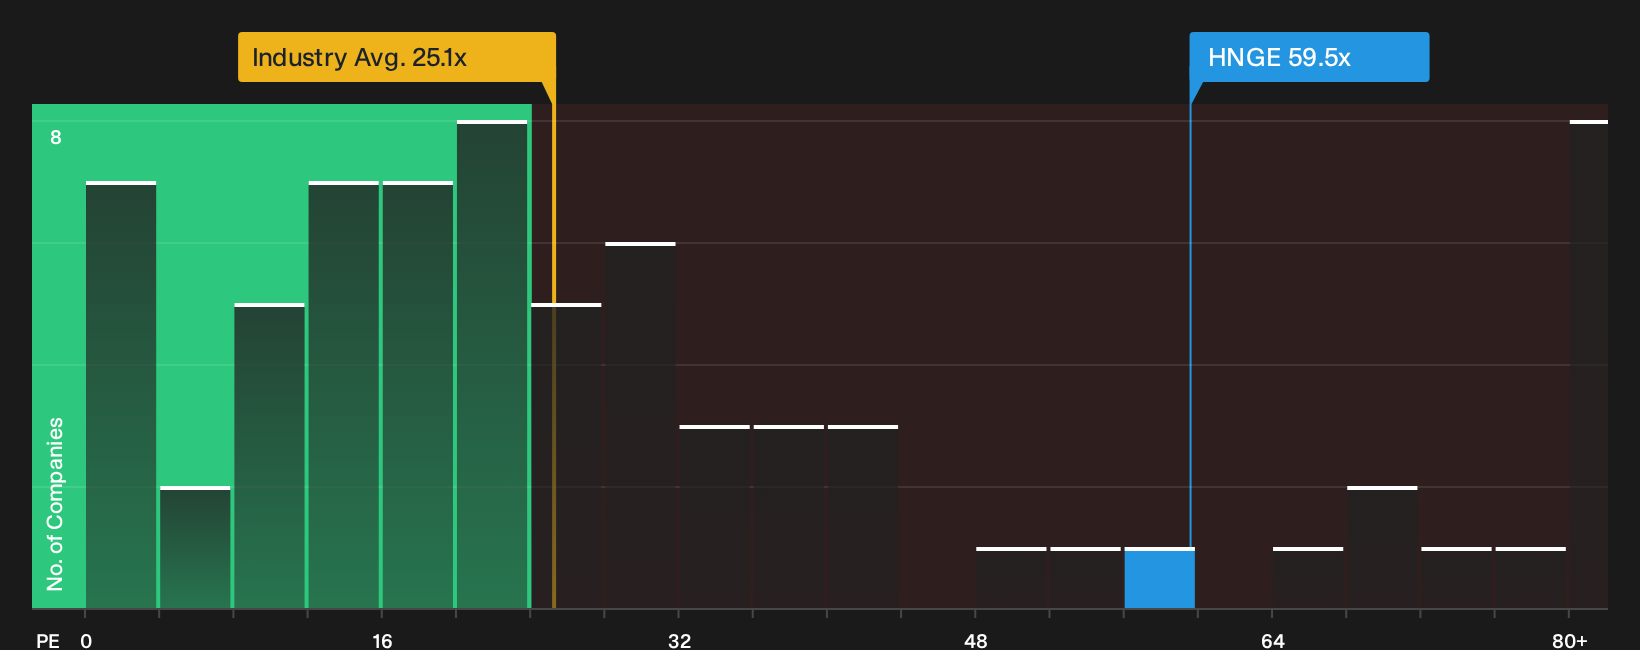
The P/E ratio is a useful anchor for Hinge Health because it already reports profits that can be compared directly with its share price. On this metric, the stock trades on about 59.5x earnings, which is richer than both the Healthcare sector average of roughly 25.1x and the peer group on about 50.3x. That places Hinge Health on a visibly higher multiple than many profit-making healthcare peers.
Because the P/E that would typically be expected given Hinge Health's profile is lower than the current level, the stock screens as overvalued on this framework. Record Q3 2026 results and higher full year revenue guidance help explain why investors are willing to pay up for each dollar of earnings, yet the price still sits above what the Fair Ratio model implies for the business. For anyone assessing HNGE, the key question is whether that premium P/E is justified by future execution and risk, or whether it leaves less room for error than the sector and peer averages suggest. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hinge Health valuation puzzle leaves off by spelling out what kind of growth, margin path and earnings profile would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each narrative ties its number to a clear view on how Hinge Health's revenue potential, profitability and risk profile could evolve, which you can revisit as fresh information comes through on the Community page.
Bulls and bears are reading the same Hinge Health numbers and reaching very different conclusions about how much is already priced in.
Bull case: 16% undervalued
According to Ontological, an investor in the Simply Wall St Community, the upside case leans heavily on operating efficiency and scale.
"Most striking is the free cash flow margin, which surged to 47% in Q2 2026, far exceeding typical SaaS benchmarks of 15 to 20%…"
Discover why this Narrative puts Hinge Health at 16% undervalued.
Bear case: 20% overvalued
The bearish analyst Narrative on Simply Wall St frames the risk around what happens if strong execution meets already stretched expectations.
"Despite analysts expecting the underlying business to improve, they seem to believe the market's expectations are too high…"
Explore why this Narrative puts Hinge Health at 20% overvalued.
One more crucial piece for Hinge Health that the numbers do not show
The valuation story for Hinge Health is only half complete without understanding who is steering the business, what they prioritise and how their incentives line up with shareholders. See who runs Hinge Health and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com