
Is Somnigroup International (SGI) Cheap On Earnings, Dividends And Acquisition Plans?
Somnigroup International (SGI) just packed earnings, a dividend declaration and fresh comments on acquisition plans into a single business update, giving investors several moving parts to assess at once.
Somnigroup International’s share price has slipped 10.49% over the past week and is down 29.58% year to date. However, the 3-year total shareholder return of 58.37% and 5-year total shareholder return of 48.34% show longer term gains, even as recent momentum has faded following record results, guidance reset, acquisitions and the latest dividend announcement.
Capitalize on Somnigroup International’s earnings reset and acquisition push by scanning a curated 19 high quality undiscovered gems featuring companies with similarly active strategies and strong fundamentals.Bulls point to Somnigroup International’s multi year gains, vertical integration and synergy targets. Bears see ERP hiccups, softer bedding demand and execution risk. Which side does the current valuation lean toward as guidance gets reset?
Most Popular Narrative: 33% Undervalued
Against Somnigroup International’s last close at $62.49, the analyst consensus Narrative on Simply Wall St works off a fair value of $93.44 and treats that gap as meaningful. It blends analyst revenue and earnings forecasts with a 9.4% discount rate to frame where the stock might sit on a long term view.
Integration of recent acquisition and digital strategy are driving cost efficiencies, margin expansion, and improved cash flow. International growth, proprietary technology, and favorable demographics are broadening the revenue base and supporting premium product demand.
See why 6 investors see Somnigroup International as 33% undervalued.
The same analyst consensus Narrative assumes Somnigroup International can grow revenue and profits at a pace that justifies a fair value roughly one third above the current share price, once future cash flows are discounted at 9.4%. That relies on earnings expansion from $533.3 million today toward $1.1 billion by 2029, along with profit margins that analysts model at 9.4% in three years compared with 7.0% now.
This framework also embeds a future P/E multiple of 22.6x on those 2029 earnings, which is higher than the current 13.3x multiple cited for the US Consumer Durables industry in the Narrative. For you as an investor, the key question is whether Somnigroup International’s control of more of its supply chain, the Mattress Firm and Leggett & Platt integrations, and digital initiatives justify that richer valuation over time.
Result: Fair Value of $93.44 (UNDERVALUED)
Still, softer bedding demand and the risk that Somnigroup International falls short on Mattress Firm and Leggett & Platt synergies could quickly challenge that 33% undervalued story.
Find out about the key risks to this Somnigroup International narrative.
Another View: Somnigroup International Through The P/E Lens
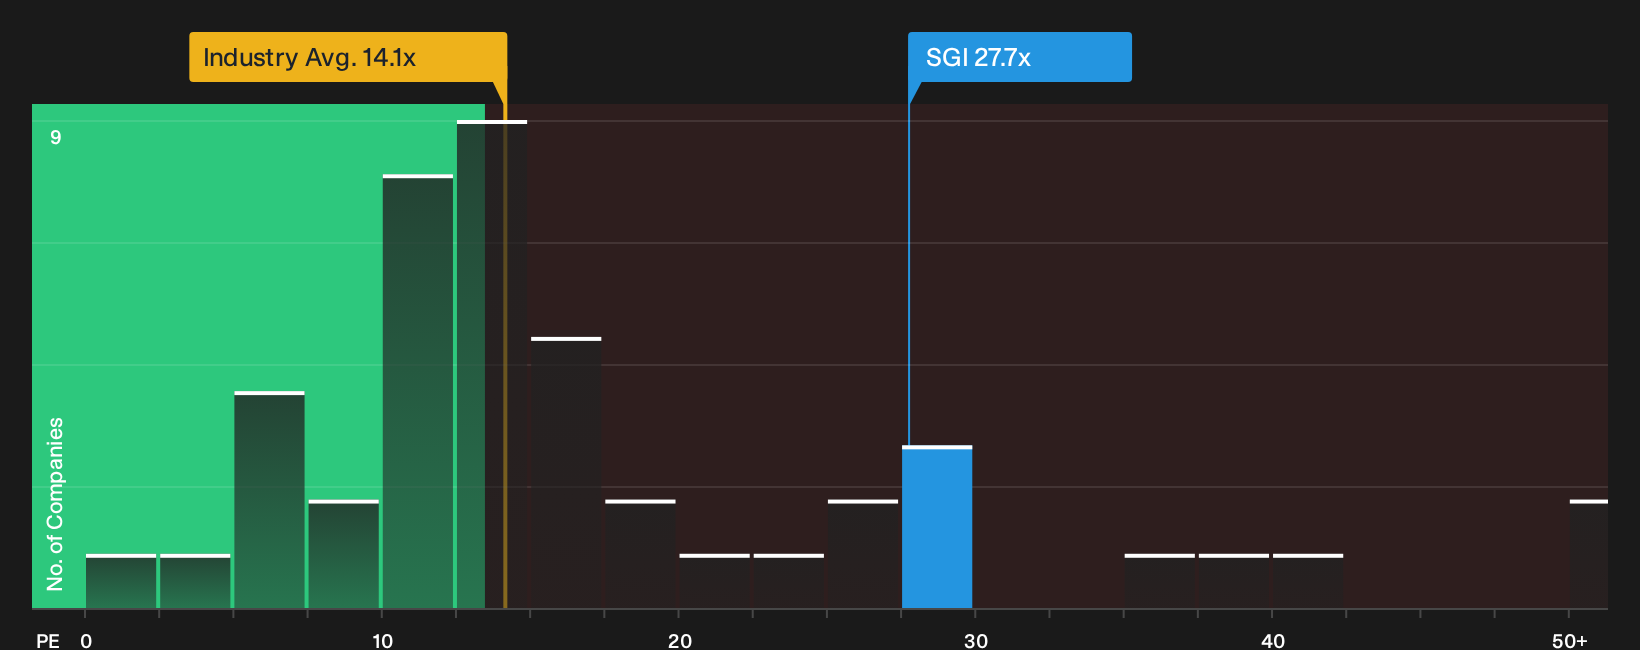
The analyst Narrative leans on future cash flows and a fair value of $93.44. A simple earnings multiple tells a different story. Somnigroup International trades on a P/E of 27.7x, while the Consumer Durables industry sits at 14.1x and direct peers average 15.7x.
The fair ratio sits at 27.4x, only a touch below the current level. That means most of the premium is already in the price, with less room for error if earnings or synergies fall short. As an investor, are you comfortable paying almost double the industry multiple for this bedding group?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Somnigroup International’s valuation, growth plans and deal execution can feel messy, so move fast, review the numbers yourself and decide where you stand. To weigh both the upside and the downside in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more Somnigroup International style investment ideas?
Do not stop with Somnigroup International. Use the Simply Wall St screener to pinpoint fresh opportunities with clear financial stories and different risk profiles.
- Target resilient potential by reviewing companies that score well on financial strength and liquidity through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by scanning the 32 high quality undervalued stocks focused on strong businesses that trade below their assessed worth.
- Prioritise steadier capital preservation and smoother ride potential by checking out the 30 resilient stocks with low risk scores built around companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com