
Altria Group (MO) Earnings Put Its Dividend Story And Valuation Back In Focus
Altria Group (MO) just posted third quarter 2026 results that showed higher sales and net income compared with a year earlier, prompting fresh attention on the tobacco giant’s dividend track record.
Altria Group’s latest earnings arrive after a strong run in the share price, with a 30-day share price return of 8% and a 90-day move of 18.9%. The 1-year total shareholder return of 42.3% and 5-year total shareholder return of 155.8% signal momentum that investors are weighing against ongoing smoke free product risks and regulatory scrutiny.
Spot 6 dividend fortresses that, like Altria Group, pair substantial income potential with long records of consistent shareholder payouts.After that rally, and with Altria Group now trading above the average analyst target while still carrying a large implied discount to estimated intrinsic value, where does a reasonable fair value anchor actually land for this stock?
Most Popular Narrative: 6.7% Overvalued
Altria Group’s last close of $77.39 sits above the analyst consensus Narrative fair value of $72.55, which uses a discount rate of 8.0% and ties that to detailed revenue, earnings and risk assumptions in the analyst consensus Narrative on Simply Wall St.
The main factor that has to go right is Altria Group successfully scaling its on! and on! PLUS nicotine pouch platform, as well as balancing Marlboro and discount brands while managing regulatory and legal pressures.
See why 270 investors see Altria Group as 7% overvalued.
Result: Fair Value of $72.55 (OVERVALUED)
Still, the Altria Group story can change quickly if trade down into discount cigarettes erodes the Marlboro mix, or if legal and regulatory probes escalate.
Find out about the key risks to this Altria Group narrative.
Another View: What Altria Group’s P/E Is Saying
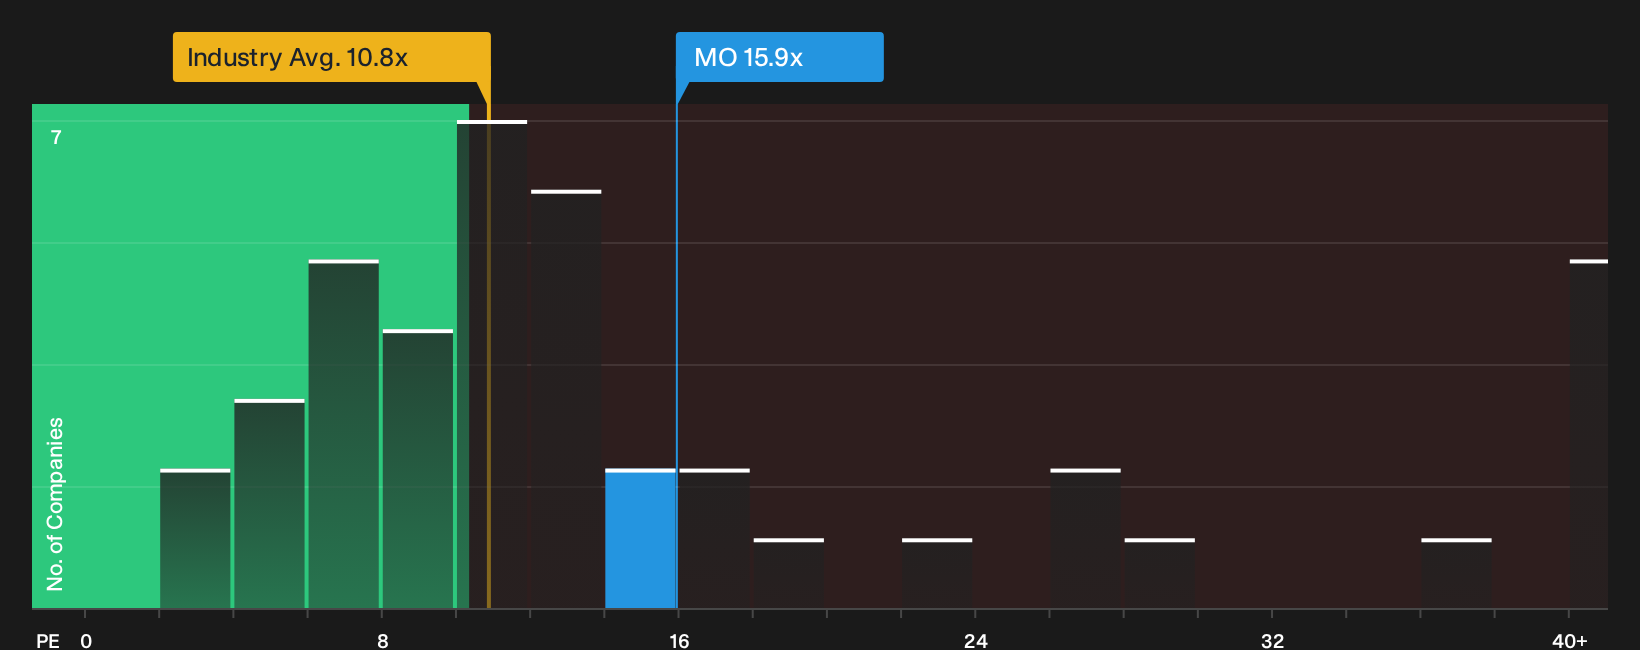
Analysts using narrative based fair value see Altria Group as 6.7% overvalued around $77.39 compared with a $72.55 anchor. The P/E picture looks very different. MO trades on 15.9x earnings against a fair ratio of 23.3x and a peer average of 27.5x, while the wider global tobacco group sits nearer 10.8x.
That combination points to a stock that screens cheap against close peers and below its own fair ratio, yet screens expensive against the broader industry. It raises a practical question for you as an investor: Which crowd matters more for Altria Group, direct competitors or the wider tobacco sector, and what does that imply for how much valuation risk you are willing to accept?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Altria Group’s value and risk profile invite more than a quick glance. Take a closer look at both sides of the story with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Altria Group?
If you stop with Altria Group, you see only one angle. Broaden your watchlist with a few targeted screens that can surface very different opportunities.
- Target resilient income payers by scanning a curated set of 6 dividend fortresses that aim to keep distributions flowing even when conditions get tougher.
- Hunt for potential value gaps by reviewing 32 high quality undervalued stocks where fundamentals and pricing send very different messages.
- Prioritise capital protection by focusing on 30 resilient stocks with low risk scores that pair steadier risk profiles with cleaner balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com