
The 1 Number CoreWeave Bulls Are Ignoring After Today’s Rally
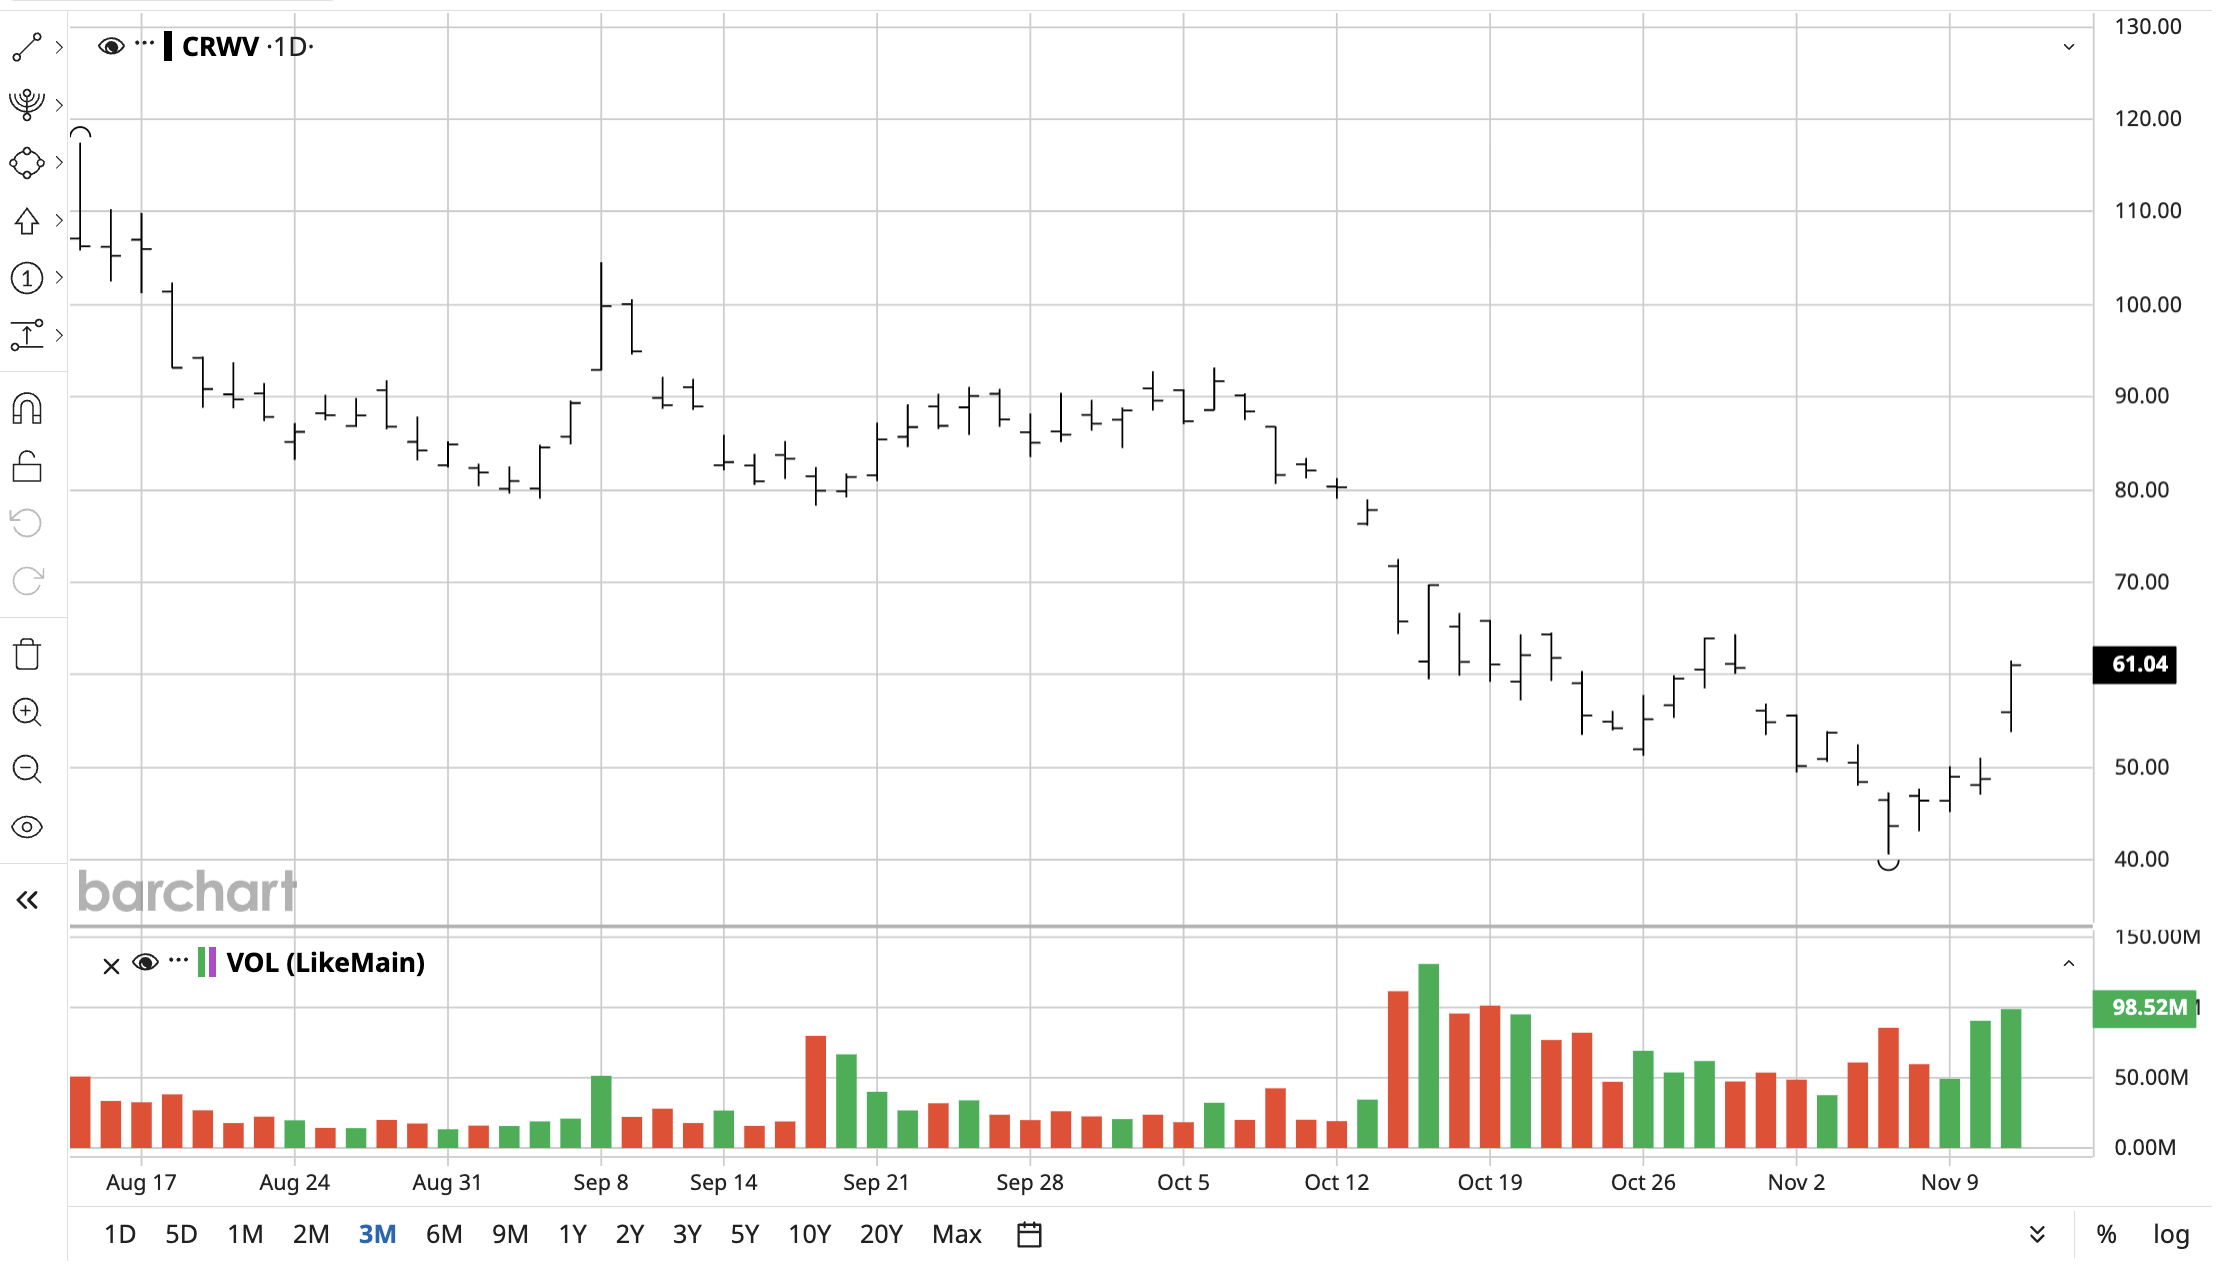
CoreWeave (CRWV) stock lost 75% of its value before it started bouncing back on Nov. 11 after record earnings, climbing roughly 25% in just one session. Investor worries about how the company would pay for its leveraged artificial intelligence (AI) buildout are no longer taking center stage, as the AI cloud provider recently posted quarterly results that beat estimates and raised its guidance for the year.
Third-quarter revenue came in at $3.66 billion, ahead of analyst estimates of $3.55 billion, while management raised its full-year 2026 revenue guidance to a range of $13 billion to $13.3 billion. That is well ahead of estimates of $12.86 billion.
That said, investors should still worry about some of the numbers coming out. Let's take a closer look.
Guidance Isn't as Solid as You Think
At first glance, the raised outlook looks like a clear vote of confidence for CoreWeave. However, the shape of the new range is more muted when you look at the top end. Management lifted the bottom of its full-year revenue guidance from $12.4 billion to $13 billion, while the top moved only from $13.2 billion to $13.3 billion. Q3 alone beat the consensus estimate by $110 million, so the top end adds little for the final quarter.
Then, there are factors outside of CoreWeave's control in Q4. Revenue for the first three quarters of fiscal 2026 totaled roughly $8.3 billion, so the new range implies Q4 revenue of $4.7 billion to $5 billion. Reaching that will require new data-center capacity to come online on schedule.
Unfortunately, management left its year-end target of more than 1.85 gigawatts of active power unchanged, even as it raised its full-year capital expenditures guidance to a range of $37 billion to $39 billion. Management also expects losses through 2027, with only adjusted net income turning positive in 2028.
CoreWeave’s Interest Bill Is Eating Its Profits
CoreWeave sees interest expense of $1.05 billion to $1.15 billion in Q4, which is over 80% of its $1.275 billion to $1.375 billion in guided adjusted operating income for the entire year. Again, that's just one quarter of interest payments, so we are looking at interest expenses dwarfing the business' profits.
Interest expense was $640 million in Q2, and net interest expense rose to $846 million in Q3. If CoreWeave lands at the midpoint of its Q4 guidance, its quarterly interest bill will have grown by roughly 70% in just two quarters.
Operating profit is growing quickly, too, but Q3 GAAP operating income was $207 million. So, after interest, the company still reported a net loss of $709 million.
CoreWeave owed almost $47 billion at the end of Q3. Very likely, you are going to see that debt continue to rise significantly, as this company does not have the cash to fund its buildout expenses. CoreWeave ended the quarter with about $4.12 billion in cash against full-year capex guidance of $37 billion to $39 billion, while the company plans to raise new debt tied to a set of contracts in the coming weeks. Data also shows CoreWeave's total debt more than tripled in the year through June, going from $11.05 billion to $35.07 billion.
How to Play CoreWeave Stock After the Rally
Before you chase the Nov. 11 rally, you should keep in mind how often CRWV stock has rallied during its long slide downward. Rallies of double digits in a day are a dime a dozen in this stock's history, and they haven't ended well in the long run. Barchart lists a 60-month beta of 7.71 for CoreWeave, so CRWV stock swings far harder than the market. The debt is simply too high and acts as a millstone that keeps enterprise value down, and that's even before you factor in the high interest expenses. Q2 alone saw $11.53 billion in net debt issuance.
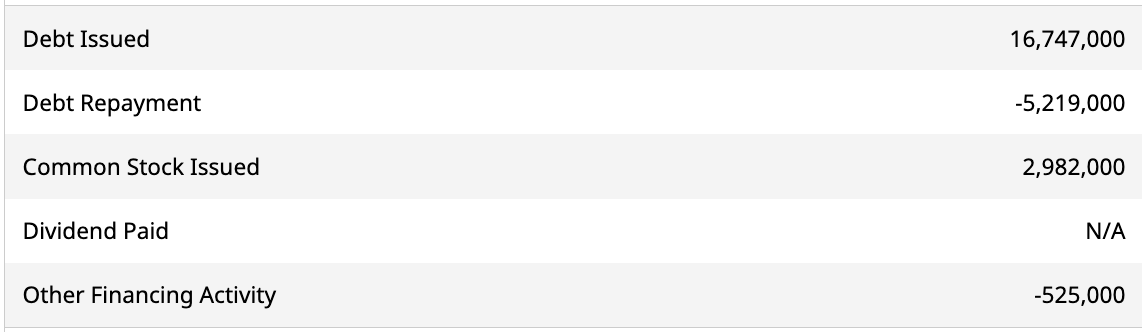
All things considered, I expect CRWV stock to keep declining. Barchart's Technical Opinion agrees, with a strong "Sell” even after Wednesday's rally. The new debt will add to CoreWeave's already eye-watering debt, and the company also has an at-the-market (ATM) program to sell up to 35 million new shares. In short, you'd be investing in a business with dilution, debt, and losses.
On the date of publication, Omor Ibne Ehsan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.