
GitLab (GTLB) Could Be 16% Below Fair Value On RapidFort Partnership
GitLab (GTLB) is back in focus after RapidFort announced a partnership that supplies hardened, compliance-ready container images for regulated self-managed deployments, aiming to reduce vulnerabilities directly inside existing GitLab workflows.
The RapidFort tie up lands after a mixed run for GitLab’s stock, with a 30 day share price return of down 15.5% and a 7 day move of down 9.7%. At the same time, a 90 day share price return of 9.1% and year to date gain of 30.8% suggest momentum has cooled recently but remains positive over a longer stretch. Meanwhile, the 1 year total shareholder return of 1.9% and 5 year total shareholder return of down 60.3% show how long term holders have had a far rougher ride as the market reassesses both growth potential and execution risk around new security and AI features.
Scan beyond GitLab and line up other security focused software plays using our curated list of 19 high quality undiscovered gems as a starting universe.
GitLab now pairs fresh security partnerships with a wobbling share price. After this pullback, does the current valuation still offer enough upside potential to justify the execution and competition risks buyers are taking on?
Most Popular Narrative: 16% Undervalued
GitLab closed at $47.31, while the analyst consensus Narrative on Simply Wall St places fair value at $56.13 using an 8.4% discount rate. The current quote implies a meaningful gap that hinges on how AI, SaaS and Flex adoption actually play out.
GitLab's expansion of AI-driven capabilities across its DevSecOps platform, now including strong early traction for Duo Agent Platform and a paid consumption run rate above US$40 million with a target of more than US$100 million, is cited as supporting the idea that higher value AI features can contribute to revenue growth and operating leverage as usage scales.
See why 83 investors see GitLab as 16% undervalued.
Result: Fair Value of $56.13 (UNDERVALUED)
Still, the GitLab story can shift quickly if Flex-driven revenue timing drags on reported growth or the Act 2 restructuring disrupts large deal execution.
Find out about the key risks to this GitLab narrative.
Another View: GitLab Looks Expensive On Sales
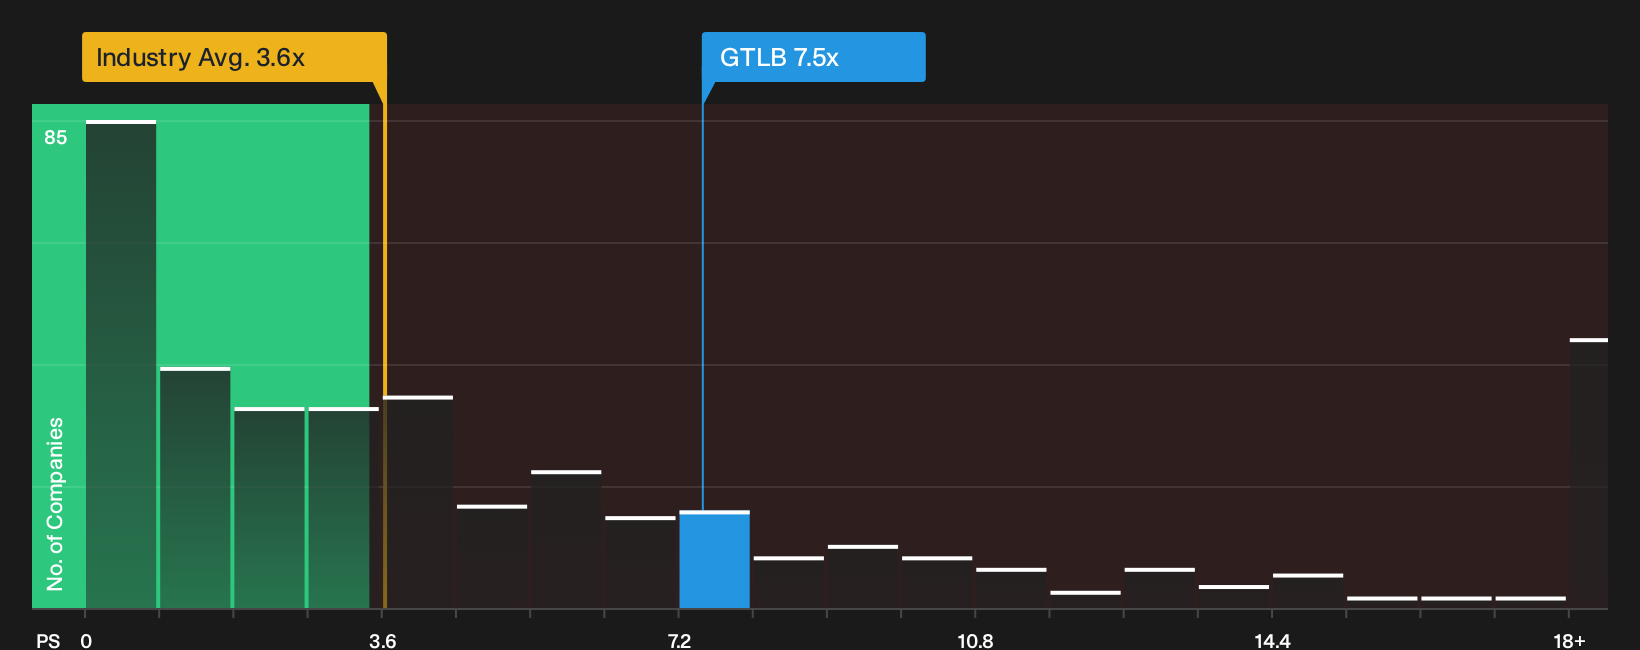
The 16% gap to fair value from our DCF-style narrative looks different when you consider what the market currently pays for GitLab’s revenue. On a P/S of 7.5x, the stock trades at more than double the US Software industry on 3.6x and above its own fair ratio of 6.7x. This could reflect a perceived quality premium or a thinner margin of safety if execution slips.
For a closer look at how that sales multiple compares across peers and how much room there might be for it to compress or stretch, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are uncertain whether this mixed picture around GitLab represents an opportunity or a risk for you personally, consider acting promptly and evaluating both sides by reviewing the 1 key reward and 1 important warning sign.
Ready for more investment ideas beyond GitLab?
Do not stop with a single ticker when the market is full of mispriced stories that could suit your goals better than GitLab at today’s levels.
- Target potential upside in compressed valuations by scanning a focused pool of companies that screen as 32 high quality undervalued stocks.
- Prioritize sleep-at-night resilience and use a curated universe of 30 resilient stocks with low risk scores to guide you toward businesses with steadier risk profiles.
- Hunt for underfollowed opportunities and rely on a filtered set of 19 high quality undiscovered gems before the wider market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com