
What Medistim Doubters Got Wrong
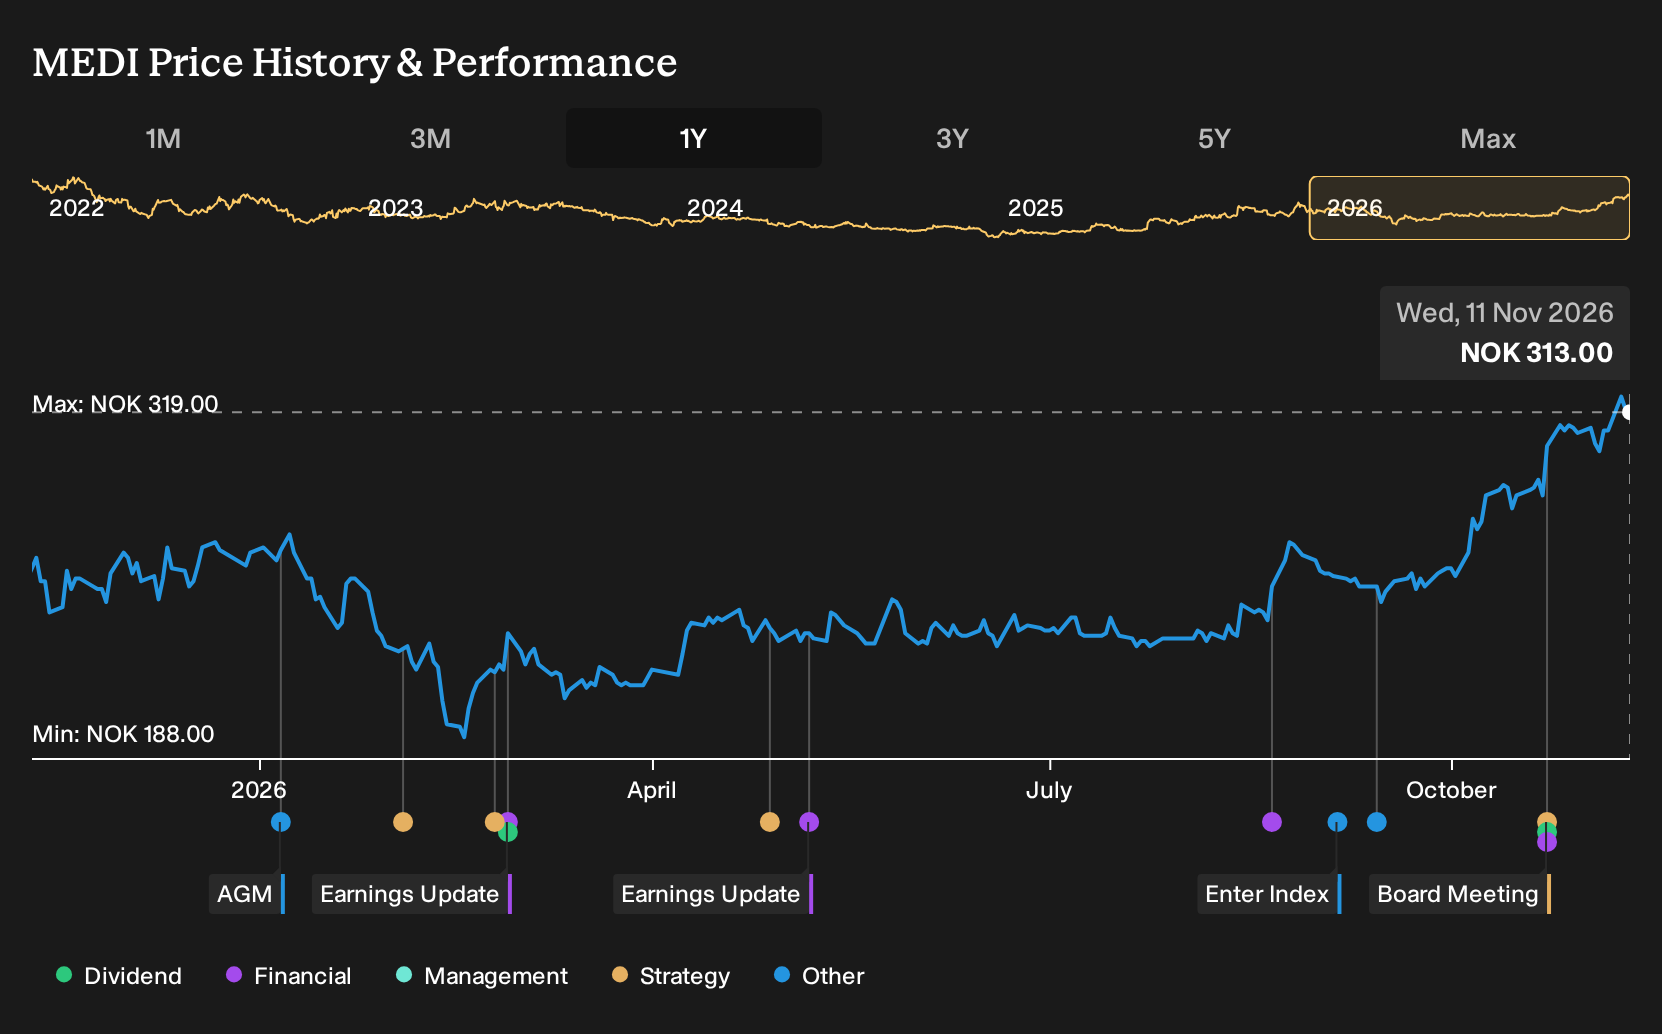
If you only skimmed Medistim’s quarterly headlines, the story might look straightforward. Revenue and profit were higher in Q3 2026 than a year earlier, and net margin moved from 20.8% to 22.8%. Holding Medistim over the past year would have returned 31.9%, including dividends. If you had been weighing those 2025 bullish and bearish reports before buying, what exactly in that mixed record seemed solid enough to justify taking the risk?
The easy part of this move is behind Medistim. Zero in on 196 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Medistim Investors Were Weighing
The shares cost NOK257 at the start of the period, and anyone looking at Medistim then had to decide which of two stories felt more convincing.
On the optimistic side, one narrative saw share repurchases and global market expansion supporting a Fair Value of NOK290. That price reflected what strong future performance could justify. That view leaned on assumed revenue growth of 8.9% with profit margins at 22.3% and a future P/E of 35.2x over three years.
The cautious camp worked off a Fair Value of NOK200, a price level that reflected pressure from shrinking patient pools and rising costs. That scenario still used 8.9% revenue growth but only 20.5% profit margins and a future P/E of 27.3x, plus the risk of alternative therapies steadily eroding cardiac surgery volumes.
What The Results Changed For Medistim
The clearest update came from Medistim’s Q3 2026 report. Revenue reached NOK209.987m and net income was NOK47.802m, with net margin at 22.8% versus 20.8% a year earlier. That profitability level sat close to the earlier bullish assumption of 22.3%, so the quarter leaned toward the optimistic case.
The key lesson is simple. When a thesis hangs on margin expansion, do not stop at sales growth. Track net margin and compare it with the original forecast range to see which story is getting more real world support.
What Medistim’s Run Leaves You Paying For
Medistim now trades at NOK313 after a 31.9% gain over the past year. The analyst consensus Narrative on Simply Wall St places its Fair Value above that level, framed around recurring usage of installed systems rather than one off hardware sales.
The same Narrative argues that today’s price still does not fully credit Medistim converting recent investments into sustained procedure volumes and durable margins.
"Expansion of Medistim's direct sales operations in Asia, including the recently opened Japanese subsidiary with a 10 person team and the move to go direct in China, is shifting revenue away from distributors toward higher margin regions, which can support higher earnings and net margins over time."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 27% below our estimate - builds a broader adult and oral health line as direct channels scale.
- Company 2 - 31% below our estimate - expands fee earning real asset funds aimed at tax efficient retail inflows.
- Company 3 - 42% below our estimate - applies in house data and AI tools to refine underwriting and claims handling.
Those are three of them. See every one of the 194 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com