
Cohu (COHU) Stock Trades Below Fair Value On Cash Flow Estimates
Cohu has nearly doubled over the past year, and with the stock last closing at US$45.99 the immediate question for you is whether that price still lines up with the cash the business can generate. After a sharp pullback over the past month and fresh headlines around high performance computing test demand, the focus shifts squarely to what the cash flow profile really supports.
- Cohu has returned 99.7% over the past year, which puts real pressure on the current share price to be supported by durable cash generation rather than short term enthusiasm.
- New high performance computing wins on the Eclipse platform and a growing opportunity pipeline can affect expectations for future testing volumes, margins and ultimately the timing and level of cash flows that feed into any intrinsic value work.
- Prefer to judge Cohu on sales? See what Cohu's 3.8x P/S says about the price.
The issue now is whether the current US$45.99 price tag is adequately backed by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to stress test the same cash flow question you are asking of Cohu across a broader watchlist, you can run the numbers against 32 high quality undervalued stocks.
Is Cohu Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here is built from the cash that Cohu can return to shareholders over time rather than near-term earnings headlines. Latest twelve month free cash flow sits at about $49.4 million, and the DCF framework assumes that this stream grows from current levels rather than shrinking, with projected annual free cash flows stepping up meaningfully through the next decade.
Those rising cash projections feed into an intrinsic worth that the DCF outcome suggests is substantially above the current US$45.99 share price. Because the Eclipse platform has just been selected for next generation high performance computing devices, that concrete HPC traction helps explain why a cash flow based view can screen as more optimistic than where the stock trades today. To see how that valuation stacks up in detail, you can review the full DCF output for Cohu and compare the implied worth to the market price. Find out what Cohu could be worth using our Discounted Cash Flow (DCF) estimate.
The Cohu Narrative: What Would Justify Today's Price?
Cohu's valuation question only really makes sense once you spell out the future that would need to unfold for the current share price to look either too low or too demanding. Simply Wall St Narratives sit on the Community page and turn this into plain assumptions about Cohu's growth path, margin profile and earnings power, with each one tying its number to a clear view of how those drivers and key risks could shift as new information comes through.
One of the top narratives on Cohu: 38% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Cohu is capitalizing on the surge in high-performance computing and the complexity of modern semiconductors by rolling out advanced, configurable handler platforms and test solutions..."
Discover why this Narrative puts Cohu at 38% undervalued.
Cohu valuation is only part of the story
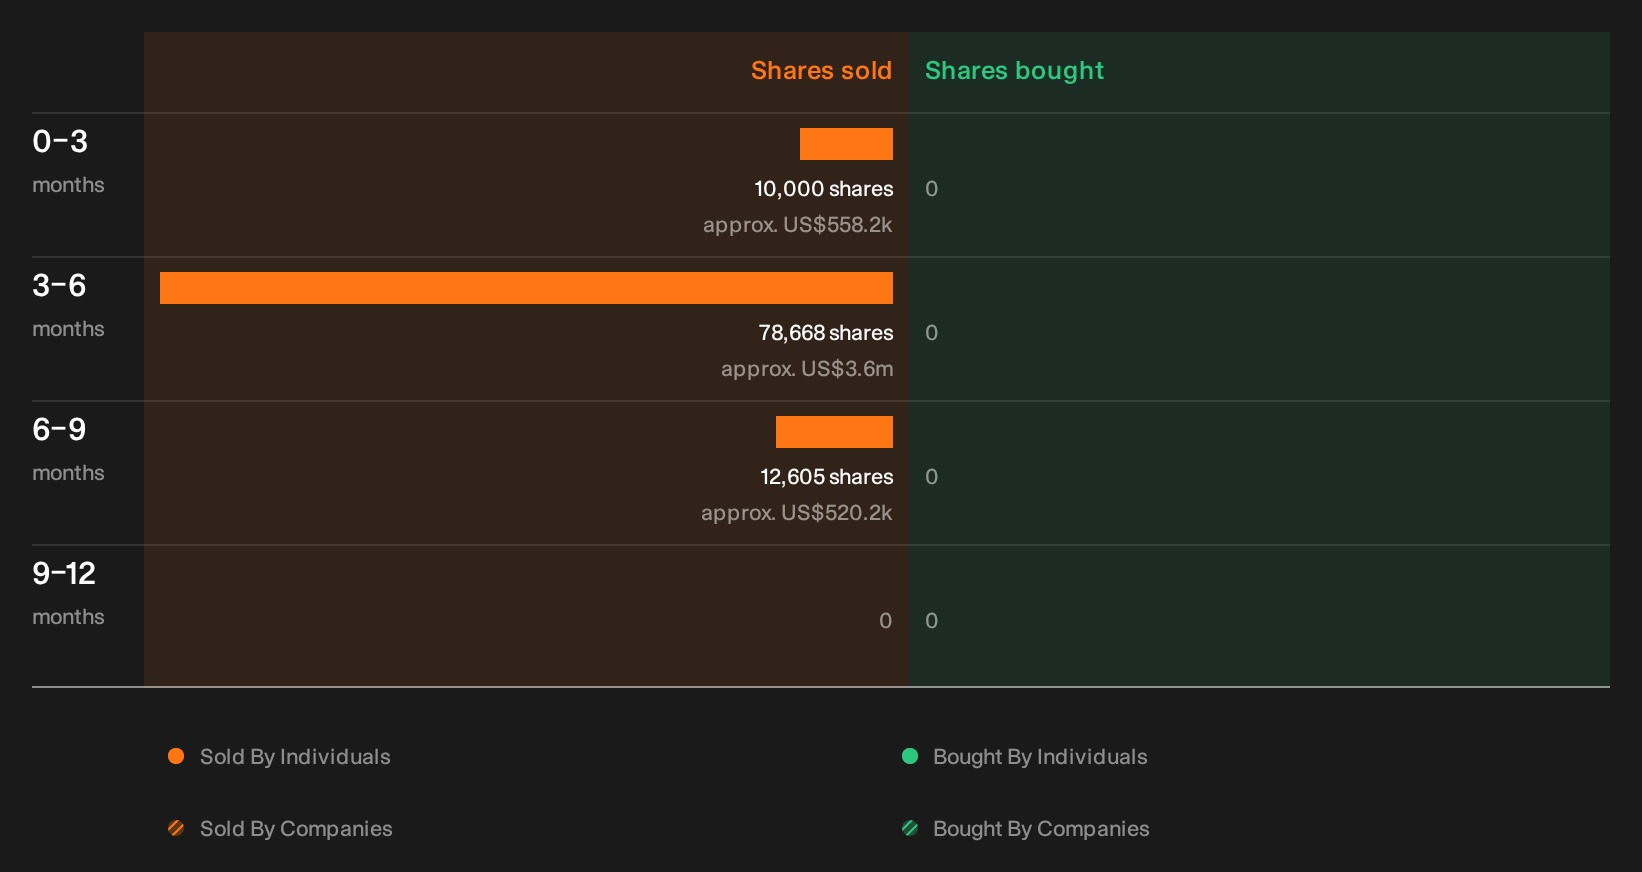
Before you lean too heavily on any cash flow model for Cohu, it is worth pausing on recent share sales by people inside the business, who sold, how much and what that might signal for you next. See the recent insider selling flagged for Cohu.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com