
Will Mixed Quarter Earnings Change Plains GP Holdings (PAGP) Narrative
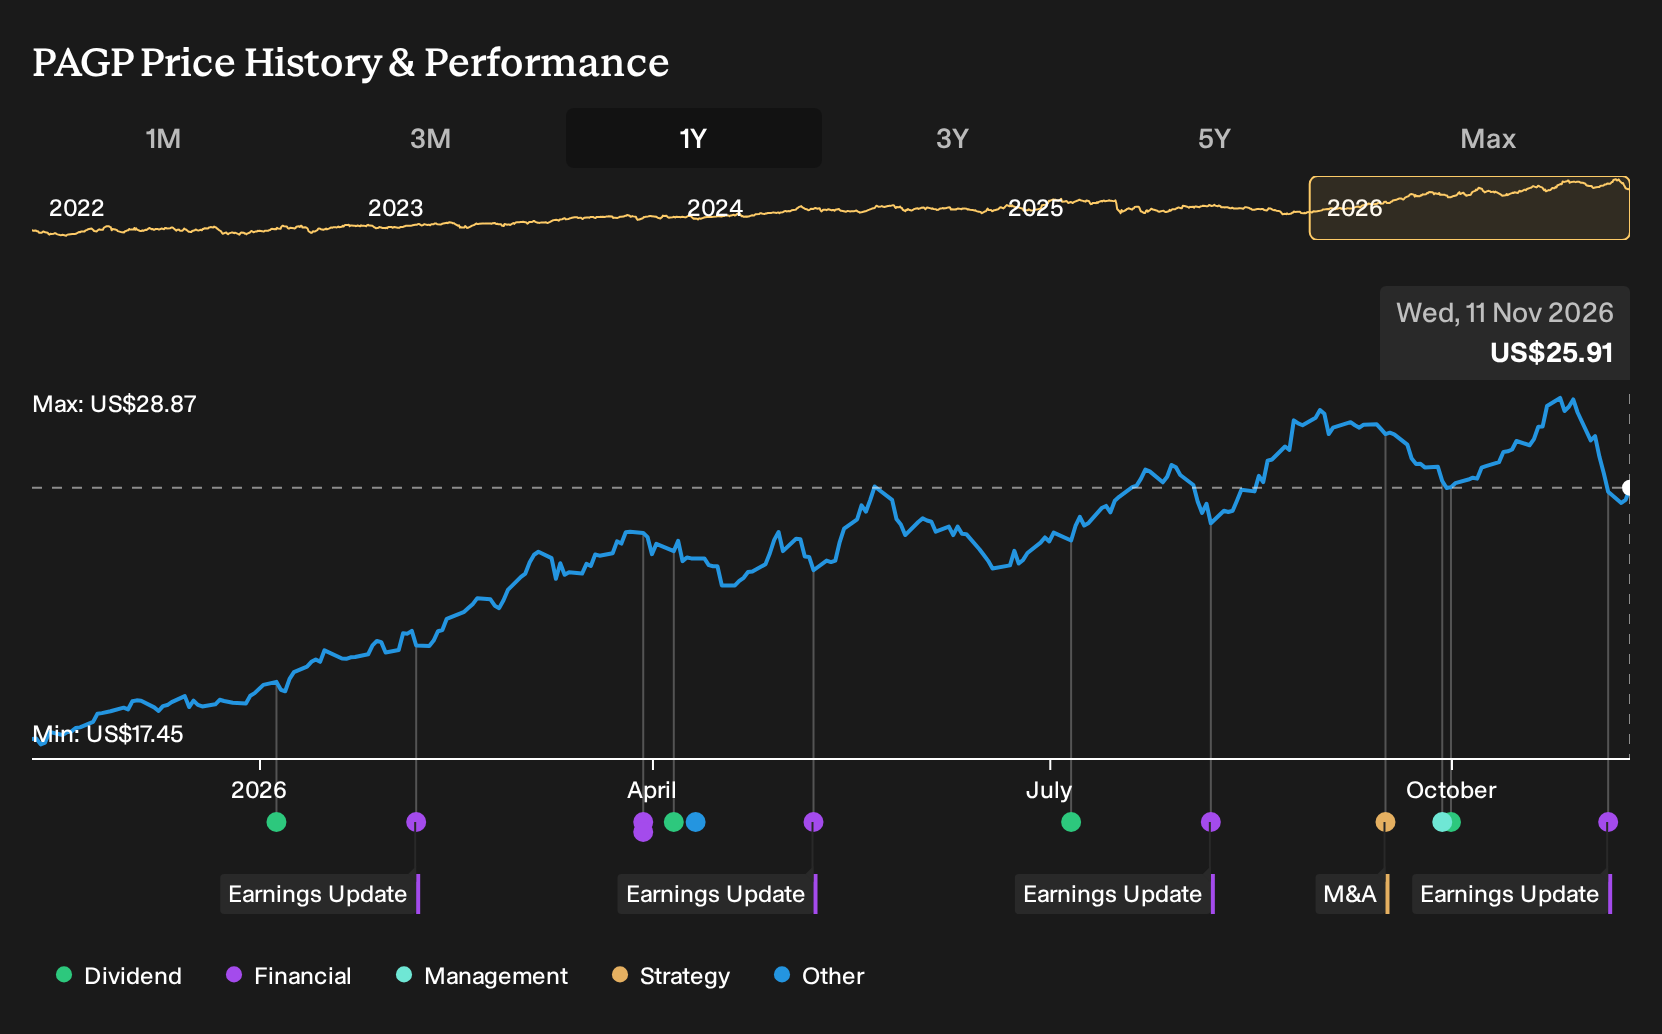
- Plains GP Holdings reported third quarter 2026 results with sales of US$15,173 million, net income of US$68 million, and a basic loss per share of US$0.16, alongside stronger nine month earnings compared with the prior year period.
- The contrast between higher quarterly sales and a quarterly loss per share, together with higher nine month net income, points to shifting cost or pricing pressures that matter for how Plains GP Holdings converts volume into earnings.
- We will look at how Plains GP Holdings' investment narrative around fee based midstream stability compares with this quarter's loss per share.
Scan how Plains GP Holdings' earnings swing compares with other fee based operators by zeroing in on a hand picked set of list of solid balance sheet and fundamentals (24 results)
Plains GP Holdings Investment Narrative Recap
For a shareholder in Plains GP Holdings, the core belief is that a crude focused, fee based midstream model can turn high volumes into steady cash generation over time. The latest quarter shows that this path is not linear. Sales reached US$15,173 million while basic loss per share swung to US$0.16, so short term earnings quality remains lumpy.
The analyst consensus Narrative on Simply Wall St focuses on efficiency programs, debt reduction and focused capital projects as near term swing factors. This quarter’s higher sales but lower net income point to cost and margin pressures as the key near term risk, rather than volume or growth capital timing.
The most relevant fresh data point is the same earnings release for the nine months to September 30, 2026. Over that period Plains GP Holdings recorded sales of US$45,334 million and net income of US$476 million, with basic earnings per share of US$1.90. Those figures help you look beyond one noisy quarter and assess whether the crude midstream thesis is tracking.
Nine month profitability also ties directly into the current catalysts in the analyst consensus Narrative on Simply Wall St. Debt reduction plans, cost saving targets and growth projects all depend on consistent cash generation, not just headline revenue. The quarterly loss per share therefore highlights execution risk around cost control and capital efficiency rather than indicating a clear break in the longer term story.
Plains GP Holdings' current loss of about US$1.2b is set against analyst expectations for earnings of US$622.8 million on revenue of US$62.3b by 2029. This implies 6.0% yearly revenue growth and an earnings swing of roughly US$1.8b over that period.
Uncover why Plains GP Holdings' fair value is effectively aligned with its current price.
Exploring Other Perspectives
Some of the lowest Plains GP Holdings forecasts focus on free cash flow strain rather than crude volume risk. Before this earnings report, the most cautious analysts were only pencilling in about US$58.0b of 2029 revenue and US$499.9 million of earnings. That is a tighter and more pessimistic story than the consensus, so treat it as one of several viewpoints to weigh as this latest quarter feeds into updated expectations.
Explore 4 other Plains GP Holdings fair value estimates, including one that suggests as much as 20% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Plains GP Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Plains GP Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plains GP Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Plains GP Holdings?
If this Plains GP Holdings update has sharpened your thinking about risk, income and balance sheet strength, it can be useful to widen the lens and compare it with other businesses that fit your preferred profile using the Simply Wall St Screener.
- For readers who want to focus on resilient businesses with conservative finances, start by scanning a 30 resilient stocks with low risk scores that keeps balance sheet risk front and center in your process.
- If income is a priority and you care about yield alongside staying power, review a curated group of 6 dividend fortresses that emphasise both payout and durability.
- To broaden your watchlist with lesser known opportunities that still clear fundamental quality checks, cast a wider net across 19 high quality undiscovered gems that might complement or contrast with Plains GP Holdings in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com