
Should Strong Q3 Earnings Require Action From CCL Industries Stock Investors?
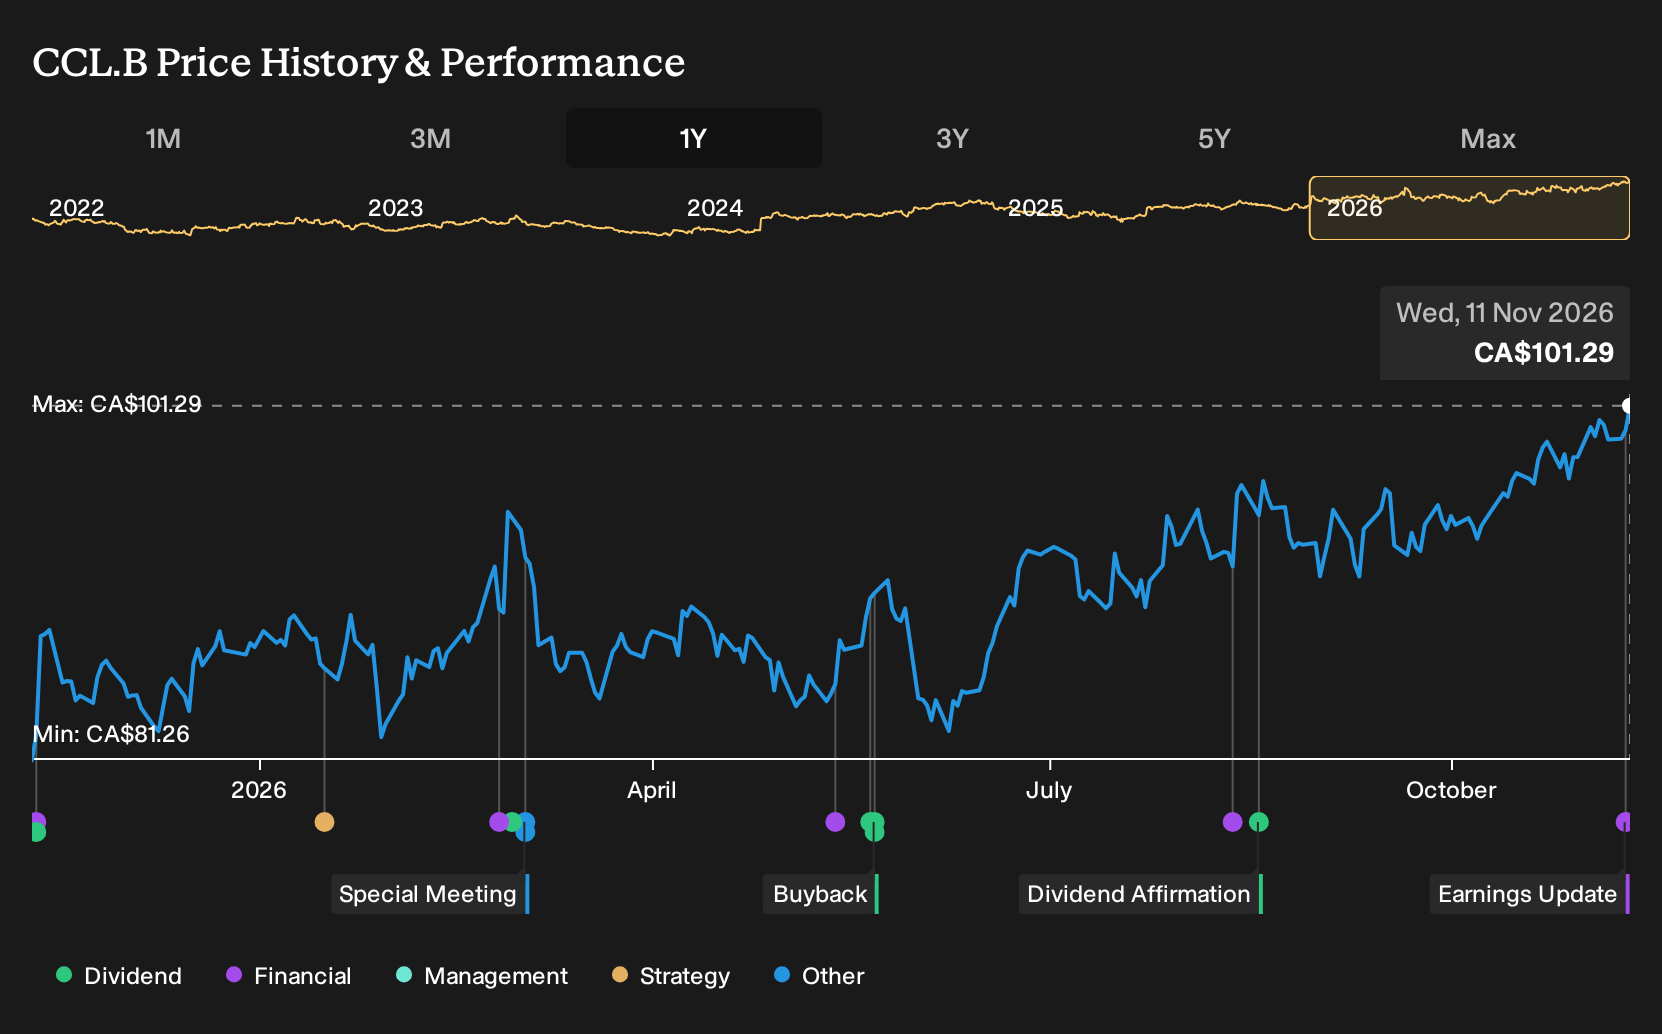
- CCL Industries reported past third quarter 2026 results with sales of C$2,219.9 million and net income of C$223.6 million, alongside higher basic and diluted earnings per share from continuing operations compared with the prior year period.
- The business also reported higher nine month sales and earnings per share, along with comments on strong free cash flow and liquidity, which points to management leaning on internal funding capacity to support ongoing global expansion and segment level investment.
- We will now look at how CCL Industries' higher quarterly earnings per share could shape the broader investment narrative around the business.
CCL Industries Investment Narrative Recap
To own CCL Industries, you need to be comfortable with a packaging and label group that leans on steady end demand, disciplined capital allocation and ongoing deployment into RFID and specialty films. The latest quarter showed higher sales, earnings and free cash flow, which supports that story. For the near term, the key swing factor is execution in intelligent labels and in the Avery and CCL segments, where recent operating income gains were concentrated.
The big operational risk still sits in margins and project ramp up. Regulatory pressure on plastics, slower volume environments in home and personal care or food, and any stumbles at newer plants such as Innovia in Germany could pressure profitability even if revenue holds up. The latest numbers do not remove these issues, but strong liquidity and internal funding capacity give management more room to keep investing while addressing them.
The analyst consensus narrative on Simply Wall St highlights continued expansion of intelligent labels and RFID solutions as a central long term driver. That makes the latest quarter particularly relevant, because management linked the 12.9% sales lift and 10.7% operating income gain to Avery and CCL, along with RFID and intelligent label strength. This is where the medium term growth argument increasingly lives.
The same release also pointed to strong free cash flow, a solid leverage ratio and ample liquidity, plus a regular dividend. For catalysts, that financial position matters. It gives CCL Industries capacity to keep funding global expansion, acquisitions and sustainability focused film projects without leaning heavily on higher risk funding. The tension for you as a shareholder is whether that reinvestment offsets risks from slower RFID growth, pricing pressure and rising regulatory costs around plastics and packaging.
CCL Industries' current revenue trajectory in analyst models points to CA$9.1b of sales and CA$963.1m of earnings by 2029, based on an assumed 4.7% yearly revenue growth rate. That pathway moves from earnings today of CA$810.6m to the 2029 consensus, which is an increase of about CA$152.5m in profit.
Uncover how CCL Industries' fair value indicates a 9% potential upside to its current price before the gap closes.
Exploring Other Perspectives
Retail investors in the Simply Wall St Community have only two fair value estimates for CCL Industries so far, ranging from C$109.90 to C$190.26, which is a wide gap for such a small sample. That split sits alongside risks related to RFID demand, tariffs and plastic regulation, so you should weigh several contrasting viewpoints before deciding how comfortable you feel with the story.
Explore another CCL Industries fair value estimate, including one that suggests it could be worth just CA$109.90.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CCL Industries research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CCL Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CCL Industries' overall financial health at a glance.
Looking for more CCL Industries investment ideas?
If CCL Industries has sharpened your interest in earnings led stories, you could broaden your watchlist by scanning other companies with focused screeners on Simply Wall St.
- For investors who want quality at a reasonable entry point, you can start with a curated set of potential value opportunities through 5 high quality undervalued stocks.
- If resilience matters more than excitement for you, you may consider a hand picked group of financially robust businesses highlighted in the 9 resilient stocks with low risk scores.
- For readers who care about steady income alongside fundamentals, there is a targeted collection of higher yielding payers in the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com