
APA Group (ASX:APA) Faces A Funding Squeeze, Where Does Fair Value Sit?
ANZ’s decision to stop funding new gas projects, including Beetaloo Basin pipelines, has put APA Group (ASX:APA) under a brighter spotlight as investors reassess financing risks around its long term pipeline ambitions.
Recent price action suggests investors are still willing to back APA Group despite funding questions. The share price is at A$11.19 and a 90 day share price return of 11.01% feeds into a 1 year total shareholder return of 25.81% and a 3 year total shareholder return of 61.69%. This points to momentum that has so far outweighed concerns around tighter bank support and management changes such as the appointment of Lucinda Gemmell.
Scan for other infrastructure and utilities stocks showing resilient funding stories and robust share price momentum by starting with our curated list of solid balance sheet and fundamentals (12 results).
APA Group now trades well above the average analyst target while still screening as heavily discounted on some intrinsic metrics. Where does fair value really sit within that spread, and what does the recent run imply?
Most Popular Narrative: 15% Overvalued
APA Group’s last close at A$11.19 sits above the A$9.77 fair value implied by the analyst consensus Narrative on Simply Wall St, which blends analyst targets with their revenue and earnings forecasts under a 7.18% discount rate.
The main thing that has to go right is APA Group converting its large, capital intensive project pipeline in gas pipelines and peaking power into durable, contracted cash flows without eroding returns through cost overruns or weak recontracting.
The current valuation implies investors are treating APA Group as a dependable high yield infrastructure stock with limited risk to cash flows from energy transition or regulation. This appears optimistic given its growing exposure to gas fired growth projects and policy scrutiny.
See why 78 investors see APA Group as 15% overvalued.
Result: Fair Value of A$9.77 (OVERVALUED)
Still, if gas demand across APA Group’s East Coast grid holds up and long term offtake deals keep locking in capacity, that cautious overvaluation story can begin to fray more quickly.
Find out about the key risks to this APA Group narrative.
Another View: Cash Flows Point the Other Way
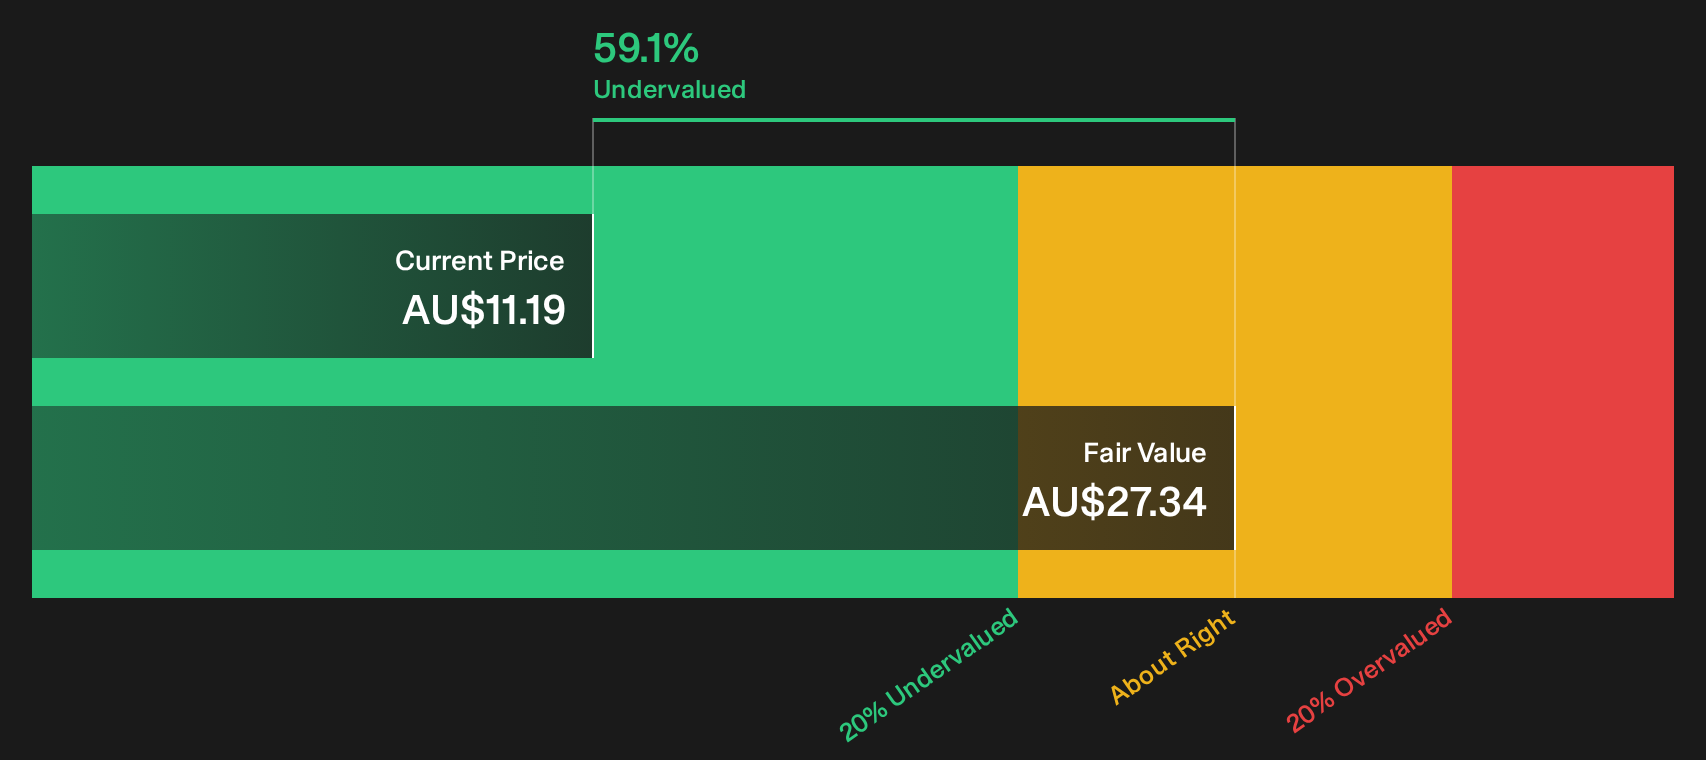
While analyst targets suggest APA Group is about 15% overvalued at A$11.19, the Simply Wall St DCF model points in the opposite direction. On that cash flow view, APA screens as trading 59.1% below an estimated future value of A$27.34. Which story do you trust more for a long term thesis?
To unpack how those projected cash flows are built and stress test the assumptions that drive such a large gap, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out APA Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on APA Group’s value story will not settle themselves. Move quickly, test the numbers, and weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond APA Group?
Do not stop your research at APA Group. Broaden your watchlist with fresh ideas that match your risk tolerance, income goals, and balance sheet comfort zone.
- Target potential mispricings by scanning a curated 3 high quality undervalued stocks that filters for quality fundamentals and compelling valuations.
- Strengthen your income toolkit through a focused 4 dividend fortresses built around higher yielding businesses with resilient payout profiles.
- Dial down portfolio stress with a 6 resilient stocks with low risk scores that highlights companies screened for sturdier financial and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com