
Guidewire Software (GWRE) Could Be 26% Undervalued After New Insurance Client Wins
Guidewire Software (GWRE) is back in focus after two Canadian insurers highlighted fresh deployments of its technology, including a major digital overhaul at Ontario's Workplace Safety and Insurance Board using the Jutro Digital Platform.
Those client wins arrive after a tough stretch for Guidewire Software's stock, with the share price down 7.3% over the past week and 15.7% year to date, while the 1 year total shareholder return has declined 28.4%. However, the 3 year total shareholder return remains up 62.4%, suggesting longer term holders have still seen meaningful gains even as near term momentum has cooled.
Spot opportunities across insurers embracing cloud, AI and workflow automation by scanning the curated 42 profitable AI stocks that aren't just burning cash.Guidewire Software now pairs fresh client wins with a share price that has pulled back sharply. Does that combination still leave enough upside potential to justify the current valuation risk?
Most Popular Narrative: 26% Undervalued
Guidewire Software closed at $158.16 against an analyst consensus fair value of $213.29, and the analyst consensus Narrative on Simply Wall St frames that gap around the durability of its cloud and AI driven revenue engine under an 8.69% discount rate.
The industry's transition to cloud based systems, particularly in the property and casualty insurance sector, is steadily accelerating, which may facilitate future revenue growth as more customers migrate to the Guidewire Cloud Platform and expand cloud ARR and subscription revenue.
Embedding AI driven assistants like ProNavigator and new developer tools directly into PolicyCenter, ClaimCenter, and UnderwritingCenter creates scope for higher value software tiers and services productivity, which can support future gains in subscription and services margins.
See why 11 investors see Guidewire Software as 26% undervalued.
Result: Fair Value of $213.29 (UNDERVALUED)
Still, if insurer IT budgets tighten or cloud migrations slow relative to expectations, the Guidewire Software narrative, built around premium ARR quality, could fray.
Find out about the key risks to this Guidewire Software narrative.
Another View on Guidewire Software's Valuation
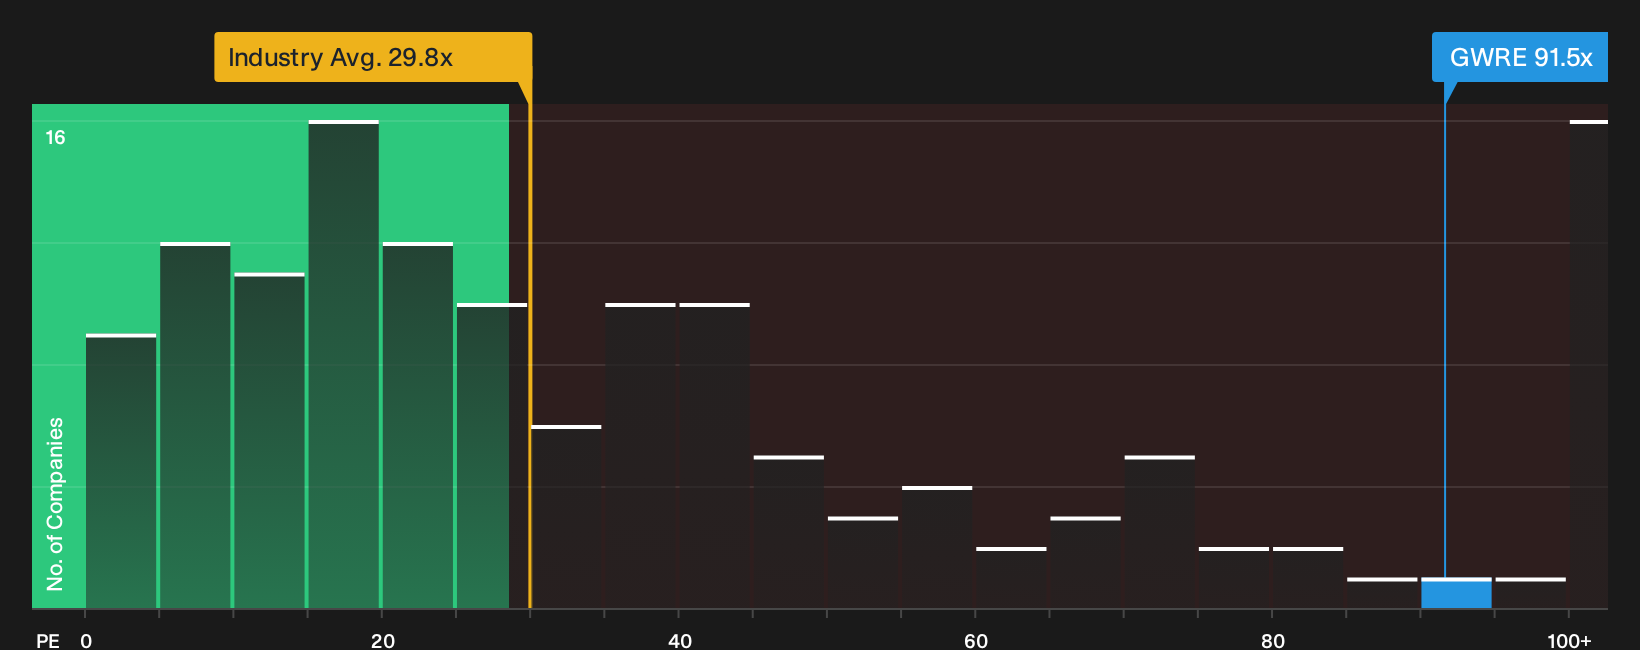
On simple earnings multiples, Guidewire Software looks expensive. The P/E sits at 93.1x, while peers trade around 37.7x and the fair ratio is 40x, which points to a rich setup and higher valuation risk if growth or sentiment cools from here.
That kind of premium forces a tougher question for you as an investor. Is the growth narrative strong enough to keep justifying a P/E more than double both peers and the fair ratio, or does this gap leave more room for disappointment than upside potential?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Guidewire Software's share price, client wins, and valuation can be confusing at first glance, so move quickly to inspect the full risk and reward breakdown yourself and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Guidewire Software?
Do not stop at one stock. Put Guidewire Software in context by lining it up against other opportunities that match your style, risk tolerance, and income goals.
- Target resilient cash generators and sharpen your downside protection with the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality and compare Guidewire Software against the 32 high quality undervalued stocks.
- Build a cash payout stream that works while you sleep by scanning the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com