
Is Philip Morris International (PM) Fairly Valued Following State Street’s Stake Increase?
Philip Morris International (PM) is back in focus after the State Street Consumer Staples Select Sector SPDR ETF reversed course, lifting its position by US$25.2 million on November 9.
Recent trading has been choppy. The share price return is up 22.49% year to date and the 1 year total shareholder return is 30.69%. However, the 7 day share price return declined 7.07% and the 30 day share price return fell 2.80%, hinting that momentum has cooled even as long term holders still sit on strong gains supported by Philip Morris International’s push into smoke free products, a higher dividend and fresh institutional interest.
Scan how Philip Morris International compares with other consumer staples movers by running your eye over a curated list of 36 high quality undervalued stocks that combine quality with compressed expectations.
After a 22.49% year to date climb and a 30.69% 1 year total return, Philip Morris International now sits in trickier territory. Is most of the easy upside already used up, or do the current valuation markers still hint at more to come?
Most Popular Narrative: 4% Overvalued
Philip Morris International last closed at $196.35, compared with a narrative fair value estimate of $188.78. This implies the stock trades at a modest premium according to this view and sets up a closer look at what is driving that gap.
The first is the modified risk tobacco product authorization for twenty ZYN SKUs. Management had called it the “icing on the cake” of the brand’s U.S. repositioning, the regulatory clearance that let the company market the specific claim that ZYN use carries lower risk than cigarettes across six disease categories. On a call built almost entirely around ZYN, where the brand’s reported numbers outperformed scanner data enough that one analyst (Jefferies’ Andrei Andon) asked for a reconciliation, repeating the question once at Andolina’s request, the authorization does not get a single mention.
See why 3 investors see Philip Morris International as 4% overvalued.
Result: Fair Value of $188.78 (OVERVALUED)
Still, the narrative could be knocked off course if U.S. smoke free momentum cools, or if rising excise taxes squeeze Philip Morris International’s pricing power.
Find out about the key risks to this Philip Morris International narrative.
Another View: Philip Morris International Through Earnings Ratios
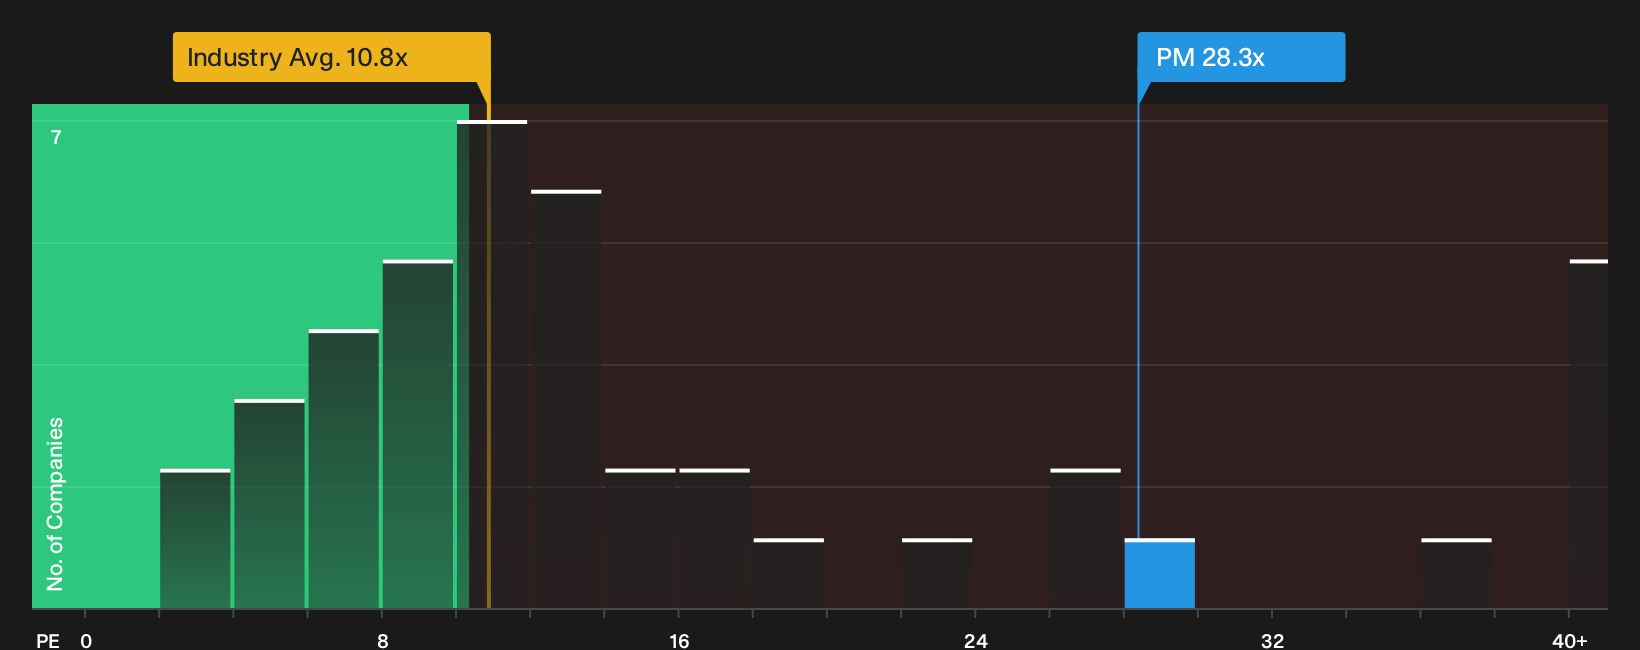
Philip Morris International looks only slightly rich against its own fair ratio. The stock trades on a P/E of 28.3x, close to an estimated fair ratio of 29.1x, which implies limited room for error if sentiment cools or earnings fall short.
The picture shifts once you widen the lens. That same 28.3x multiple is far higher than the global tobacco sector on 10.8x and still above a peer set on 26.9x. Paying that kind of premium for Philip Morris International could make sense for some investors, but it raises a blunt question: How patient are you willing to be if the rest of the group keeps pricing in less optimism?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can cut both ways. This is why it helps to move fast, review the full picture yourself, then weigh the 3 key rewards and 1 important warning sign.
Hunting For Your Next Idea Beyond Philip Morris International
If you stop at Philip Morris International, you miss the wider opportunity set. Let the data surface new angles so your watchlist keeps working for you.
- Spot potential value candidates early by reviewing a focused 36 high quality undervalued stocks that blend solid fundamentals with muted expectations.
- Lock in more dependable income streams by scanning a curated group of 5 dividend fortresses that prioritize durability as much as yield.
- Protect your downside first by filtering for 30 resilient stocks with low risk scores that pair resilient balance sheets with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com