
Forbright Is Just One Of These 3 Insider Owned Growth Stocks
Hotter than expected inflation and the prospect of a December Fed rate hike have put dependable growth back under the spotlight. Higher borrowing costs can punish fragile balance sheets, which is why fast expanding businesses where insiders own a lot of stock can look especially interesting. This article walks through three such high growth, high insider commitment stocks from the US, and what makes each worth a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses with management and analysts aligned on an optimistic outlook. However, if you want the absolute best, these 55 high growth high conviction stocks are the cream of the crop.
Forbright (FRBT)
Forbright is a US-based bank holding company that runs a national lending platform and digital consumer banking operation, generating about US$332 million in banking revenue and carrying a market value of roughly US$952 million. This ties directly into the screener’s focus on growth backed by engaged insiders.
The analyst consensus Narrative on Simply Wall St frames Forbright as a lender using technology and funding mix to pursue faster growth than many traditional banks. Its digital and middle market focus is central to that outlook and a key reason it sits in a high growth, high insider commitment screen.
"Expansion of the proprietary digital deposit platform, including promotion tools and the upcoming digital checking product, is building a lower cost, granular funding base that can support asset growth and influence net interest margin and overall funding costs."
What matters from here is how one pressure on future profitability evolves as Forbright leans further into this growth playbook.
That pressure point is exactly where the story gets interesting, and the full narrative for Forbright explains how Forbright’s funding mix, risk controls and growth ambitions could be accelerating beneath the surface.

Pinterest (PINS)
Pinterest runs a visual search and social commerce platform where people plan projects and shop from ideas, generating about US$4.7b in Internet Information Providers revenue and a market value of roughly US$10.9b.
Pinterest fits the fast growing, high insider commitment theme because its ad and shopping tools are built directly on user intent. The analyst consensus Narrative on Simply Wall St highlights how that link between engagement and monetization is central to the long term story.
"Ongoing advancements in AI-driven visual search and personalized content curation, supported by proprietary multimodal and generative retrieval models, are deepening user engagement and increasing session times."
What happens to margins and revenue momentum depends on how one unresolved pressure in international monetization is resolved over the next stretch.
That pressure point is exactly where the full narrative for Pinterest maps out whether Pinterest’s international monetization gap is masking accelerating upside or is instead stretching this ad story too far.

Estée Lauder Companies (EL)
Estée Lauder Companies is a global beauty group built around prestige skincare, makeup, fragrance and hair care. Its strongest tie to this fast growing, high insider ownership theme comes from high growth skincare and makeup brands sold through expanding direct to consumer and online channels.
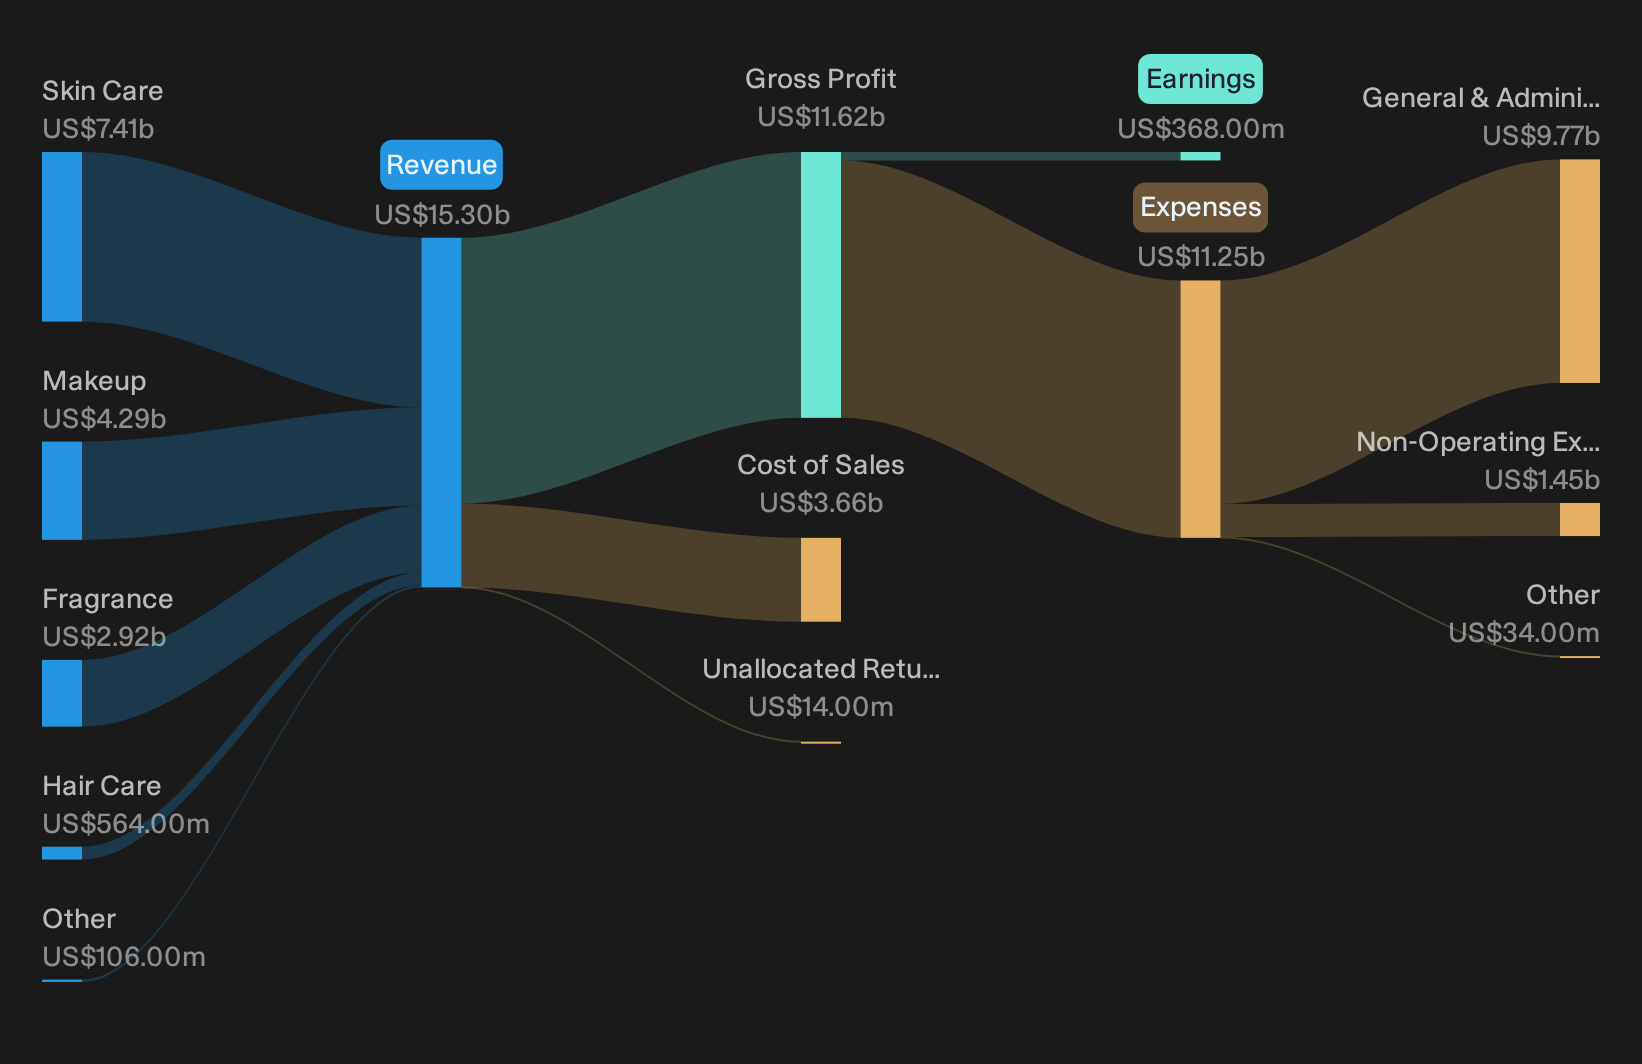
The business produces a wide range of premium products under labels such as La Mer, Clinique, M·A·C and The Ordinary, with skin care generating about US$7.4b of revenue and makeup about US$4.3b, while fragrance and hair care add roughly US$2.9b and US$564 million respectively. Together, these support a market value of around US$41.1b.
For investors using this screener, Estée Lauder Companies brings a mix of prestige brands, growing direct channels and high insider ownership that link directly to the theme of growth backed by management confidence. The analyst consensus Narrative on Simply Wall St presents the company as a business in profit recovery while leaning more heavily into digital and e-commerce.
"Estée Lauder Companies is progressing its multi year Profit Recovery and Growth Plan and One ELC operating model, which has already lifted gross margin by nearly 400 bps between fiscal 2024 and fiscal 2026 and expanded operating margin by 320 bps to 11.2%. If these actions do not translate into the intended cost savings or disrupt consumer facing execution, the company could face ongoing SG&A pressure that limits net margin expansion and earnings growth."
What happens to that carefully rebuilt earnings picture will hinge on how one underappreciated pressure on future margins and cash generation ultimately resolves.
That margin pressure is exactly why you should read the full narrative for Estée Lauder Companies to see whether Estée Lauder Companies is quietly accelerating its profit recovery story.
Seeking Fresh Alternatives Before They Fly
New ideas often move first, and some breakouts can advance before the broader market pays attention. Scan fresh momentum while it matters, under the radar for now, and consider opportunities early.
- Identify under the radar compounders with resilient balance sheets by scanning the curated list of solid balance sheet and fundamentals (24 results) before other investors focus on the same quality signals.
- Follow developments in automation by tracking companies inside the hand picked 89 robotics and automation stocks while robotics momentum is developing and expectations remain measured.
- Review the focused 42 power grid technology and infrastructure stocks for businesses linked to modern energy infrastructure as part of evaluating the ongoing grid upgrade cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com