
How Investors Are Reacting To HELLA GmbH KGaA (XTRA:HLE) Guidance Reaffirmed After Mixed Quarter
- HELLA GmbH KGaA confirmed its full year 2026 operating income margin guidance at around 5.4% to 6.0%, while third quarter sales reached €1,910.87 million and net income came to €33.48 million.
- The nine month figures show HELLA GmbH KGaA delivering €5,883 million in sales and €130.98 million in net income, which contrasts with the softer third quarter profit and highlights the tension between near term pressure and a steady full year margin target.
- We will now look at how HELLA GmbH KGaA's confirmed margin guidance could reshape the investment narrative built around prior analyst assumptions.
Scan list of solid balance sheet and fundamentals (194 results) to compare HELLA GmbH KGaA's confirmed margin outlook with other companies that pair earnings resilience with a robust financial footing.
HELLA GmbH KGaA Investment Narrative Recap
To own HELLA GmbH KGaA, you need to be comfortable with a story where Electronics and Lifecycle Solutions carry more of the profit load while Lighting is repaired through the Lighting Transformation Program 2.0. The confirmed 2026 operating margin guidance of about 5.4% to 6.0%, with management pointing to the lower end, suggests limited short term upside but also no immediate downgrade shock.
The key near term catalyst remains execution on cost programs and Lighting mix so that group margins can hold inside that guidance range despite weaker quarterly earnings. The biggest risk is that Lighting volumes or pricing underperform those plans, which could pull profitability and cash conversion below what the analyst consensus Narrative on Simply Wall St currently factors in.
The most relevant announcement here is the 2026 full year guidance confirmation, paired with the third quarter report. HELLA GmbH KGaA posted €1,910.87 million in quarterly revenue, €33.48 million in net profit and basic EPS of €0.30, alongside nine month figures of €5,883 million of sales and €130.98 million in earnings.
Those numbers show a softer third quarter against relatively healthier nine month profitability, which keeps attention squarely on execution in the final stretch of the year. For you as a shareholder, the operational question is whether cost savings, Electronics growth and Lighting Transformation Program 2.0 can keep the full year margin inside the guided band while cash flow absorbs restructuring needs.
What The Current HELLA GmbH KGaA Forecasts Assume
The analyst framework around HELLA GmbH KGaA leans heavily on a slow build in revenue and a much steeper climb in profitability. Forecasts point to top line expansion of 2.1% a year over the next three years, while margins are expected to move from 1.5% today toward 6.1% on roughly the same timetable. That combination asks you to believe that Electronics and Lifecycle Solutions do more of the heavy lifting and that Lighting Transformation Program 2.0 turns a weak division into one that earns closer to the group target.
On earnings, the consensus view is specific. Analysts are working with current earnings of €115.6 million and a projection that net profit reaches €509.8 million by about 2029. That implies profit a little more than 4x higher than today, supported by higher margins rather than rapid sales growth. For an investor, the key question is less about whether revenue grows at 2.1% and more about whether this margin reset is realistic while HELLA GmbH KGaA still spends on restructuring, R&D efficiency projects and footprint changes.
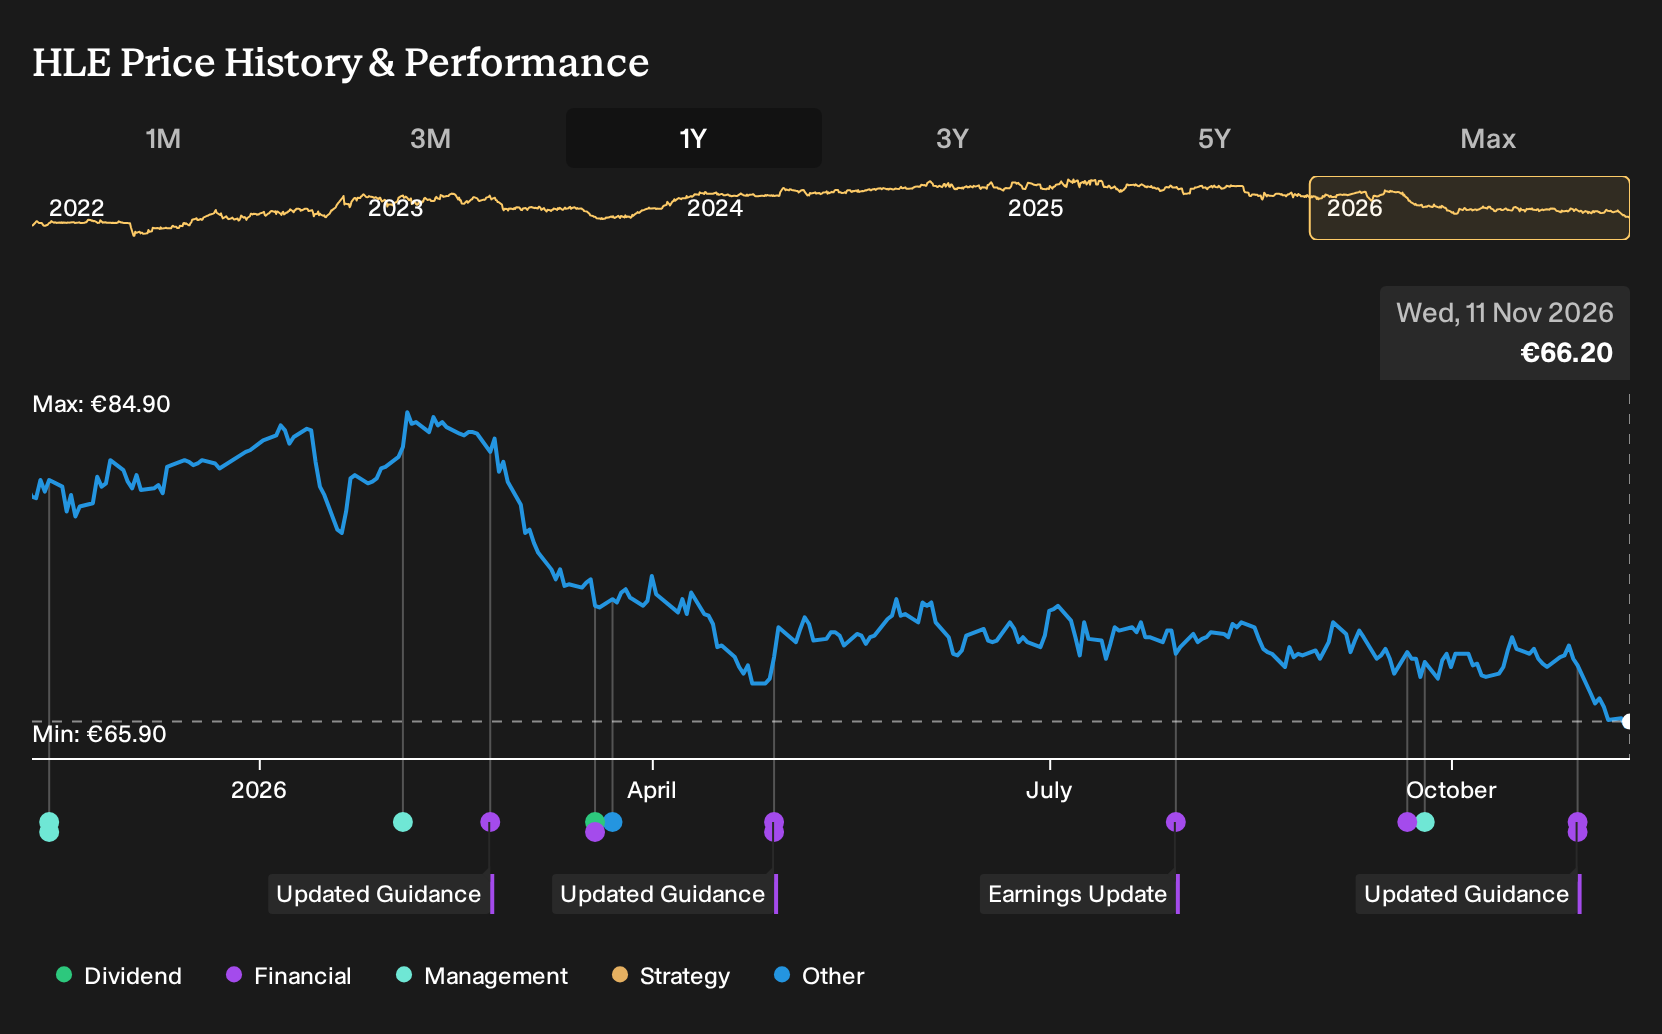
Those same assumptions feed straight into the valuation template. The group of analysts cited in the Simply Wall St report flag a consensus price target of €65.0 per share, framed against a current share price of €68.9 as at late 2026. The gap between the two numbers is 6.0%, which indicates that, on average, they see HELLA GmbH KGaA trading close to what their models suggest is fair based on the 2029 earnings profile.
For that price target to hold, several valuation anchors need to line up. The forecasts call for HELLA GmbH KGaA to generate about €8.4b in revenue and €509.8 million in earnings by 2029, while the stock trades on a P/E of 17.1x those earnings. That multiple would be lower than the current P/E of 66.2x that the report cites for HELLA GmbH KGaA today and below the 19.5x level mentioned for the wider GB Auto Components sector, implying that much of the hoped for profit rebound is already accounted for in today’s price.
HELLA GmbH KGaA's narrative projects €8.4b revenue and €509.8 million earnings by 2029. This requires 2.1% yearly revenue growth and profit to rise by a little more than 4x from €115.6 million today.
Uncover why HELLA GmbH KGaA's fair value is essentially in line with its current price.
Exploring Other Perspectives
The Simply Wall St Community currently offers 2 fair value estimates for HELLA GmbH KGaA, ranging from just €2.29 per share to €65, so retail opinion spans extreme outcomes. You also see strong order intake in electronics and Lighting Transformation Program 2.0 as potential catalysts, which could materially influence how these private investors reassess the business.
Explore another HELLA GmbH KGaA fair value estimate, including one that suggests as much as 97% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your HELLA GmbH KGaA research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for HELLA GmbH KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HELLA GmbH KGaA's overall financial health at a glance.
Looking for more investment ideas beyond HELLA GmbH KGaA?
If the HELLA GmbH KGaA story has sharpened your sense of what you want in a business, you can use that clarity to widen your search across the market.
- If capital protection and steadier price swings matter most to you, consider a focused set of 209 resilient stocks with low risk scores that may better fit a controlled risk profile.
- If you prefer owning companies that already generate strong cash flows and have firmer footing, explore a curated list of solid balance sheet and fundamentals (194 results) that matches those priorities.
- If you want to look earlier at underfollowed opportunities with healthier fundamentals, cast a wider net across a 563 high quality undiscovered gems that rarely appear on mainstream radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com