
Advantest Stock Eyes Earnings Upgrade After Strong Half Year Results
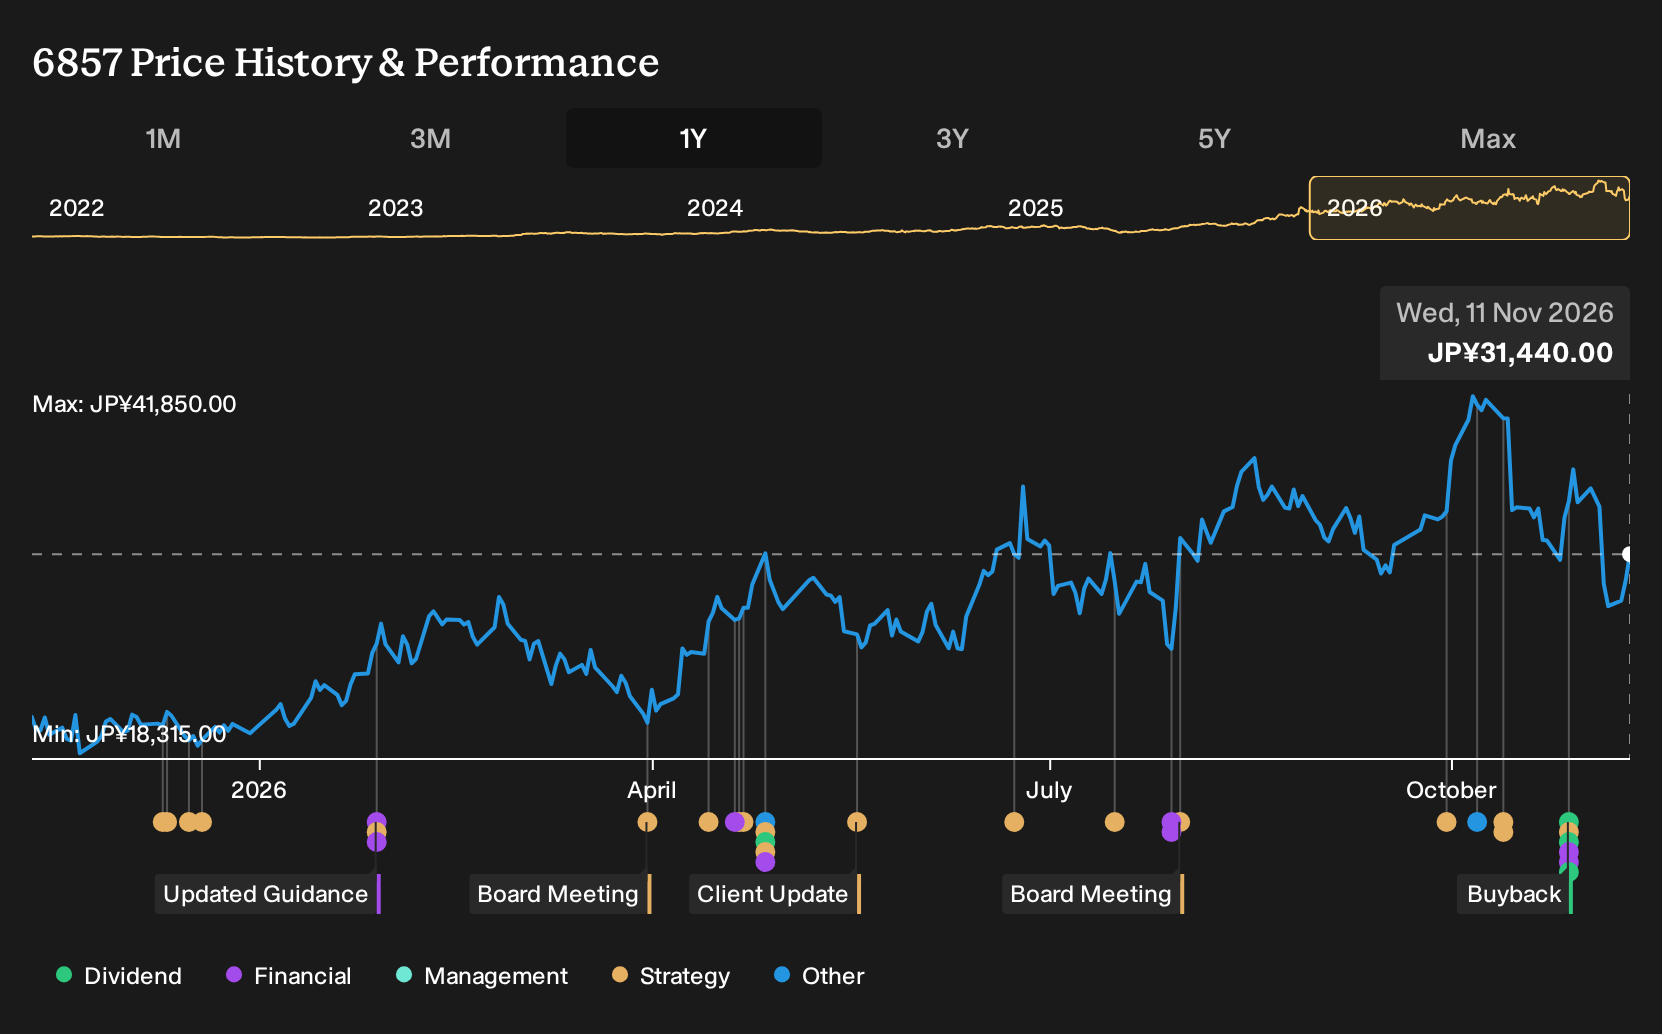
- Advantest announced a share repurchase program of up to 11,000,000 shares and confirmed a higher interim dividend, alongside updated full year guidance and first half results.
- The combination of stronger half year earnings, a steeper full year profit outlook and increased cash returns signals management confidence in Advantest's current operating momentum.
- We will look at how Advantest's investment narrative is shaped by the upgraded full year earnings guidance and recent cash return decisions.
Scan how Advantest’s buyback, dividend lift and upgraded guidance compare with peers by reviewing the hand-picked 24 high quality undervalued stocks that may offer similar earnings momentum and disciplined capital returns.
Advantest Investment Narrative Recap
To own Advantest, you effectively need to believe the analyst consensus Narrative on Simply Wall St that AI driven chip complexity keeps translating into heavy use of its SoC and memory testers, and that high capacity can stay well utilised. The raised full year guidance and strong first half earnings point to healthy order conversion, which supports that view without changing the basic thesis.
The key near term swing factor remains how smoothly capacity and product ramps are absorbed by customers versus any pause in tester orders. The biggest operational risk is still a less friendly cost mix or softer demand that pulls gross margin off recent levels and exposes the fixed cost base from recent expansion.
The upgraded full year guidance looks most relevant here. Advantest now projects ¥1,863,000m in net sales and ¥967,000m in operating income, with net income of ¥741,500m. That is higher than the prior outlook and sits alongside half year revenue of ¥845,200m and net income of ¥368,083m.
Those figures give you a cleaner data point on execution versus the capacity and demand risks already flagged. Stronger earnings can help absorb bill of materials inflation and higher DRAM costs, yet the sensitivity to any pullback in AI related tester orders or lumpier memory tester adoption remains central to the near term catalyst path.
Advantest's narrative points to revenues of ¥2,788.3b and earnings of ¥1,113.8b by 2029, based on analyst estimates that factor in 31.3% yearly top line growth. That projection assumes a move from earnings today of ¥460.0b to the ¥1,113.8b consensus, which is an increase of about ¥654b by the 2029 forecast year.
Discover how Advantest's fair value identifies a 43% potential upside to its current price before the market reflects that difference.
Exploring Other Perspectives
One alternate view leans hard into Advantest’s capacity ramp as the real catalyst. Bullish analysts were already modeling revenue of ¥4,081.9b and earnings of ¥1,619.8b by 2029 before this buyback, dividend lift and guidance change. That is a far more optimistic story, and it may shift again as fresh data lands.
Explore 2 other Advantest fair value estimates, including one that suggests potential upside of up to 48% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Advantest research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advantest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advantest's overall financial health at a glance.
Looking for more investment ideas beyond Advantest?
Once you have a handle on Advantest and its latest narrative, it can help to widen the lens and compare it with other stocks that share similar qualities in value, resilience or income potential.
- If you want companies where the market price sits below what the fundamentals suggest, scan through a curated 24 high quality undervalued stocks that filters for robust cash flows and solid balance sheets.
- For investors who care most about capital strength and financial resilience, review a focused list of solid balance sheet and fundamentals (23 results) that screens for conservative leverage and healthy liquidity.
- If income is a priority and you are hunting for higher yields with staying power, work through a targeted 29 dividend fortresses that highlights sturdier payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com