
Definium Therapeutics (DFTX) Stock Looks Above Fair Value On Phase 3 Progress
Definium Therapeutics has logged an extremely strong multi year share price run, and the latest clinical headlines now raise a sharper question about how that market value lines up with its book value. With the stock carrying a recent close of US$34.64, investors are asking whether the balance sheet can support that kind of market optimism.
- Over the past 3 years the share price has delivered a very large return, which puts substantial weight on whether the current valuation is still grounded in the company’s underlying net assets.
- Positive Phase 3 data for DT120 in anxiety and depression, together with plans for an NDA filing in 2027, can influence expectations for future revenue and capital needs, which feeds directly into how much of a premium investors are willing to pay over book value.
- There is a second opinion on Definium Therapeutics worth weighing. See what analysts think Definium Therapeutics's shares could be worth.
The issue now is whether Definium Therapeutics' recent market value is adequately supported by its book value once you strip the story back to the balance sheet.
If you are weighing Definium Therapeutics against other book value driven opportunities, it can help to compare it with 35 high quality undervalued stocks.
Is Definium Therapeutics Getting Expensive on Book Value?
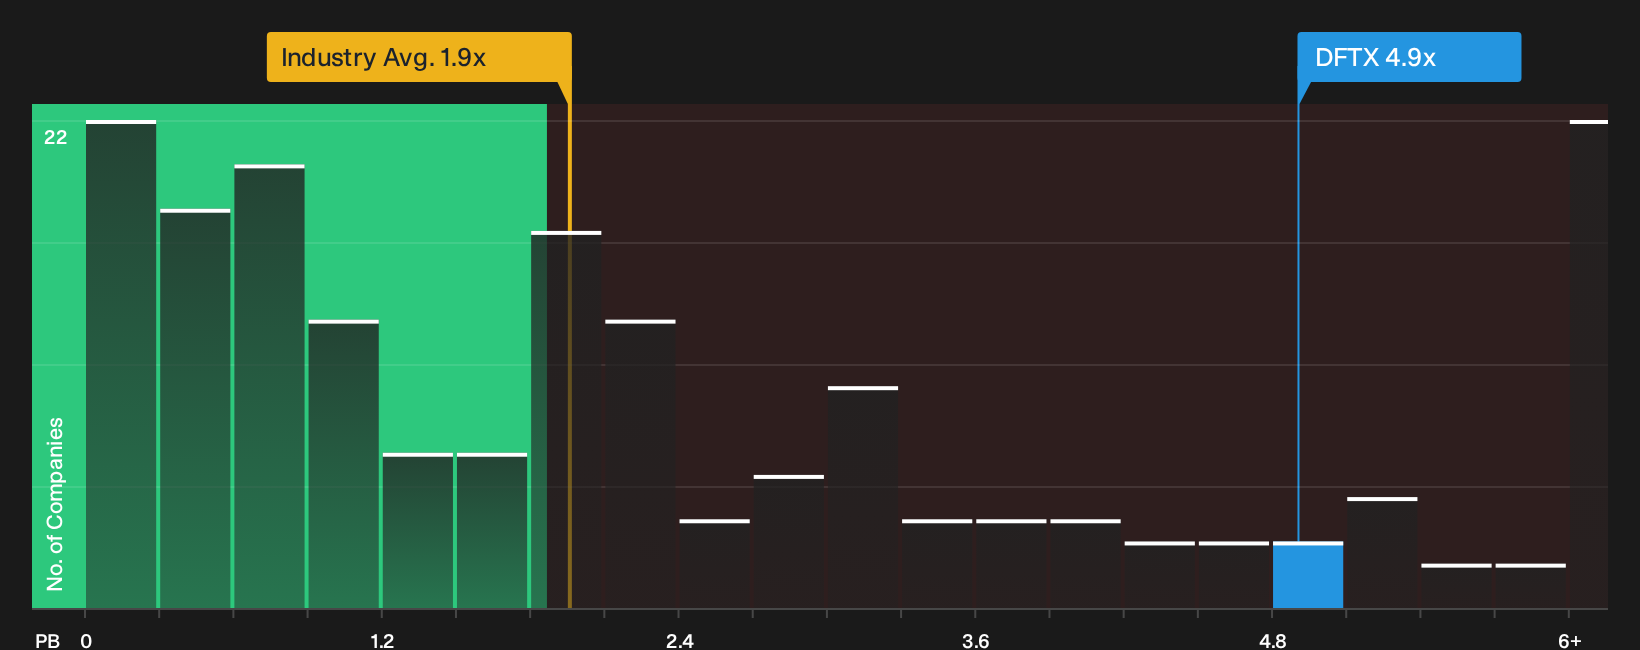
P/B is a useful lens for Definium Therapeutics because investors are weighing a balance sheet heavy on R&D against a market value built on future trial outcomes. On this yardstick, the stock trades on a P/B of 4.9x, which is well above the Pharmaceuticals sector average of 1.9x and also ahead of peers around 3.9x. That gap signals you are paying a sizeable premium over the accounting value of Definium Therapeutics' net assets compared with much of the industry.
Because the latest Phase 3 DT120 results and the planned NDA filing in 2027 have sharpened optimism around the pipeline, the current P/B suggests those milestones are already baking a lot of expectation into the share price. For anyone comparing Definium Therapeutics with more book value anchored opportunities, the question is whether that premium feels justified by the asset base and clinical progress, or whether it leaves less room for error than lower multiple alternatives. Explore the numbers behind Definium Therapeutics's P/B valuation.
The Definium Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Definium Therapeutics pick up where the P/B puzzle leaves off by explaining which paths for growth, margins and earnings would need to occur for the share price to appear meaningfully higher or lower than it does today on the screen. Each scenario links its implied number to a clear view on how Definium Therapeutics' prospects and risks might change, giving you something concrete to revisit when fresh data or trial news arrives.
One of the top community narratives on Definium Therapeutics: 43% undervalued
According to Ontological, a Simply Wall St Community investor who wrote the Narrative, Definium Therapeutics sits at the front of late stage psychedelic medicine.
"With three successful Phase 3 trials completed in anxiety and depression, Definium is now preparing for a landmark FDA submission in 2027..."
Discover why this Narrative puts Definium Therapeutics at 43% undervalued.
One more piece of Definium Therapeutics that could change the picture
Valuation only tells part of the story for Definium Therapeutics, because our broader review has also highlighted specific red flags that could matter a lot to long term holders. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com