
Nippon Densetsu Kogyo (TSE:1950) Issued New Earnings Guidance, Is The Upside Already Priced In?
Nippon Densetsu Kogyo (TSE:1950) has put fresh numbers on the table by issuing consolidated earnings guidance for the fiscal year ending March 31, 2027, giving investors clearer visibility on expected performance.
The new guidance lands after a strong run, with Nippon Densetsu Kogyo’s share price delivering a 14.31% year to date return and a 1 day gain of 2.02%. Total shareholder return of 28.41% over one year and 158.13% over five years points to momentum that has been building rather than fading.
Scan how Nippon Densetsu Kogyo compares with other power grid and rail infrastructure plays by reviewing the hand picked 42 power grid technology and infrastructure stocks shaping this part of the market.
Bulls point to Nippon Densetsu Kogyo’s earnings guidance and recent share price strength, while bears question how much of that is already reflected in the price. Which side does the current valuation support?
Preferred P/E of 10.9x for Nippon Densetsu Kogyo: Is it justified?
On a P/E of 10.9x at a last close of ¥3,795, Nippon Densetsu Kogyo trades at a level that suggests the market is not assigning a steep premium relative to peers, even though our data flags the shares as slightly expensive versus the broader construction group.
The P/E multiple compares the current share price with earnings per share. For a contractor rooted in power grid and rail projects, this is a practical way to gauge how much investors are willing to pay for each unit of profit, especially when earnings quality and consistency matter more than rapid expansion.
Here, the picture is mixed. The stock is marked as expensive against the JP Construction industry average P/E of 10.4x, which implies investors are paying a bit more than the sector for Nippon Densetsu Kogyo’s earnings stream. At the same time, the P/E sits below the peer average of 11.7x and below an estimated fair P/E of 12x, which signals the market could be pricing the shares somewhat conservatively compared with what the fair ratio suggests.
Explore the SWS fair ratio for Nippon Densetsu Kogyo.
Result: Price-to-Earnings of 10.9x (ABOUT RIGHT)
Still, that story can crack if earnings guidance is revised lower, or if tender activity in rail and power projects softens materially.
Find out about the key risks to this Nippon Densetsu Kogyo narrative.
Another View: Nippon Densetsu Kogyo Through a Cash Flow Lens
A different angle comes from the SWS DCF model, which points to a future cash flow value of ¥4,333.68 per share, compared with the current ¥3,795 price. That 12.4% gap suggests the market is asking less than this framework indicates. Does that represent a margin of safety, or a signal the model is too optimistic?
Look into how the SWS DCF model arrives at its fair value.
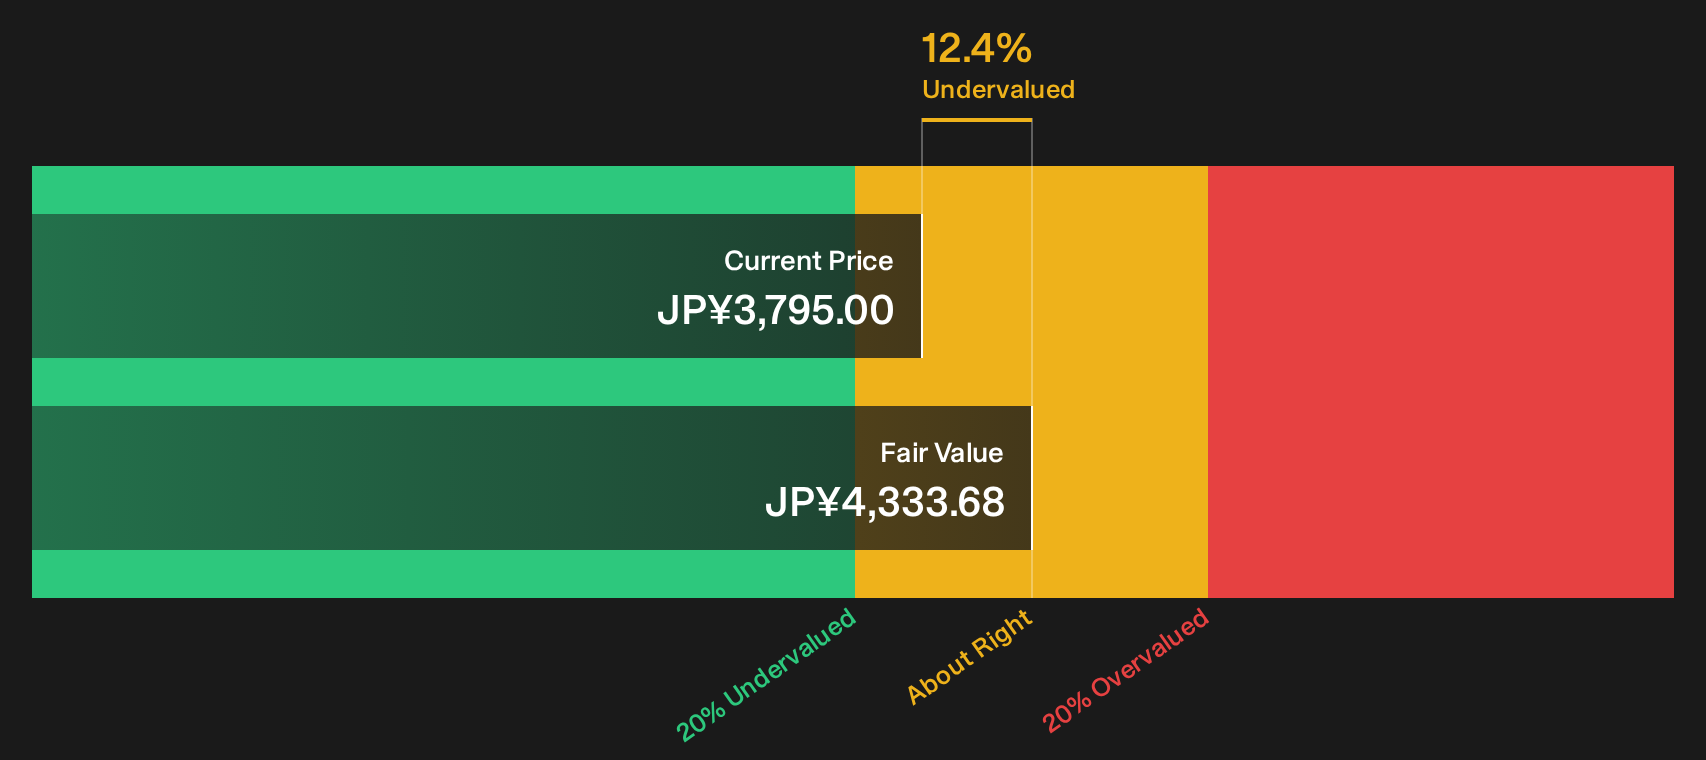
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nippon Densetsu Kogyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 24 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Nippon Densetsu Kogyo leave you torn, that is the point to start doing your own homework rather than waiting. Move fast, weigh both sides of the story, and ground your view in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nippon Densetsu Kogyo?
If Nippon Densetsu Kogyo has sharpened your focus on opportunities, do not stop here. Broader markets will move with or without you, so line up the next candidates now.
- Target potential mispricing and line up candidates that might offer more value by scanning the 24 high quality undervalued stocks before they draw wider attention.
- Strengthen portfolio resilience and reduce gut check moments by focusing on a 19 resilient stocks with low risk scores grounded in balance sheet and risk metrics.
- Hunt for future leaders early by tracking a 72 high quality undiscovered gems that couples quality fundamentals with limited current coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com