
NGK (TSE:5333) Looks Cheap On Half Year Results And Dividend Upgrade
NGK (TSE:5333) just paired a strong half year earnings update with a richer interim dividend, after reporting higher sales, net income and earnings per share, plus an uplift to its full year payout guidance.
NGK’s latest half year update arrives after a sharp share price pullback, with the 30 day share price return down 14.14% and the 90 day share price return down 19.51%, even though the year to date share price return is 41.55% and the 5 year total shareholder return is 192.10%. This means recent weakness comes against a strong longer term performance backdrop that this earnings and dividend reset may now be starting to test.
Spot fresh ideas with a similar earnings and dividend reset story by scanning our hand picked 29 dividend fortresses that balance income potential with business resilience.NGK now has stronger earnings and a richer dividend plan on the table, while the share price has pulled back significantly. Does that add up to a solid business still offered at a sensible valuation today?
Preferred Price-to-Earnings of 14.1x: Is it justified?
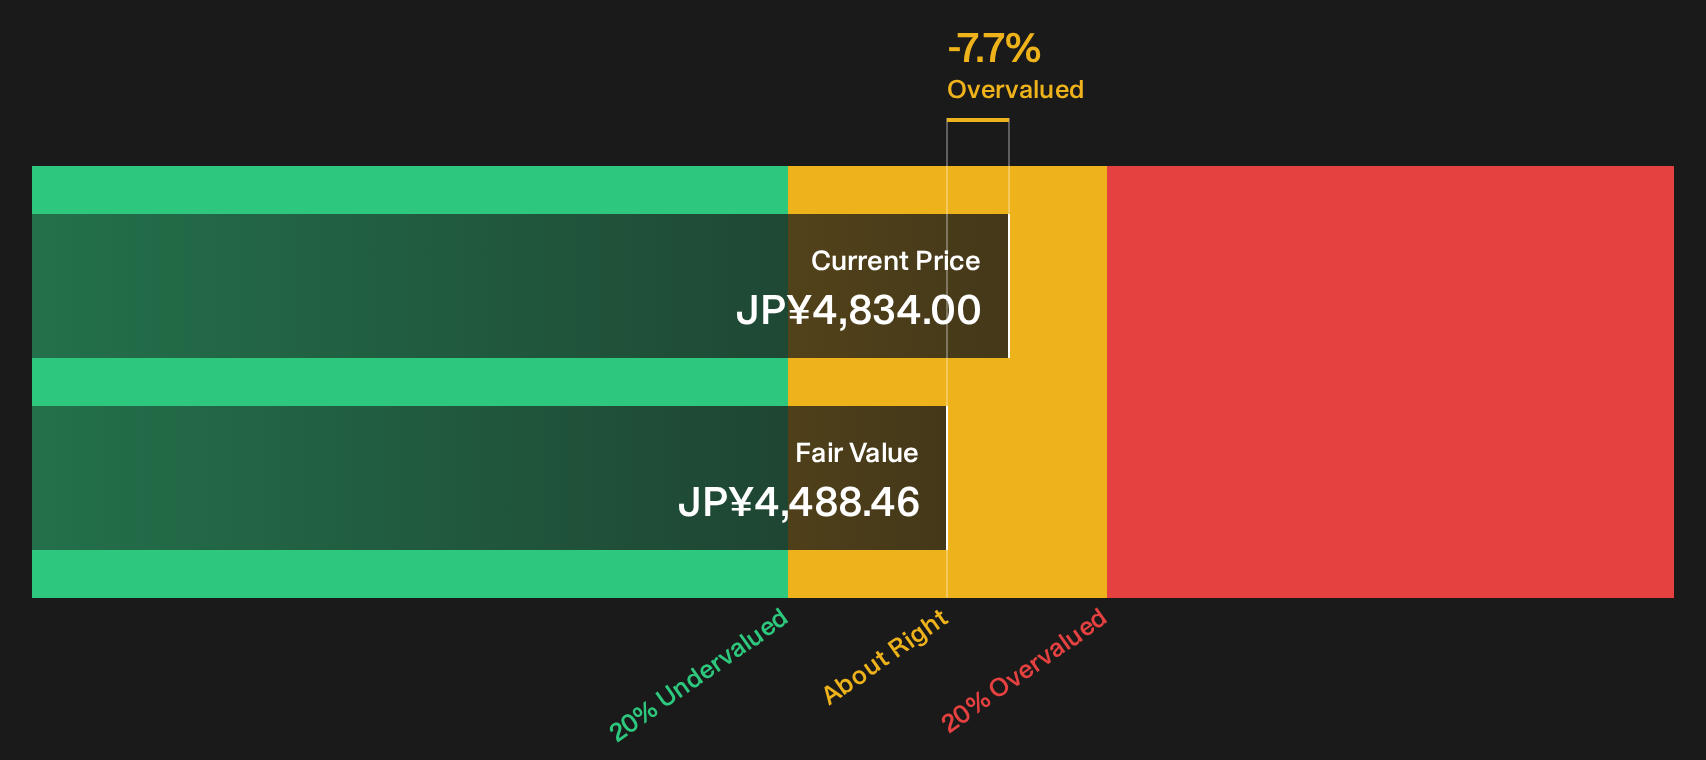
NGK closed at ¥4,834, and on a P/E of 14.1x it is being valued more cheaply than peers that trade on 17.2x earnings, even though Simply Wall St’s DCF estimate of future cash flows sits slightly lower at ¥4,488.46 per share.
The P/E ratio compares what you pay for each ¥1 of current earnings. For a manufacturer like NGK that already has meaningful profits on the board, this lens speaks directly to what the market is willing to pay for its earnings stream today.
Right now the stock trades on a lower P/E than both the peer average of 17.2x and the platform’s estimated fair P/E of 16.4x. That points to a market that is pricing NGK’s recent 83% earnings growth and 13.5% net margin level more cautiously than those benchmarks, even though both comparisons suggest room for the valuation multiple to move higher if results stay on track.
Compared with the broader JP Machinery group on 12x, NGK carries a premium that signals investors are already paying up a little for its earnings quality and track record of profit expansion. Yet against the 16.4x fair P/E estimate, the current 14.1x still looks restrained, which highlights a gap that could close if the market gains more confidence in the durability of its earnings profile.
Explore the SWS fair ratio for NGK.
Result: Preferred multiple of price-to-earnings of 14.1x (UNDERVALUED)
Still, the sharp 19.51% 90 day share price decline and NGK’s exposure to cyclical end markets could quickly challenge any thesis built purely around valuation.
Find out about the key risks to this NGK narrative.
Another View on NGK’s Value
On earnings, NGK looks inexpensive. On cash flows, the picture tilts the other way. At ¥4,834, our DCF model points to a future cash flow value of ¥4,488.46 per share, which flags the stock as slightly overvalued and raises a practical question: Is the recent earnings surge fully backed by long run cash generation?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NGK for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 24 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around NGK is clearly mixed, with fresh earnings strength set against valuation questions and a recent share price slide that still follows strong multi year gains. If that tension makes you curious rather than comfortable, pull up the charts, read the filings and weigh both the upside potential and the pressure points before making a call, then round out your view by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond NGK?
If NGK has sharpened your focus on valuation and income, do not stop here. The broader market still holds plenty of potential candidates worth your attention.
- Target resilience first by filtering for businesses with stronger finances using our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced opportunities by running a screen built around 24 high quality undervalued stocks.
- Build an income focused watchlist by zeroing in on our hand picked 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com