
Mercury Systems (MRCY) Stock Could Be Overvalued As Earnings Guidance Rises
Mercury Systems has delivered a strong run in recent years, and the stock now trades at a level where the key issue is whether that price lines up with its sales base. With investors paying close attention to recent news and changing expectations, the question is how much of the business's revenue story is already reflected in the current valuation.
- Over the past 3 years the share price has climbed 140.9%, which puts a lot of weight on whether the underlying sales can carry that kind of move.
- Recent updates around record bookings, higher margins and expectations for revenue approaching US$1.1b suggest the sales and earnings profile may support different assumptions about what the stock should be worth.
- Your read on Mercury Systems is one view; the desks covering it have another. See what analysts think Mercury Systems's shares could be worth.
For investors, the debate is whether Mercury Systems' current share price is justified by its sales when set against the Fair Ratio benchmark.
To see how Mercury Systems' sales-based valuation compares with other opportunities built on similar criteria, compare it with the 35 high quality undervalued stocks.
Has Mercury Systems Run Too Far on Sales?
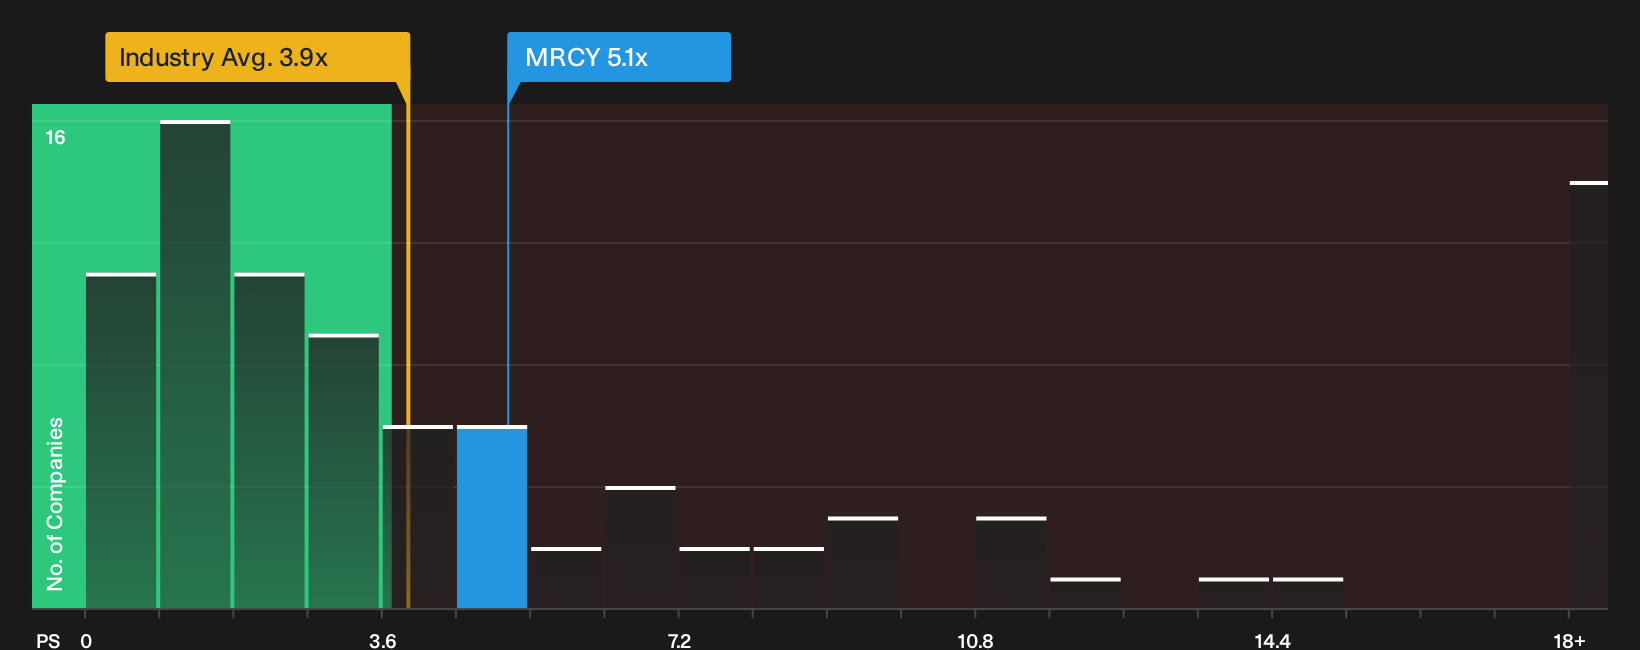
The P/S multiple fits Mercury Systems because management commentary and investor focus are squarely on the revenue line. On this measure, the stock trades on a P/S of about 5.1x, which is higher than the Aerospace & Defense group on roughly 3.9x and also above the peer set near 4.7x.
Because the Fair Ratio framework blends Mercury Systems' margins, growth profile, size and risk into a tailored benchmark, the current P/S points to an overvalued outcome on that yardstick. Despite the recent guidance lift toward revenue approaching US$1.1b, the market is already attaching a premium sales multiple relative to both sector norms and similar businesses, so any further upside case rests on how confidently you view those revenue and margin ambitions. Explore the numbers behind Mercury Systems's P/S valuation.
The Mercury Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Mercury Systems valuation question leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the stock to look materially higher or lower than it does today on the screen. Rather than one headline multiple or a single model result, each narrative lays out the moving parts behind its view of fair value so you can check those assumptions against the company’s reported numbers over time on Simply Wall St's Community page.
The bullish and bearish Narratives on Mercury Systems both lean on the same backlog and capacity story, yet they read that evidence very differently.
Bull case: 23% undervalued
The analyst consensus Narrative on Simply Wall St leans on the size and quality of Mercury Systems’ order book and operational upgrades.
"Growth in backlog and bookings across U.S. defense primes, including record quarterly bookings of about US$660 million and a total backlog above US$1.9b with next 12 month backlog of about US$1b, supports the view that Mercury Systems has multi year production already lined up that can feed future revenue and earnings…"
Discover why this Narrative puts Mercury Systems at 23% undervalued.
Bear case: 5% overvalued
The bearish analyst Narrative on Simply Wall St focuses less on orders and more on how reliably Mercury Systems turns that work into profit and cash.
"The numbers imply that Mercury Systems’ share price already reflects caution around its mixed long-term track record and recent pressure on gross margin and free cash flow, despite the current growth in bookings, backlog and EBITDA…"
Explore why this Narrative puts Mercury Systems at 5% overvalued.
One more Mercury Systems check that sits outside the sales story
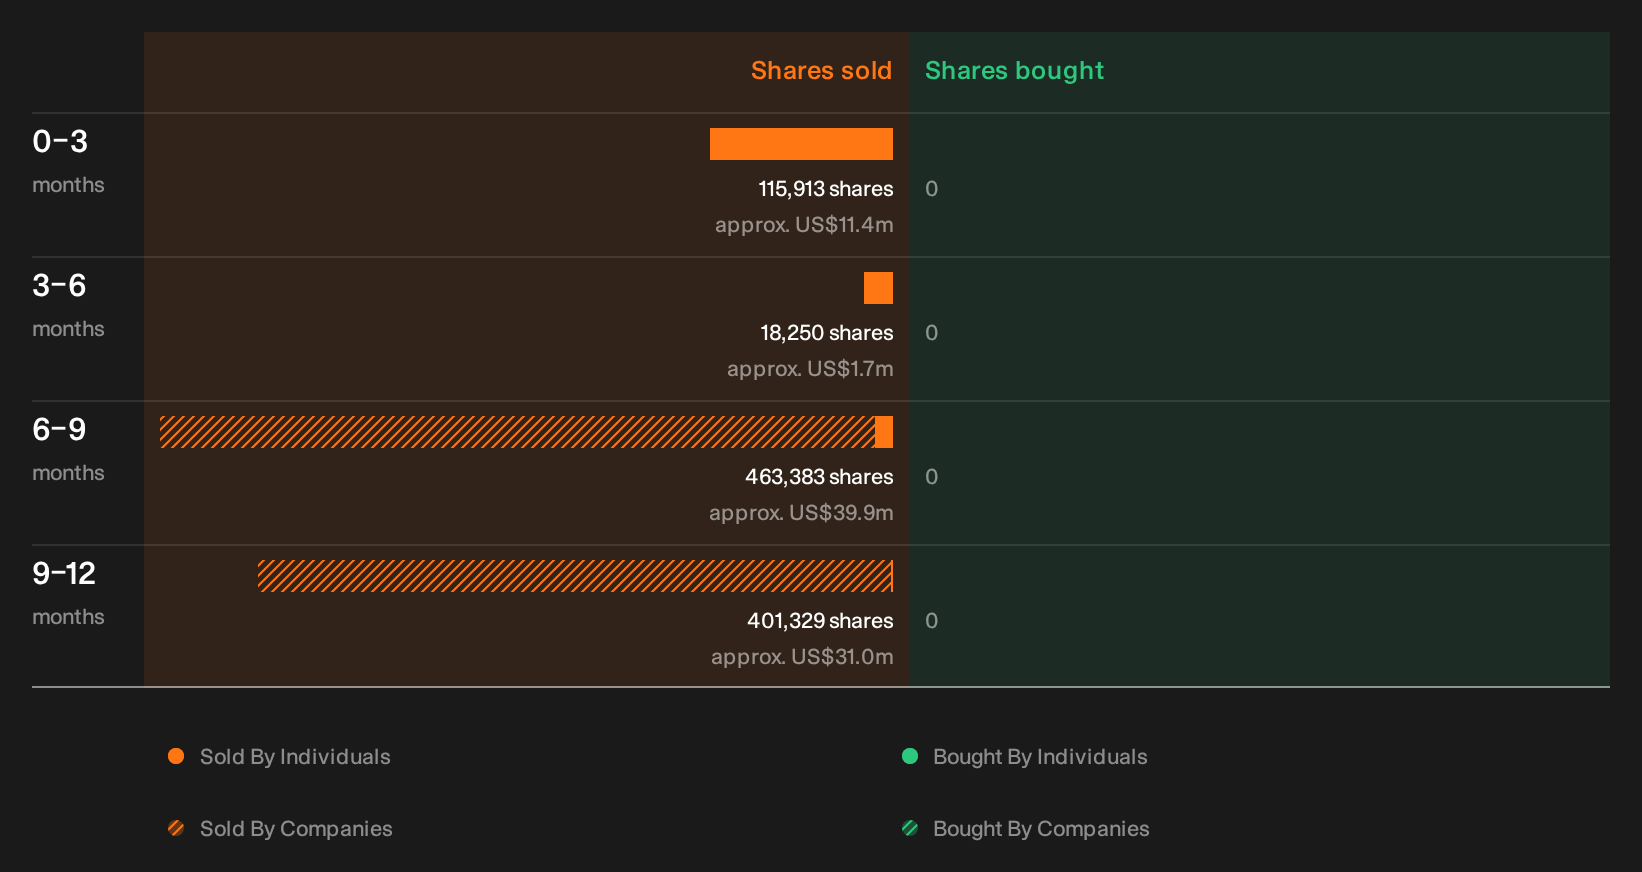
Price, revenue and backlogs tell only part of the Mercury Systems picture. Recent trading in the stock by company insiders has also been flagged by our checks, with the sellers, transaction sizes and possible read throughs still for you to review. See the recent insider selling flagged for Mercury Systems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com