
ArcBest (ARCB) Stock Looks Expensive Given Its Current Earnings
ArcBest has more than doubled over the past year, and with the stock around US$133.85 the obvious question is whether that climb is supported by the company’s earnings power. After a run like that, the key issue for you is whether the current market valuation still lines up with what the business is actually generating in profit.
- The share price is up 104.9% over the past year, which puts real pressure on the earnings story to justify where ArcBest now trades.
- Recent profit and tonnage updates, including higher contract rates and heavier freight, can influence how investors think about the durability and timing of future earnings.
- Your read on ArcBest is one view; the desks covering it have another. See what analysts think ArcBest's shares could be worth.
For investors, the debate is whether ArcBest’s current price is still reasonable when judged purely against the earnings the business is producing today.
If you want more ideas alongside ArcBest for this kind of earnings driven story, try a focused screen of 35 high quality undervalued stocks.
Is ArcBest Getting Expensive on Earnings?
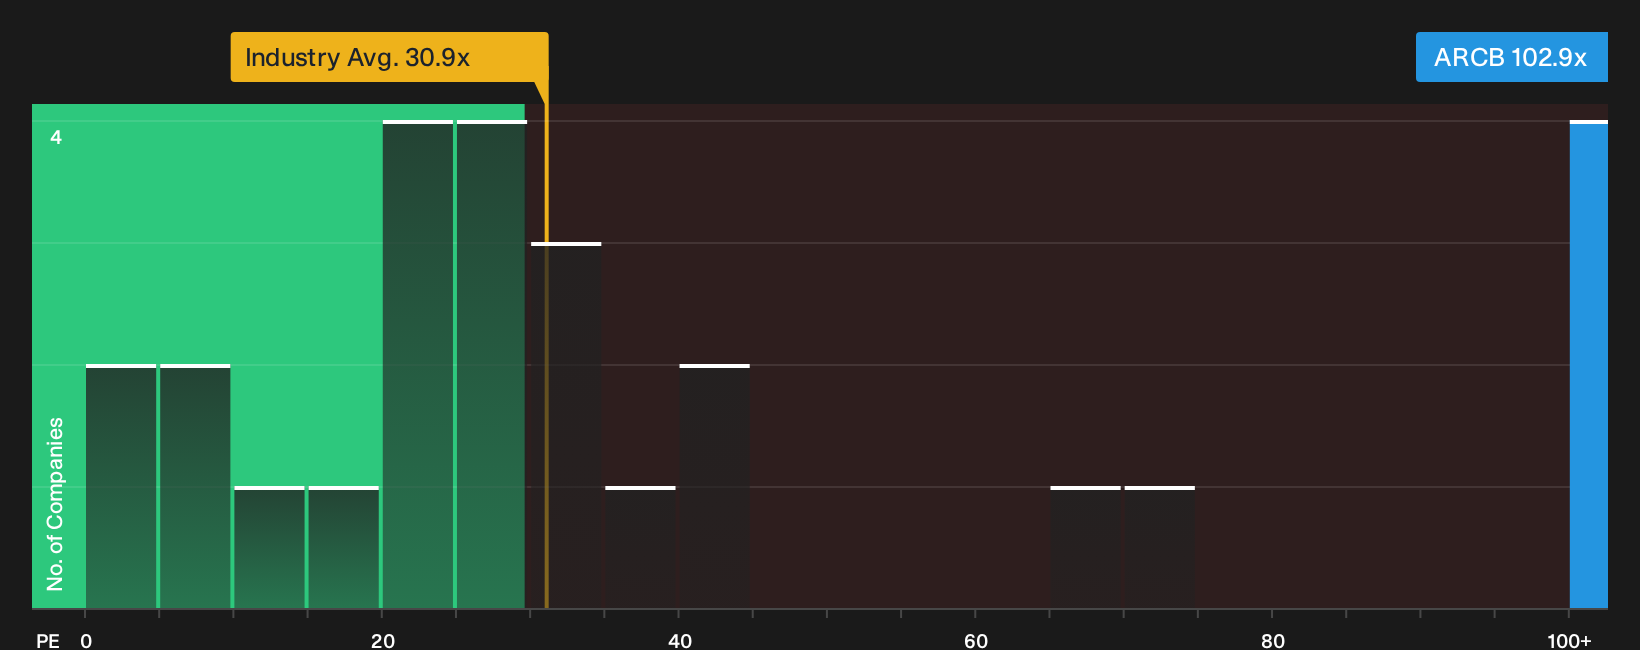
The P/E ratio is a useful lens for ArcBest because earnings sit at the center of how investors frame this stock. On this measure, the shares change hands at about 102.9x, which is roughly double the 51.5x peer average and far above the broader Transportation sector on 30.9x. That gap indicates that buyers are paying a steep premium for each dollar of profit compared with similar businesses.
On top of the recent Q3 earnings beat and solid tonnage update, the Fair Ratio model, which blends factors like sector, margins, size and risk profile, points to a materially lower multiple than where ArcBest trades today. As a result, the current P/E screens as overvalued against that more tailored yardstick. The valuation now reflects a high degree of optimism that recent contract wins and freight trends can translate into sustained profitability, which raises the bar for what future results need to deliver to keep this earnings multiple intact. Explore the numbers behind ArcBest's P/E valuation.
The ArcBest Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ArcBest pick up where this valuation puzzle leaves off. They spell out which future paths for ArcBest's growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than the current price. Each narrative ties its number to a specific view on how growth, profitability and risk might evolve that you can test again when new information lands.
One of the top narratives on ArcBest: 21% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Ongoing network and cost-structure optimization, including terminal rationalization, brand consolidation and workforce reductions that are expected to reach about US$40 million in annualized savings..."
Discover why this Narrative puts ArcBest at 21% undervalued.
One more ArcBest puzzle that could shift how you see the stock
There is another question to put next to today’s P/E and profit story. Professional forecasts sketch out where ArcBest might be a few years from now, and that pathway can sharply reframe how you judge today’s pricing. Explore where analysts expect ArcBest to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com