
What NICE (TASE:NICE)'s Earnings Miss Means For Shareholders
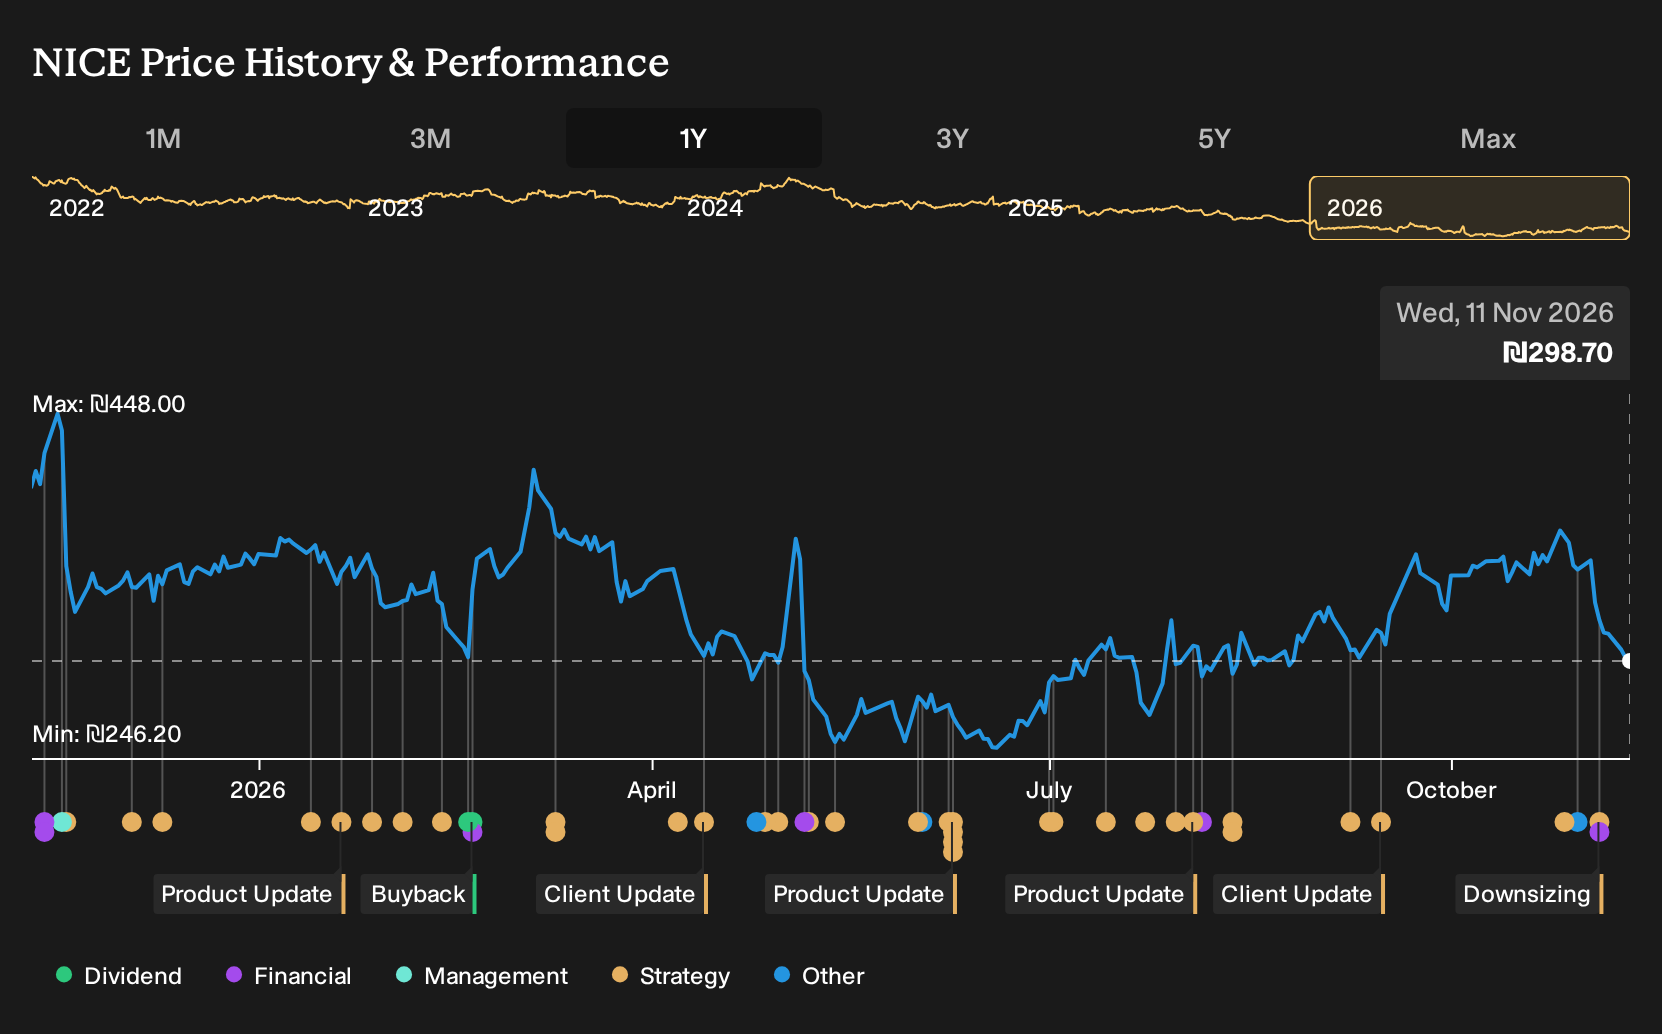
- NICE reported Q3 2026 revenue of US$790.74 million compared to US$732 million a year earlier, alongside lower net income and EPS, and announced a roughly 5% global workforce reduction with expected restructuring charges of US$15 million to US$20 million.
- The combination of higher sales, compressed earnings and a leaner structure suggests NICE is responding to cost pressures while still prioritizing CX AI, customer delivery and partner driven go to market efforts.
- We will now look at how NICE's investment narrative could be affected by the earnings miss on net income and the announced restructuring.
Scan how other CX and AI focused businesses are handling similar earnings pressure and restructuring moves by reviewing our hand picked 42 profitable AI stocks that aren't just burning cash with stronger profitability profiles and disciplined spending.
NICE Investment Narrative Recap
To own NICE, you need to be comfortable with a CX AI driven story where higher spending and complexity today are intended to support a larger cloud and AI footprint over time. The latest quarter shows that tension clearly, with revenue at US$790.74 million alongside weaker net income and lower EPS.
The workforce reduction and restructuring charges point to management trying to protect profitability while still funding CX AI, customer delivery and partner efforts. The most important near term swing factor is whether these changes stabilize margins without disrupting execution. The key risk is that margin pressure and churn persist despite the leaner setup.
The analyst consensus narrative on Simply Wall St focuses on AI and self service ARR momentum, cloud migration and big tech partnerships as the main return drivers. The Q3 earnings miss on profit complicates that story because it highlights how much net income can lag when spending tied to those themes stays high.
That same framework also highlights margin pressure, integration issues and dependency on partners as central threats. NICE’s decision to streamline management layers and cut roughly 5% of staff sits in the middle of that debate, because it directly targets efficiency at the same time that AI regulation, hyperscaler power and long deal cycles remain live execution risks.
NICE Forecasts and What Needs To Happen
NICE's current earnings are estimated at US$529.6 million, and analyst consensus points to earnings of US$638.7 million by 2029. This implies an increase of about US$109 million in profit. The same analyst set expects revenue to compound at roughly 9.8% per year over the next 3 years, leading to forecast sales of US$4.0 billion and earnings of US$638.7 million by 2029.
Uncover why NICE's fair value points to a 108% potential upside to its current price, which could narrow quickly as expectations reset.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$621 and US$700 per share, which shows how tightly some retail investors group their numbers, even before the latest NICE restructuring news. Set that against ongoing earnings pressure and workforce cuts, and you get a reminder that opinions can differ widely. It makes sense to compare several viewpoints before deciding how NICE fits in your portfolio.
Explore another NICE fair value estimate, including one that suggests it could be worth just ₪620.96!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your NICE research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NICE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NICE's overall financial health at a glance.
Looking For More Investment Ideas Beyond NICE?
If NICE sits on your watchlist already, you might consider balancing that single CX AI story with other companies that have different risk and income profiles.
- For investors hunting for potential mispricing, scan our 201 high quality undervalued stocks that pair solid fundamentals with more modest market expectations.
- If capital preservation and steadier price moves matter most to you, filter for 209 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- When you want quality first and prefer to avoid crowded trades, use the screener built around 563 high quality undiscovered gems with strong fundamentals that are still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com