
Power Test Expansion Might Change The Case For Investing In Keysight Stock (KEYS)
- Keysight Technologies recently expanded its high power automated test equipment portfolio, adding higher voltage options up to 1,500 volts and compact regenerative supplies up to 12 kilowatts to cover a wider range of power validation uses.
- The broader mix of power-stage, battery and aerospace focused systems, integrated with PathWave automation software, points to heavier integration of hardware and software in Keysight Technologies power test workflows, which can influence demand, as well as the quality and complexity of customer relationships.
- We will now assess how Keysight Technologies expanded 1,500 volt high power test platform could influence the company’s broader investment narrative.
Scan how Keysight Technologies fits into the broader test and measurement story by lining it up against 53 AI infrastructure stocks, which is powering the next wave of data centers and high performance compute.
Keysight Technologies Investment Narrative Recap
To own Keysight Technologies, you need to believe the test and measurement leader can keep leaning into AI data centers, 6G work, and aerospace and defense while shifting more of its mix toward software, simulation, and services. The analyst consensus Narrative on Simply Wall St ties that mix shift, along with Spirent integration, to earnings growth and high margins.
The latest high power test expansion fits that story but does not change the near term swing factors. The key short term catalyst is execution on AI infrastructure and high speed interconnect demand. The biggest near risk remains supply constraints and Spirent integration, which could affect both reported revenue timing and margin delivery.
Among the recent updates, the expanded high power automated test portfolio is closest to the core catalyst around AI data center and high speed power validation. Higher voltage coverage up to 1,500 V, higher current options, and regenerative supplies up to 12 kW give Keysight Technologies more tools to serve battery, EV charging, aerospace, and power conversion work.
Operationally, that widens the addressable test workload that can run on PathWave automation and related software. This ties into the push toward recurring revenue and simulation led workflows. It also increases the pressure on supply chain execution and manufacturing capacity at a time when about US$100m of revenue is already delayed by constraints, so delivery discipline matters as much as product breadth.
Keysight Technologies' narrative projects US$10.4b revenue and US$2.8b earnings by 2029. This assumes 16.5% yearly revenue growth and requires earnings to increase to a little more than double from US$1.3b today.
Uncover how Keysight Technologies' fair value indicates a 42% potential upside to its current price, which could narrow quickly if the story gains broader attention.
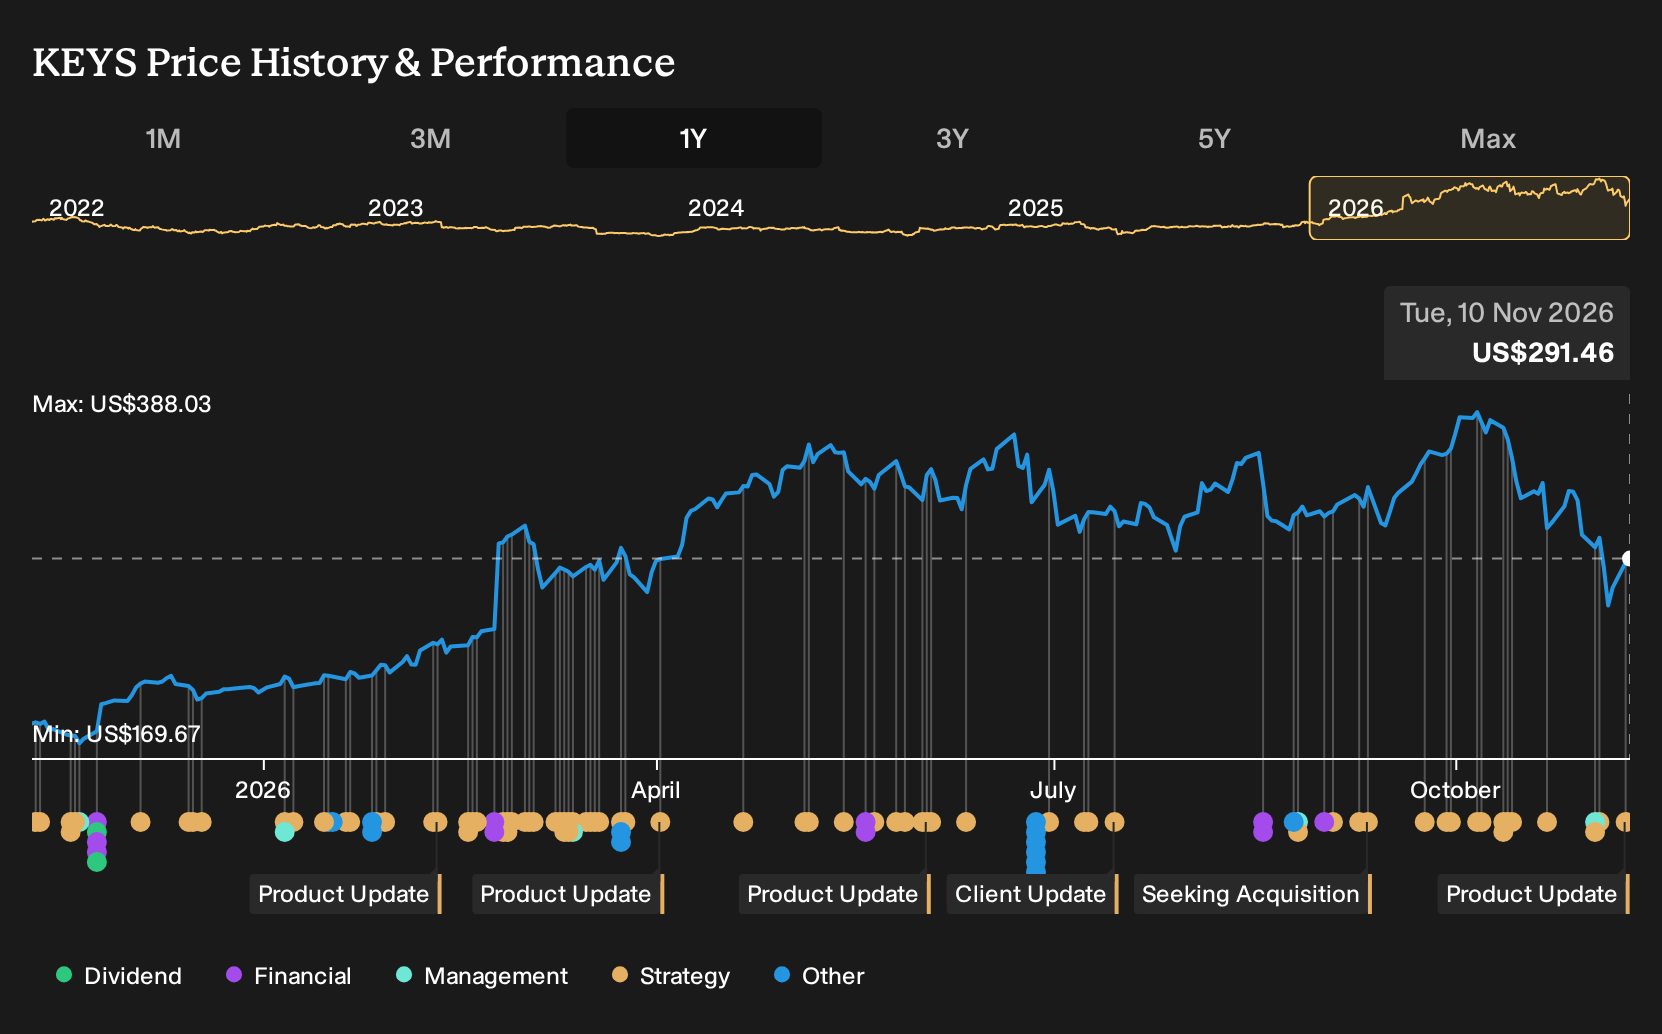
Exploring Other Perspectives
Some readers may focus on a different risk. The lowest analysts worry that AI driven test demand could slow, which is why they only model revenue reaching about US$9.3b and earnings of roughly US$2.7b by 2029. Those views were set before Keysight Technologies expanded its 1,500 volt platform, so expectations could shift.
Explore 2 other Keysight Technologies fair value estimates, including one that suggests it could be worth just $365.93!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis instead.
- A great starting point for your Keysight Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Keysight Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keysight Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Keysight Technologies?
If the Keysight Technologies story has sharpened your thinking, use that momentum and cast a wider net with the Simply Wall St Screener to spot other opportunities that match your risk profile and style.
- For investors who want potential upside with strict quality filters, shortlist companies that pass our high quality and value checks through the 35 high quality undervalued stocks.
- If capital preservation is front of mind, focus on businesses with steadier profiles by scanning the 30 resilient stocks with low risk scores that already clear tough risk hurdles.
- When you want financial strength to be the foundation of your watchlist, start with companies that show resilient balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com