
Will BrainChip Holdings (ASX:BRN) Spend Its Cash Wisely?
Just because a business does not make any money, does not mean that the stock will go down. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So should BrainChip Holdings (ASX:BRN) shareholders be worried about its cash burn? For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). Let's start with an examination of the business' cash, relative to its cash burn.
When Might BrainChip Holdings Run Out Of Money?
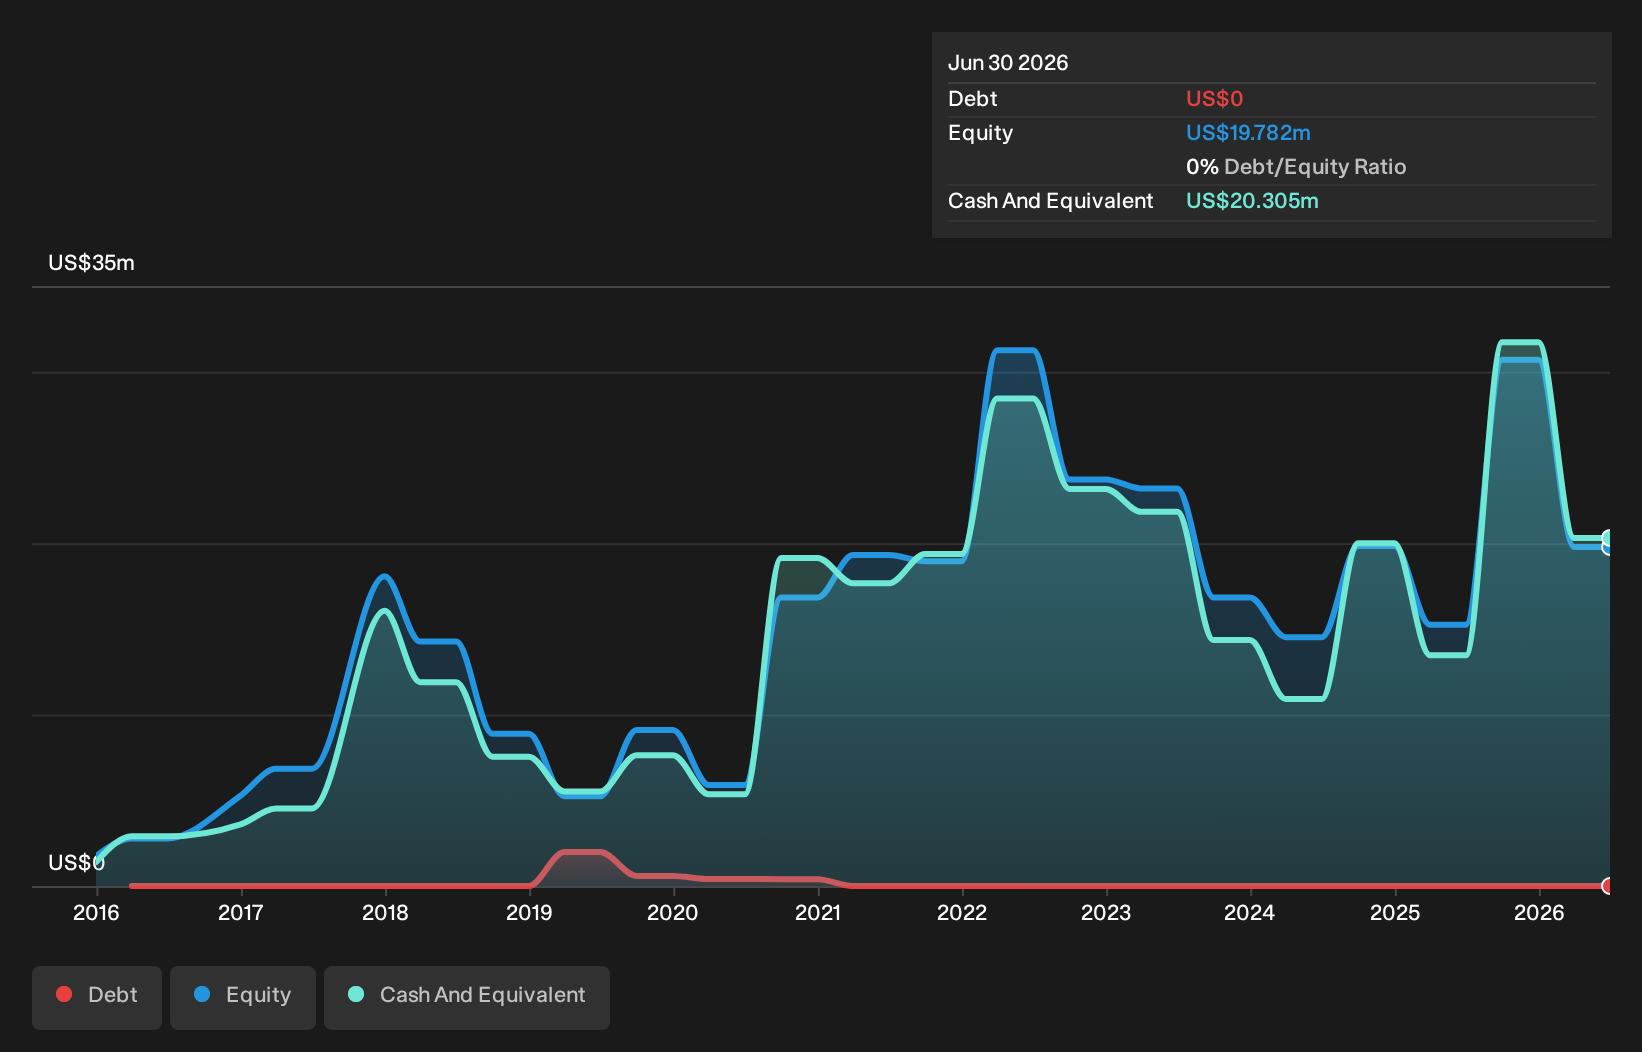
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at June 2026, BrainChip Holdings had cash of US$20m and no debt. Importantly, its cash burn was US$20m over the trailing twelve months. That means it had a cash runway of around 12 months as of June 2026. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. You can see how its cash balance has changed over time in the image below.
View our latest analysis for BrainChip Holdings
How Is BrainChip Holdings' Cash Burn Changing Over Time?
Whilst it's great to see that BrainChip Holdings has already begun generating revenue from operations, last year it only produced US$2.1m, so we don't think it is generating significant revenue, at this point. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. Over the last year its cash burn actually increased by 36%, which suggests that management are increasing investment in future growth, but not too quickly. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
Can BrainChip Holdings Raise More Cash Easily?
While BrainChip Holdings does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Companies can raise capital through either debt or equity. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
BrainChip Holdings has a market capitalisation of US$172m and burnt through US$20m last year, which is 12% of the company's market value. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
How Risky Is BrainChip Holdings' Cash Burn Situation?
On this analysis of BrainChip Holdings' cash burn, we think its cash burn relative to its market cap was reassuring, while its increasing cash burn has us a bit worried. Even though we don't think it has a problem with its cash burn, the analysis we've done in this article does suggest that shareholders should give some careful thought to the potential cost of raising more money in the future. Taking a deeper dive, we've spotted 4 warning signs for BrainChip Holdings you should be aware of, and 2 of them are potentially serious.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.