
Western Union (WU) Looks Fully Valued After Earnings And Revenue Guidance Reset
Western Union earnings and updated revenue outlook
Western Union (WU) has put fresh numbers on the table. Third quarter 2026 results showed softer profit, and management paired that update with new full year revenue guidance tied to its pending Intermex merger.
Western Union’s latest earnings update arrived during a period of share price volatility. The stock is up 11.0% on a 7 day share price return and 13.4% on a 30 day share price return. However, it remains down 24.8% on a year to date share price return and shows a weaker 5 year total shareholder return of 38.9%.
Scan Western Union’s peers facing similar earnings pressure and shifting guidance by reviewing our hand picked 35 high quality undervalued stocks, which combine resilient balance sheets with disciplined cash generation.
Western Union still runs a sizeable money transfer and consumer services operation, yet the share price slide and recent rebound pull the focus to something sharper. Is this a solid franchise being priced like a shrinking one?
Most Popular Narrative: 1% Overvalued
Western Union closed at $6.94 against an analyst consensus fair value of $6.88, and the analyst consensus Narrative on Simply Wall St frames that small gap through the lens of execution in digital, Consumer Services and cost savings under a 9.68% discount rate.
The accelerated Beyond Efficiency program, targeting US$50 million of run rate cost reductions by the end of 2026 and US$200 million by the end of 2027 through measures such as legacy product shutdowns, AI enabled productivity gains and regionalized operations, is aimed at offsetting pressure from the mix shift to lower margin digital, which could support operating margin and earnings if executed as planned.
See why 47 investors see Western Union as 1% overvalued.
Result: Fair Value of $6.88 (OVERVALUED)
Still, Western Union’s story can change quickly if regulatory pressure on key corridors worsens, or if lower margin digital volumes keep earnings under strain.
Find out about the key risks to this Western Union narrative.
Another view on Western Union’s valuation
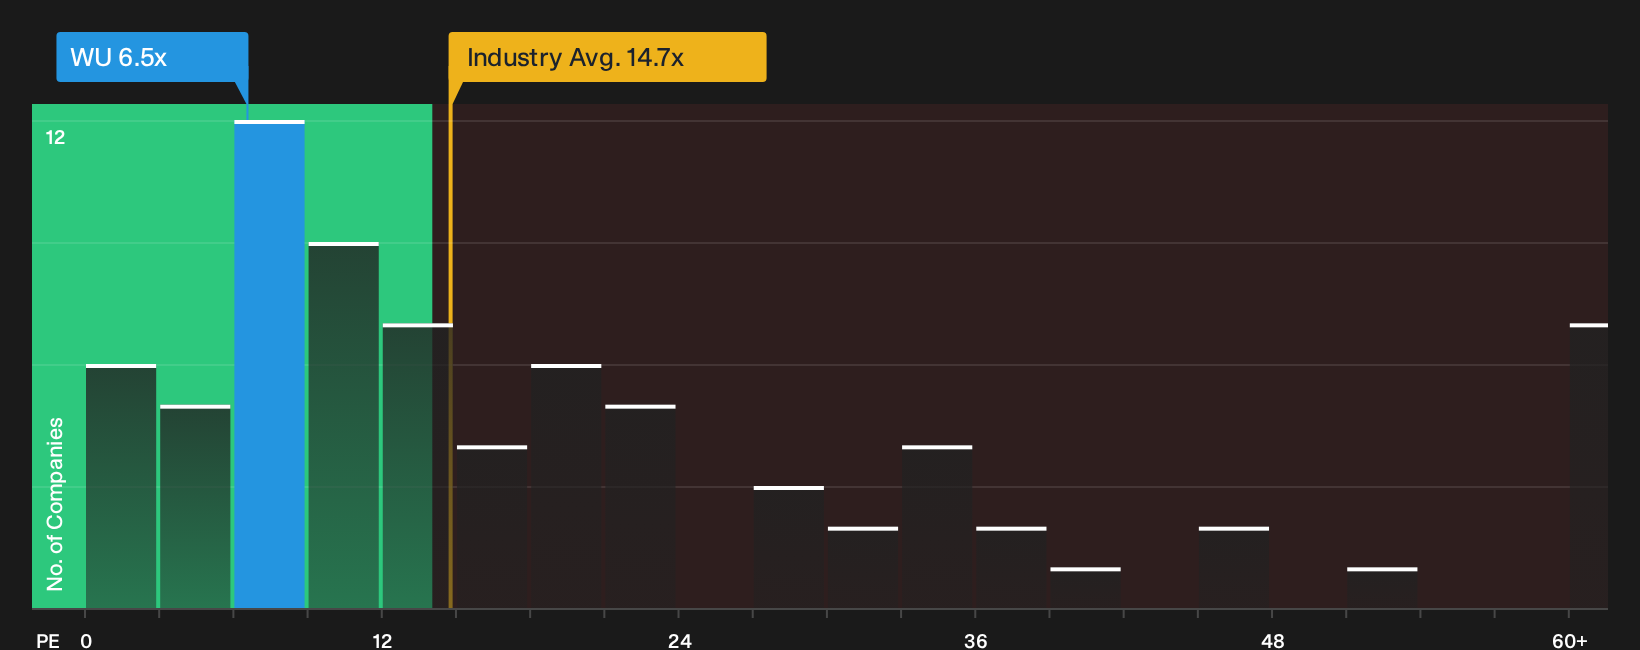
Analysts on Simply Wall St see Western Union as slightly overvalued at $6.94 against a $6.88 fair value, yet the current 6.5x P/E presents a very different picture. That multiple sits well below the US Diversified Financial industry on 14.7x and the stock’s own 12.1x fair ratio. For investors, the question is whether that gap reflects genuine risk or an opportunity waiting for clearer execution.
To see how this earnings multiple comparison ties back to Western Union’s fundamentals and where the ratio could move over time, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Western Union’s valuation and execution can feel messy, so consider acting promptly, reviewing the underlying data, and weighing both sides of the story for yourself by checking the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Western Union?
You have seen how Western Union is priced today, so do not stop here when the broader market may hold combinations of quality, income, and resilience worth your attention.
- Target fresh upside potential by scanning companies on our 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Prioritise staying power by reviewing companies in the list of solid balance sheet and fundamentals (24 results) that emphasise robust finances and consistent fundamentals.
- Build an income focused watchlist by checking out the 5 dividend fortresses that spotlight dividend payers with yields above 5%.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com