
Earnings Beat Could Be A Game Changer For OCBC Stock
- Oversea-Chinese Banking reported Q3 2026 net interest income of SGD 2,313 million and net income of SGD 2,042 million, with both metrics higher than the same period in 2025.
- For the first nine months of 2026, Oversea-Chinese Banking recorded SGD 6,237 million in net income and higher basic EPS than the prior year, indicating resilient profitability. This was reported alongside a £15 million 6.25% 2036 callable Eurobond issuance.
- We will now look at how Oversea-Chinese Banking's higher Q3 net income shapes the broader investment narrative around earnings quality.
Scan how Oversea-Chinese Banking's earnings profile compares with other resilient financials by reviewing our curated list of solid balance sheet and fundamentals (194 results).
Oversea-Chinese Banking Investment Narrative Recap
To own Oversea-Chinese Banking, you need to believe the bank can keep blending loan driven income with a growing wealth and insurance engine, while holding asset quality steady as rates and funding costs shift. The analyst consensus Narrative on Simply Wall St leans on earnings growth around the mid single digit range, supported by that mix.
The latest Q3 report, with Q3 2026 net income at SGD 2,042 million and nine month profit at SGD 6,237 million, reinforces that story rather than rewriting it. The near term swing factor still looks like net interest margin pressure against fee and insurance income, while softer wealth demand or weaker product take up remains the clearest risk.
The most relevant recent development to watch alongside these results is the £15 million 6.25% callable Eurobond due 2036. It adds another fixed coupon funding source in sterling, which can matter for how Oversea-Chinese Banking manages its currency mix, funding costs and duration profile across the group balance sheet.
For you as a shareholder, that bond sits in the background of bigger earnings catalysts such as wealth and insurance growth, digital productivity gains and the Indonesia build out. It still feeds into the same risk discussion. If wholesale funding stays relatively expensive while SORA and HIBOR remain soft, the margin squeeze highlighted in the analyst consensus Narrative on Simply Wall St remains an active concern.
Oversea-Chinese Banking's narrative projects SGD 18.4 billion revenue and SGD 9.6 billion earnings by 2029. This implies 7.7% yearly revenue growth and an earnings increase of about SGD 1.8 billion from SGD 7.8 billion today.
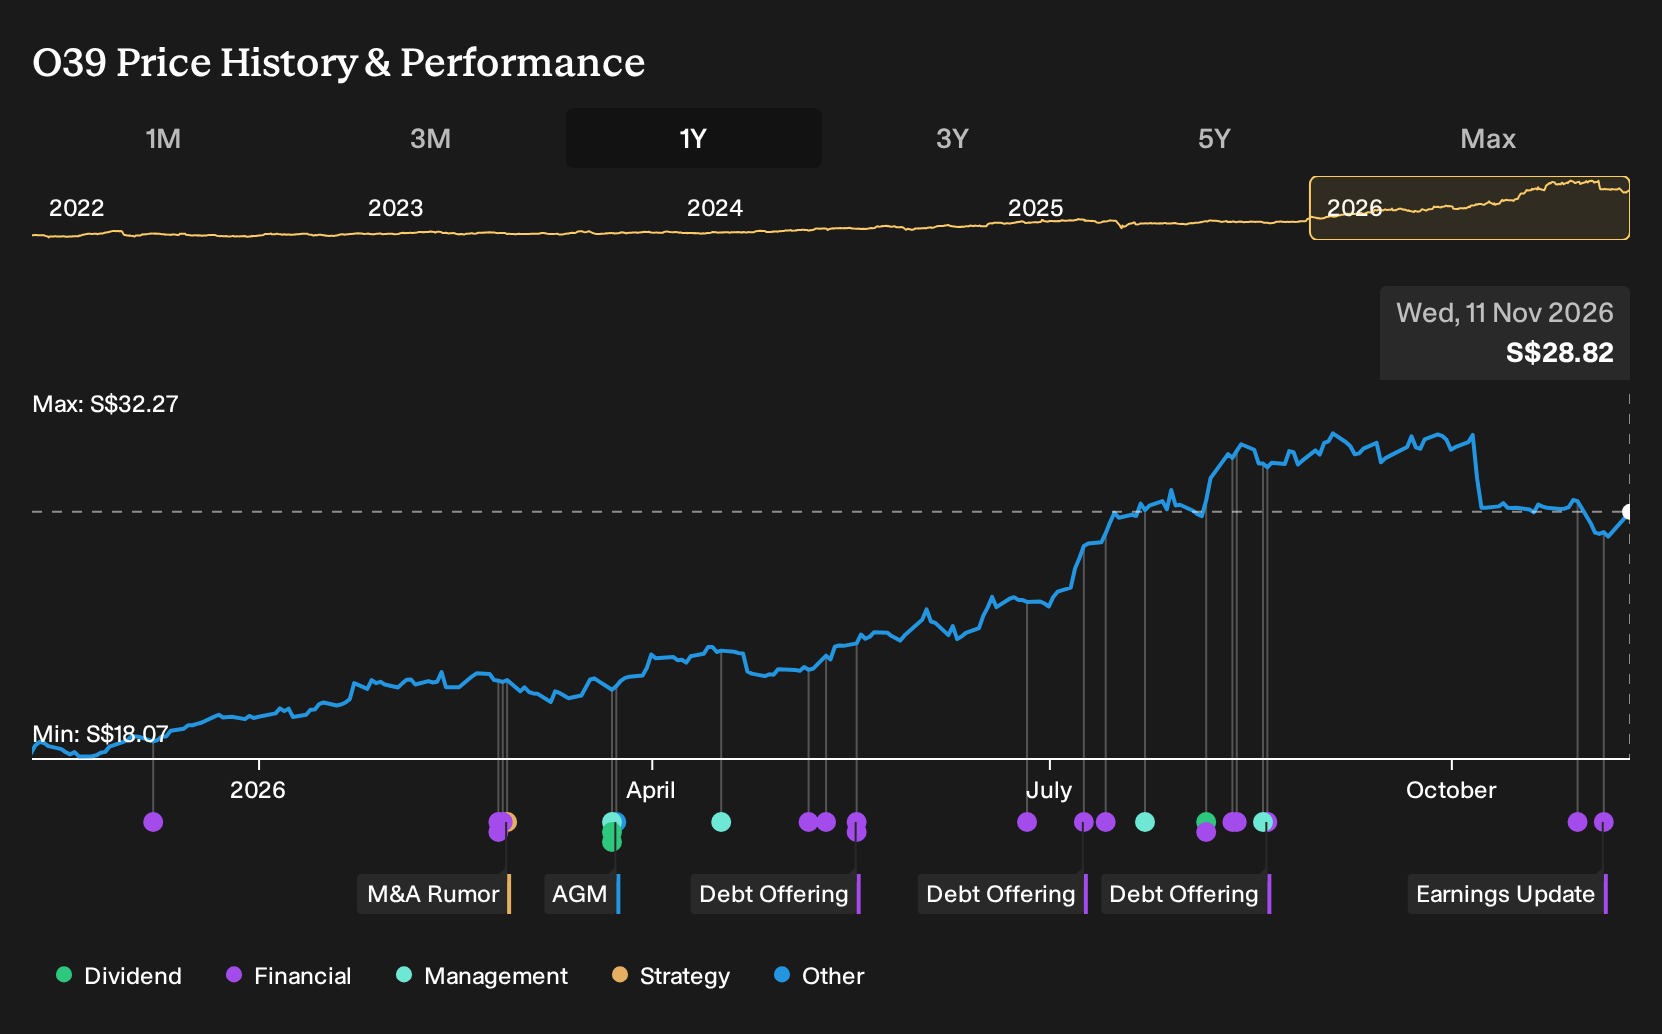
Uncover why Oversea-Chinese Banking's fair value indicates a 9% potential upside to its current price, a discount that could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts frame Oversea-Chinese Banking's AI and wealth push as the real story, not margin pressure. Before this Q3 print, that group was pencilling in revenue of about SGD 21.2b and earnings of SGD 10.9b by 2029. Your view on this fresh earnings call may shift how credible that sounds.
Explore 3 other Oversea-Chinese Banking fair value estimates, including one that suggests as much as 32% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Oversea-Chinese Banking research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Oversea-Chinese Banking. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oversea-Chinese Banking's overall financial health at a glance.
Looking For More Investment Ideas Beyond Oversea-Chinese Banking?
Once you have formed a view on Oversea-Chinese Banking, it can help to compare that thesis with other opportunities that fit different risk and income profiles using the Simply Wall St screener.
- For investors who want potential upside but still care about underlying quality, review our hand picked set of 563 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- If downside resilience matters more to you than chasing every rally, focus on a curated group of 208 resilient stocks with low risk scores designed to keep overall portfolio volatility in check.
- Income focused readers who value regular cash returns can scan a targeted pool of 219 dividend fortresses that combine higher yields with underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com