
Why Curtiss Wright (CW) Could Be 30% Undervalued On Q3 Beat And Contract Wins
Curtiss-Wright (CW) just paired stronger than expected Q3 2026 results with fresh defense contract wins worth more than US$365 million, a combination that has sharpened investor focus on the stock.
The recent pullback tells a different story to the contracts and Q3 beat. Curtiss-Wright’s share price has dropped about 7% over the past month and roughly 34% over the last quarter. However, the 3-year total shareholder return of about 124% and 5-year total shareholder return of roughly 274% still point to strong longer term compounding. This suggests current weakness reflects a reset in expectations and risk appetite rather than a collapse in the broader investment case.
Scan how Curtiss-Wright’s recent contract wins and guidance lift compare with other defense and industrial plays by reviewing a curated set of 30 resilient stocks with low risk scores in similar sectors.
The question now is whether Curtiss-Wright’s slide reflects something changing in the underlying business or mostly a reset in sentiment, and how that gap shows up in the current valuation setup.
Most Popular Narrative: 30% Undervalued
Curtiss-Wright’s last close at $477.92 sits well below the analyst consensus Narrative on Simply Wall St, which estimates fair value at about $681 using an 8.0% discount rate. That gap frames a story built around defense, nuclear and electronics demand, rather than short term share price moves.
Backlog and order visibility remain central to the thesis, with total orders up 12% year to date against 9% sales growth, a book to bill above 1.2x, and backlog at US$4.3b. Taken together with raised 2026 sales, margin, and EPS guidance, these factors can support the idea that current pricing undervalues the potential operating leverage into revenue and net margin over the next few years.
See why 17 investors see Curtiss-Wright as 30% undervalued.
Result: Fair Value of $681 (UNDERVALUED)
Still, the Curtiss-Wright narrative could be knocked off course if large defense or nuclear contracts are delayed, or if valuation concerns keep investors hesitant.
Find out about the key risks to this Curtiss-Wright narrative.
Another View on Curtiss-Wright’s Valuation
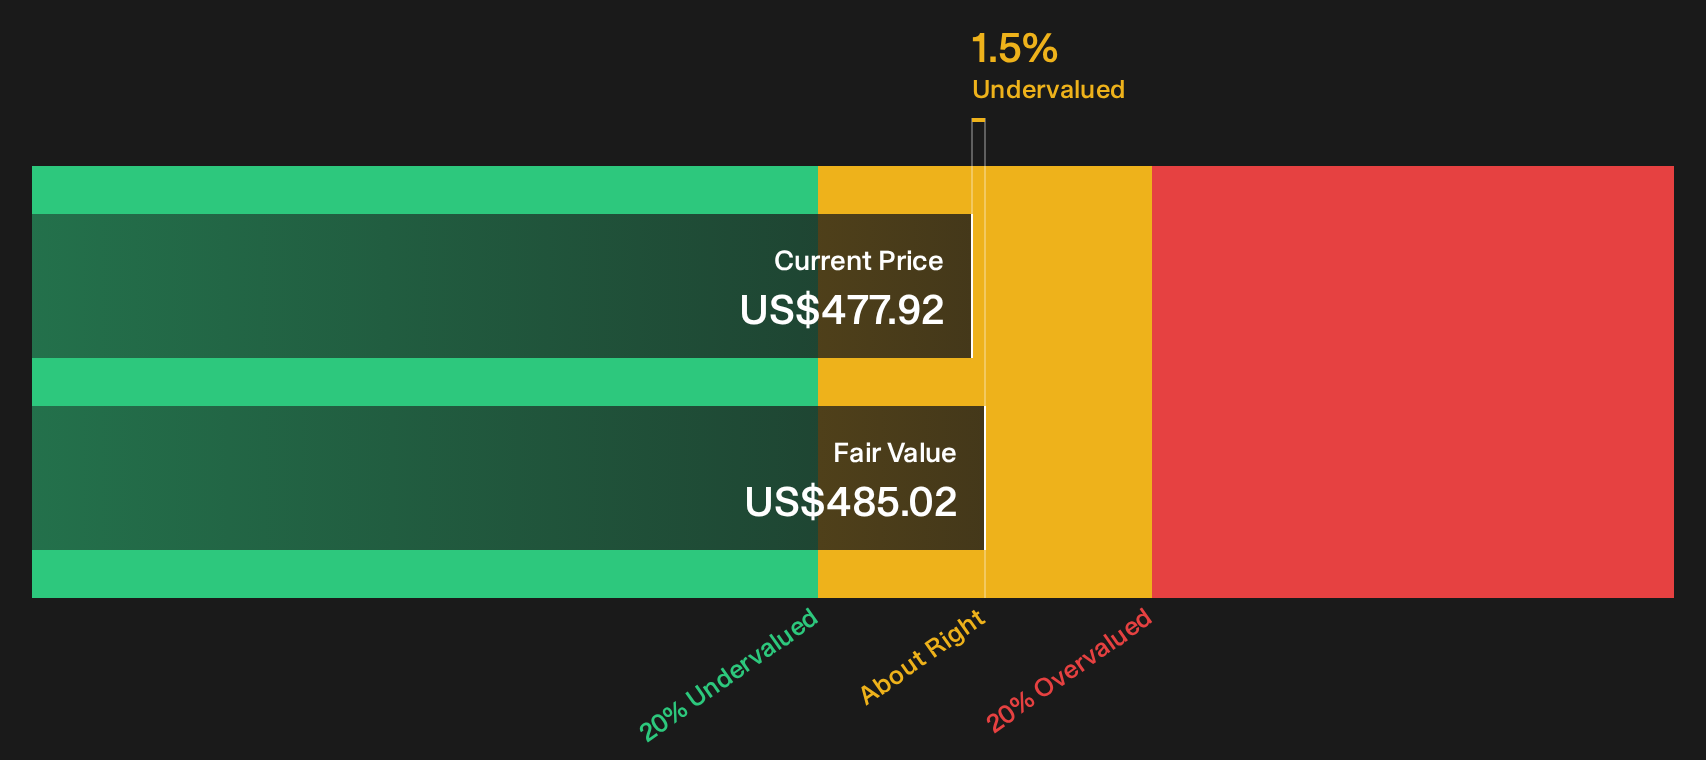
The Simply Wall St DCF model points to Curtiss-Wright trading only about 1.5% below its estimated future cash flow value of roughly $485, which implies the stock is close to fair value rather than deeply mispriced. If the cash flow view is this tight, it raises the question of how much weight to give to a 30% undervaluation narrative.
For investors who want to see exactly how that cash flow estimate is built up, it is worth walking through the full SWS DCF model step by step via Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mix of contracts, guidance and valuation debate around Curtiss-Wright leaves you unsure, act quickly and pressure test the numbers yourself using the 3 key rewards.
Looking for more investment ideas beyond Curtiss-Wright?
Do not stop with Curtiss-Wright. Broaden your watchlist now, compare different return profiles, and reduce the risk of missing opportunities that better fit your goals and risk limits.
- Target potential bargain opportunities by scanning companies that look cheaper than their fundamentals suggest through the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on reliable cash payouts with the 5 dividend fortresses.
- Prioritise resilience and capital protection by filtering for companies screened as relatively steady using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com