
Is Raiffeisen Bank International (WBAG:RBI) Fully Valued Following Strong Nine Month Results And NII Guidance?
Raiffeisen Bank International (WBAG:RBI) drew fresh attention on 3 November 2026 after issuing guidance for net interest income above €4.5b and reporting sharply higher nine month net income and earnings per share.
The latest guidance and nine month figures land after a powerful run in Raiffeisen Bank International’s shares, with the 1 year total shareholder return at 103.45% and the year to date share price return at 70.47%. This suggests momentum has been building rather than fading.
Spot similar momentum in other financials by scanning the hand picked 202 high quality undervalued stocks that also pair strong recent performance with balance sheet strength.After Raiffeisen Bank International’s rally and upgraded net interest income outlook above €4.5b, the key issue is simple: Does the current price still leave enough upside for the risk involved?
Most Popular Narrative: 8% Overvalued
Raiffeisen Bank International closed at €64.20 compared with the analyst consensus Narrative fair value of €59.68, which implies a modest premium based on that framework. The analyst consensus Narrative on Simply Wall St ties that gap directly to how earnings, loan growth and risk clean up are expected to play out over time.
The current valuation suggests the market already views Raiffeisen Bank International as fairly valued, with its capital, fee and FX franchises and ongoing digital and AI investment balanced against the remaining Russia related and litigation risks.
A key requirement is that Raiffeisen Bank International successfully executes its Russia exit and Polish FX mortgage clean up while integrating Garanti Romania and Addiko without eroding its strong capital position.
See why 22 investors see Raiffeisen Bank International as 8% overvalued.
Result: Fair Value of €59.68 (OVERVALUED)
Still, the Russia exit overhang and unpredictable Polish FX mortgage litigation mean Raiffeisen Bank International’s earnings and capital trajectory could yet face sharp detours.
Find out about the key risks to this Raiffeisen Bank International narrative.
Another View On Raiffeisen Bank International’s Valuation
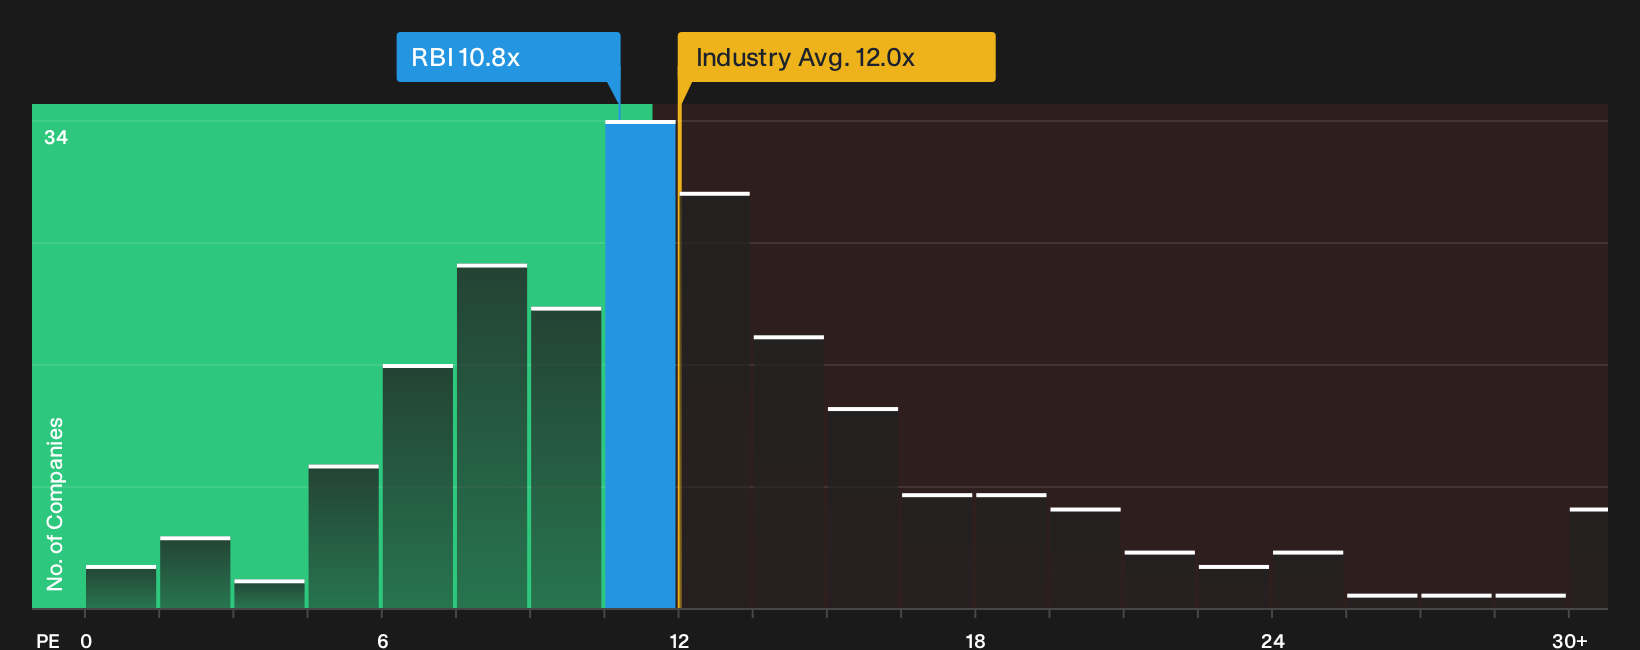
The analyst consensus narrative calls Raiffeisen Bank International about 8% overvalued at a fair value of €59.68, yet the shares trade on a P/E of 10.4x. That is lower than both the European banks average of 11.9x and the peer group at 15.3x. This points to a material discount on this simple earnings yardstick even though the fair ratio is also 10.4x. For anyone weighing these signals side by side, the key question is whether the earnings multiple eventually gravitates toward sector levels or the narrative fair value view pulls expectations back.
See what the numbers say about this price in more detail in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Raiffeisen Bank International in this piece is mixed, with both clear concerns and genuine optimism sitting side by side. Act quickly, review the underlying figures for yourself, and pressure test both angles against the 3 key rewards and 5 important warning signs 3 key rewards and 5 important warning signs
Looking for more ideas beyond Raiffeisen Bank International?
If you stop with Raiffeisen Bank International, you only see part of the opportunity set. Use the screener to spot fresh setups before everyone else does.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (194 results) to filter for financial strength first.
- Hunt for mispriced quality by reviewing the 563 high quality undiscovered gems that highlight under-the-radar businesses with strong underlying numbers.
- Reduce potential portfolio shocks by focusing on the 208 resilient stocks with low risk scores to tilt toward companies with more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com