
Lennar (LEN) Gains On FHA Proposal, Is It Still 11% Above Fair Value?
A proposed FHA program that would allow first-time buyers to secure a mortgage with just a US$1,000 down payment has sharpened attention on Lennar (LEN), particularly its entry level housing exposure.
Lennar shares have swung sharply around the FHA proposal and the recent refinancing moves, with a 30 day share price return of 13% building short term momentum, even as the year to date share price return is down 16.85% and the 1 year total shareholder return has declined 29.37%.
Scan beyond Lennar and compare it with other homebuilders and housing related stocks that score well on balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (24 results)
Lennar has bounced hard in a month yet is still carrying a double digit decline over the past year. Does the current valuation still offer a fair trade off between upside and downside from here?
Most Popular Narrative: 11% Overvalued
Lennar last closed at $86.66, while the analyst consensus Narrative on Simply Wall St places fair value at $77.87 using an 8.99% discount rate. This points to a meaningful premium that investors need to weigh against the underlying story.
The company's focus on driving consistent volume and production efficiency by matching production pace with sales pace is now supported by record construction cycle times of 116 days and tighter completed inventory. This can affect future gross margin and returns on inventory.
See why 46 investors see Lennar as 11% overvalued.
Result: Fair Value of $77.87 (OVERVALUED)
Still, the Lennar narrative depends on affordability remaining intact and on land and land banking costs not eroding the efficiency gains from faster build cycles.
Find out about the key risks to this Lennar narrative.
Another View: Lennar Through The P/E Lens
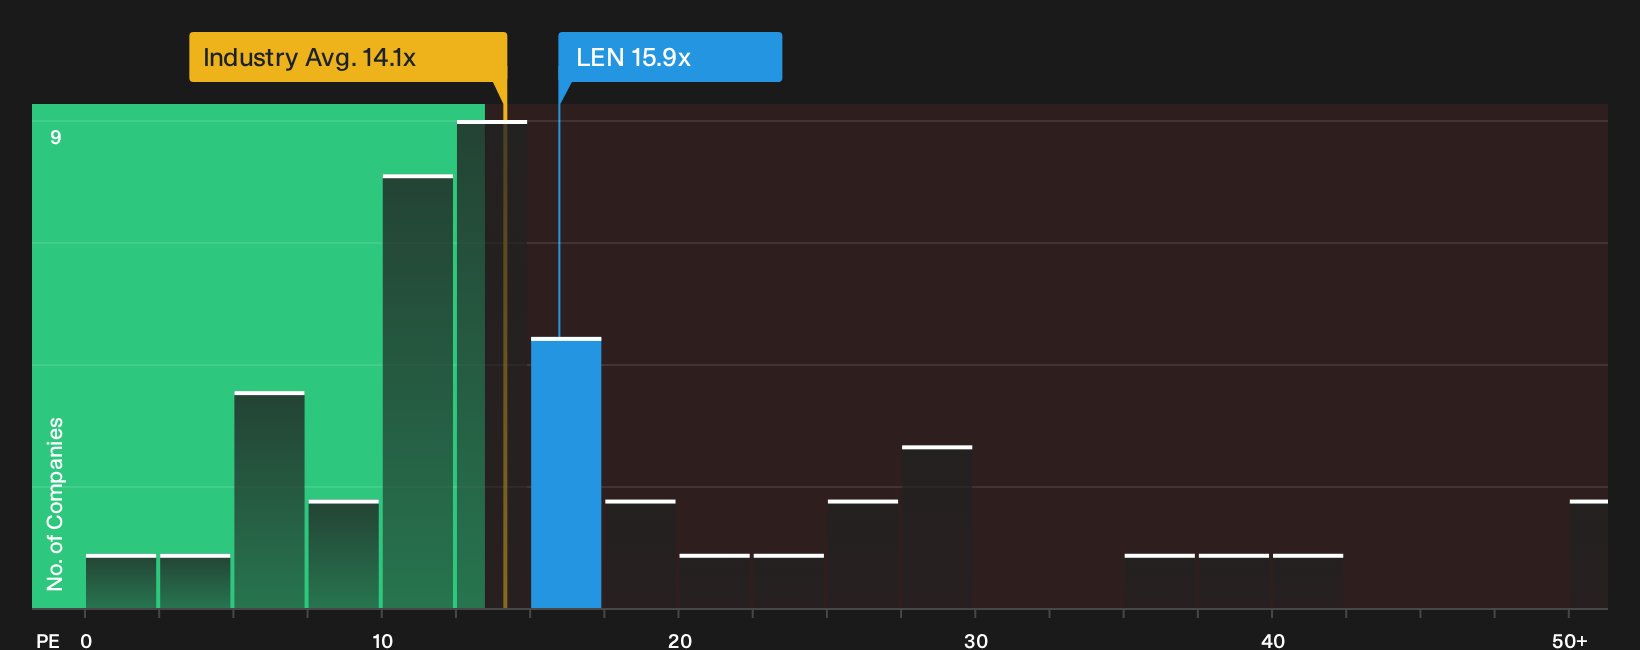
There is a twist when you value Lennar using plain earnings multiples instead of the narrative fair value. The stock trades on a P/E of 15.9x, which is higher than both the US Consumer Durables industry at 14.1x and peers at 13.6x, yet still below a fair ratio estimate of 24.2x.
That mix of richer pricing versus the sector and peers, but a gap to the fair ratio the market could move toward, points to real valuation risk if sentiment cools and potential upside if the story holds together. Which side of that trade do you think wins out over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views are clear around Lennar, and that kind of split opinion can move quickly as new data lands. Put the numbers in context for your own portfolio by weighing the 3 key rewards and 1 important warning sign.
Looking for more Lennar sized investment ideas?
Do not stop with Lennar. Broader opportunities often show up where you least expect them, and the right screen can surface them before they get crowded.
- Target resilient cash generators by scanning a 35 high quality undervalued stocks that combines quality fundamentals with pricing the market has not fully recognised yet.
- Lock in income potential by reviewing a curated 5 dividend fortresses focused on higher yielding companies with payouts that are built on solid financial footing.
- Prioritise peace of mind and capital protection by filtering for a 30 resilient stocks with low risk scores that aims to keep volatility and fundamental risk in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com