
How Investors May Respond To Zions Bank Stock Leading SBA Loan Approvals
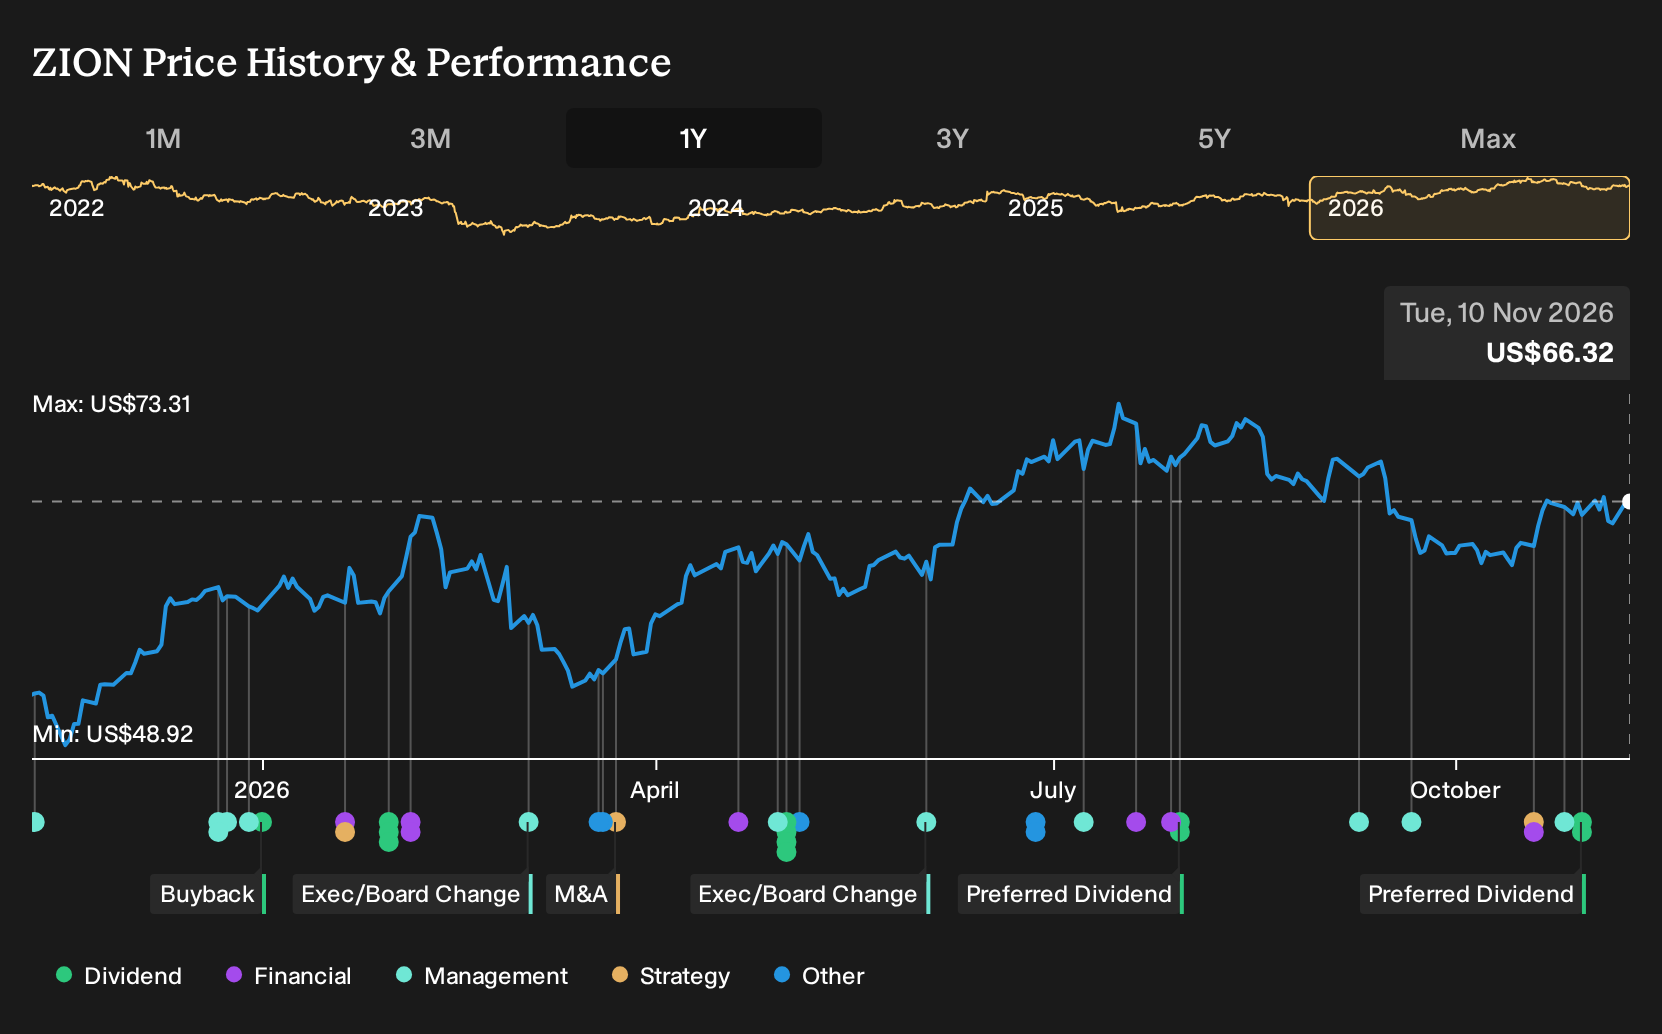
- Zions Bancorporation National Association recently declared regular quarterly dividends on both its common and Series A perpetual preferred shares, with payments scheduled in November and December 2026 to shareholders of record in mid November and early December.
- The bank also ranked No. 1 in SBA 7(a) loan approvals in the Boise and Utah districts, reflecting meaningful engagement with small and diverse business owners across its Intermountain West footprint.
- This analysis will consider how Zions Bancorporation National Association's SBA 7(a) lending leadership relates to the existing investment narrative around fee growth.
Compare Zions Bancorporation National Association's dividend and small business focus with curated banks and lenders in the list of solid balance sheet and fundamentals (24 results) that may offer similar income and credit exposure profiles.
Zions Bancorporation National Association Investment Narrative Recap
To own Zions Bancorporation National Association, you need to believe that its Western US franchise, fee businesses and tech investments can offset pressure on funding costs and the analyst consensus Narrative on Simply Wall St that points to declining earnings over the next few years. The near term swing factor is whether deposit competition tightens net interest margins or stays manageable.
The biggest operational risk still sits in regional concentration and any upward drift in credit costs if Western economies weaken, which could squeeze capital return flexibility. The latest dividend affirmations do not materially change that near term risk reward balance, although they do signal management confidence in current earnings and capital buffers.
The regular quarterly common dividend of US$0.48 per share, declared for payment on 19 November 2026, is the clearest new datapoint for income focused holders. For a bank flagged as paying a 2.9% dividend and trading on a single digit P/E, this decision ties directly into the income and valuation narrative already in focus for many shareholders.
The preferred dividend declaration on the Series A perpetual shares reinforces that Zions Bancorporation National Association is continuing its current capital return pattern while it leans into small business and fee growth catalysts. That consistency matters if analysts are expecting modest revenue expansion and earnings pressure, since reliable distributions can keep income oriented investors engaged even while operational execution remains under scrutiny.
Zions Bancorporation National Association is modeled to reach about US$3.8b in revenue and US$949.6 million in earnings by 2029, based on analyst estimates that incorporate roughly 1.3% yearly revenue growth and an earnings decline of about US$250 million from the current US$1.2b level.
Uncover why Zions Bancorporation National Association's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$73 to US$122, which shows how far opinions on Zions Bancorporation National Association can stretch. Set that against dependence on Western US credit trends and deposit competition, plus small business and fee growth catalysts, and you are looking at genuinely divergent paths. Explore those alternative viewpoints before deciding where you sit.
Explore 2 other Zions Bancorporation National Association fair value estimates, including one that suggests it could be worth just $72.64.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zions Bancorporation National Association research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zions Bancorporation National Association. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zions Bancorporation National Association's overall financial health at a glance.
Looking for more investment ideas beyond Zions Bancorporation National Association?
Once you have a handle on Zions Bancorporation National Association, it can help to widen the lens and compare its profile with other opportunities that match your income, quality, or risk preferences through the Simply Wall St Screener.
- If you want income at the center of your approach, scan for companies described as 5 dividend fortresses and see which payouts align with your tolerance for volatility.
- For investors who care most about balance sheet strength and resilient fundamentals, filter the screener using the list of solid balance sheet and fundamentals (24 results) to see which businesses clear your quality bar.
- Curious about potential mispriced opportunities with stronger fundamentals? Sort through the 20 high quality undiscovered gems and compare their profiles with what you see at Zions Bancorporation National Association.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com