
ESCO Technologies (ESE) Could Be 32% Undervalued Following Fourth Quarter Earnings Anticipation
ESCO Technologies (ESE) heads into its November 19 fourth quarter earnings release, with investors weighing an expected 6.5% revenue increase against consensus forecasts for an 11.6% decline in earnings per share.
Recent trading has cooled after a strong run. The share price has fallen 7.5% over the past month and 20.7% over the last 90 days, even though ESCO Technologies has delivered a 20.6% year to date share price gain and a 3 year total shareholder return of 127.6%. This suggests momentum has faded as investors reassess growth expectations and risk ahead of the earnings release.
Scan beyond ESCO Technologies and explore other industrials with earnings momentum shifts using our curated list of list of solid balance sheet and fundamentals (24 results)
After a 20.7% pullback from recent highs and a last close of US$238.38 against analyst targets and intrinsic estimates that sit materially higher, the key question is where fair value for ESCO Technologies really lies.
Most Popular Narrative: 32% Undervalued
On the analyst consensus Narrative on Simply Wall St, ESCO Technologies screens as undervalued, with a fair value of $352.75 against the last close at $238.38. That gap is rooted in a view that current earnings power and long term demand can support a higher valuation when discounted at 8.35%.
Record consolidated book to bill of 1.21 and backlog of US$1.54b, with all three segments above 1.0 book to bill, is cited as signaling multi quarter revenue support as ESCO Technologies converts existing orders to sales and earnings. The Megger acquisition, valued at about US$2.35b and expected to deliver about US$60m of cost synergies over three years at roughly 14x projected 2026 EBITDA, is described as increasing ESCO Technologies' exposure to utility customers and creating a larger electrical test platform that can support higher revenue and net margins as integration progresses.
See why 3 investors see ESCO Technologies as 32% undervalued.
Result: Fair Value of $352.75 (UNDERVALUED)
Still, the narrative around ESCO Technologies could shift quickly if Megger integration drags on or if weakness in the renewables focused NRG business persists longer than expected.
Find out about the key risks to this ESCO Technologies narrative.
Another View: What ESCO Technologies’ P/E Is Telling You
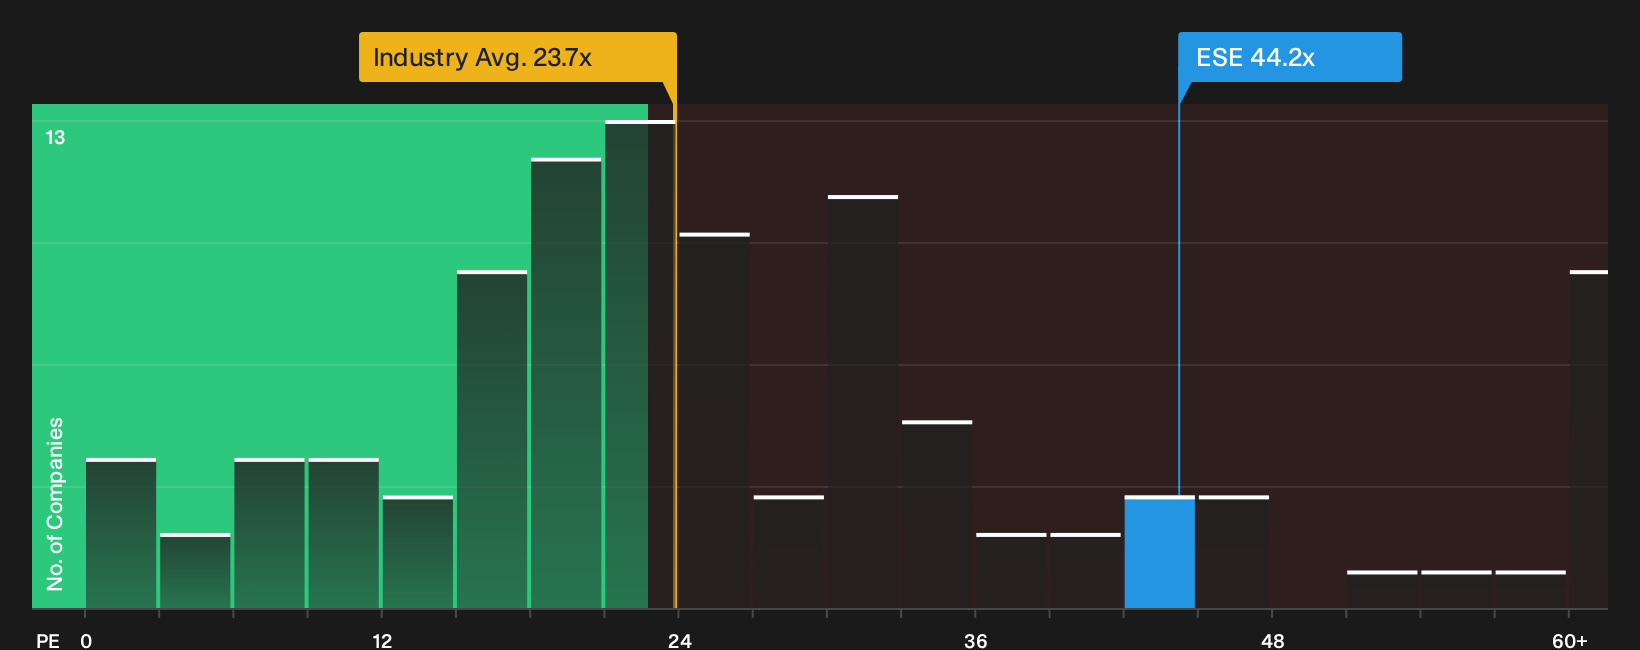
On a simple earnings multiple, ESCO Technologies screens as expensive. The stock trades on a P/E of 44.2x, compared with 24.1x for the US Machinery industry and 41.6x for its peer group, while the fair ratio is 29x. That gap points to valuation risk if expectations cool.
For a closer look at what this pricing gap could mean in practice, including how it might close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ESCO Technologies valuation and earnings expectations can create noise. Act while the data is fresh and assess the potential upside by reviewing the 4 key rewards.
Looking for more ESCO Technologies style investment ideas?
If ESCO Technologies has sharpened your focus on quality and timing, do not stop here. Broaden your watchlist now, or risk missing the next opportunity taking shape.
- Target resilient cash generators that trade below their implied worth through our curated set of 35 high quality undervalued stocks.
- Focus on potential income streams by concentrating on companies built to sustain payouts with the 5 dividend fortresses.
- Prioritize peace of mind by concentrating on financially sturdy businesses using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com