
3 Valuation Signals For Elemental Royalty (TSX:ELE) On Stronger Q3 Earnings
Elemental Royalty (TSX:ELE) just posted its third quarter results, with net income of US$3.75 million compared with US$1.37 million a year earlier, putting profit trends firmly in focus for investors.
Elemental Royalty’s latest earnings arrive in a volatile backdrop, with the share price at CA$22.85 after falling 3.95% on the day. The stock has rebounded 15.87% over 7 days, yet remains down 20.05% over 90 days as earlier momentum has faded, despite a 9.95% 1-year total shareholder return and a 3-year total shareholder return of 101.47%.
See how Elemental Royalty compares with other potential precious metal royalty opportunities by checking our curated list of 33 elite gold producer stocks.
Elemental Royalty just delivered much stronger net income while the share price has swung sharply in recent weeks. Solid royalty assets are one thing. The real test is whether investors are paying a fair price for them today.
Preferred Price-to-Sales of 14.6x: Is it justified?
Elemental Royalty closed at CA$22.85 while trading on a P/S ratio of 14.6x, which places the stock at a rich valuation compared with peers and with its own fair ratio estimate of 14.3x.
The P/S ratio compares the share price to revenue generated per share. For a royalty group like Elemental Royalty, where earnings can be noisy because of one off items, investors often look at sales as a cleaner gauge of what the market is paying for each dollar of top line.
In this case, the market is assigning a much higher price tag to Elemental Royalty’s revenue stream than to the typical Canadian Metals and Mining stock. The current 14.6x P/S ratio is more than double the peer average of 6.1x and also sits above the estimated fair P/S level of 14.3x, which points to a valuation that could be pricing in strong expectations already.
Explore the SWS fair ratio for Elemental Royalty.
Result: Preferred multiple of Price-to-Sales 14.6x (OVERVALUED)
Still, Elemental Royalty faces two clear pressure points that could upset the story: revenue tied to commodity prices and a rich P/S multiple if sentiment cools.
Find out about the key risks to this Elemental Royalty narrative.
Another view on Elemental Royalty’s value
On one side, Elemental Royalty appears expensive on a 14.6x P/S ratio. On the other side, our DCF model suggests the stock trades at a steep discount to an estimated future cash flow value of CA$329.61 per share. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
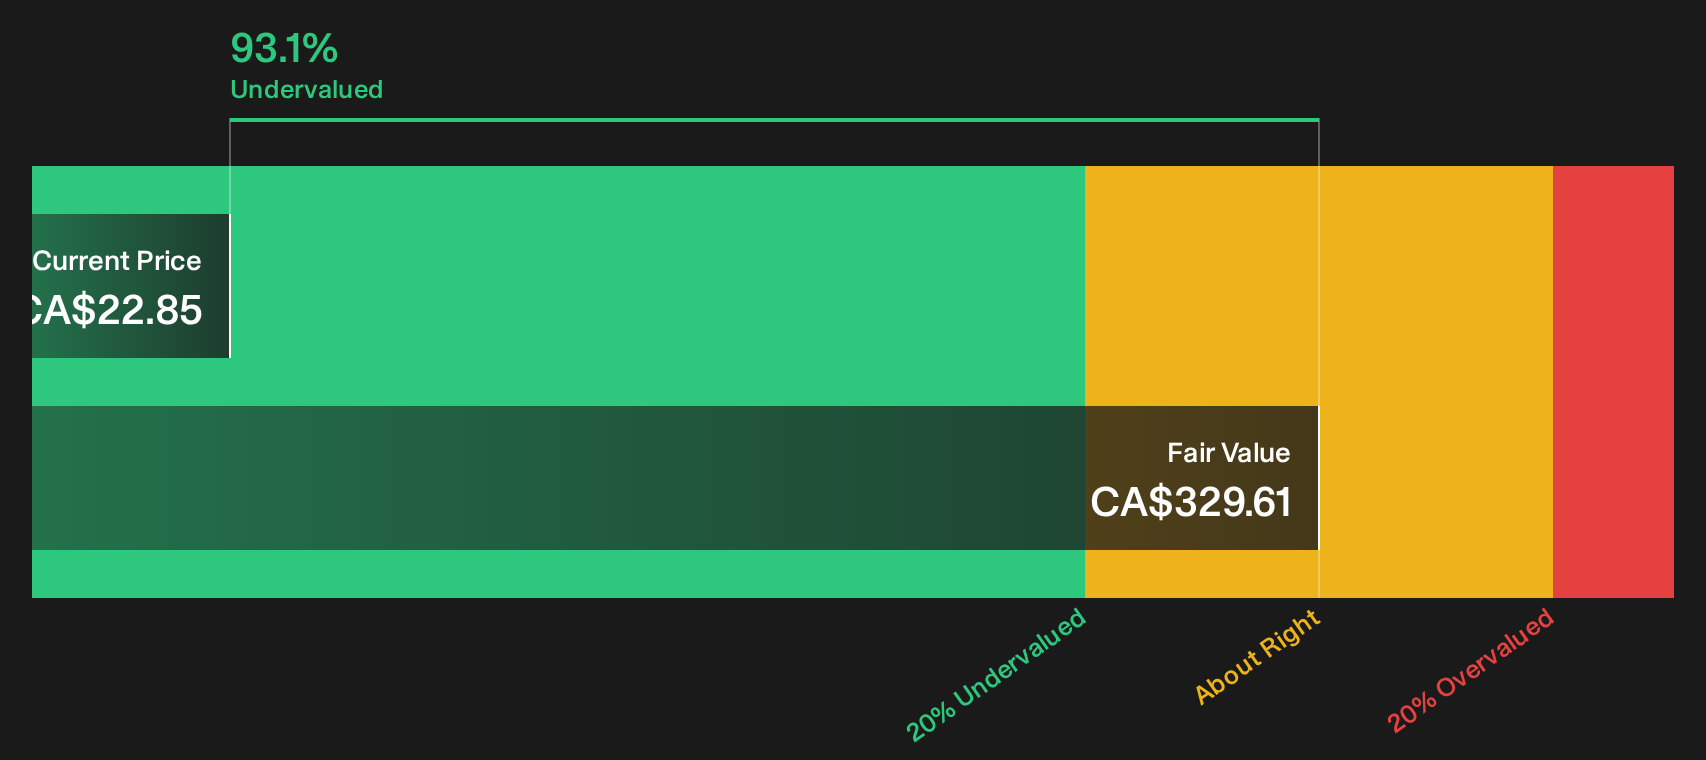
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elemental Royalty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Elemental Royalty’s valuation and risks can feel like a lot to process. Move quickly from headline reactions to your own judgment by weighing its 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Elemental Royalty?
If Elemental Royalty has your attention, do not stop here. Broadening your watchlist with well filtered ideas can sharpen your edge and reduce blind spots.
- Target higher quality at better prices by scanning a curated pool of 5 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- Prioritise resilience first by reviewing a list of solid balance sheet and fundamentals (5 results) that can help you avoid fragile businesses when conditions get tougher.
- Hunt for under-the-radar opportunities through a focused set of 7 high quality undiscovered gems before the crowd turns its attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com