
Is RadNet (RDNT) Pricing In Too Much Sales Optimism?
RadNet has delivered a powerful multi year share price run. The real question for anyone looking at the stock today is how well its current market value lines up with its sales. With fresh headlines around record results and a new acquisition, the debate now turns to what investors are actually paying for each dollar of revenue.
- Over the past 5 years, RadNet has returned 152.6%, which puts a lot of pressure on its sales based valuation to justify how far the stock has come.
- Recent record top line figures and the planned ONRAD acquisition may support higher expectations for future imaging related revenue and could reshape how investors think about the company’s ability to turn additional volume into sustainable sales.
- Your read on RadNet is one view; the desks covering it have another. See what analysts think RadNet's shares could be worth.
The issue now is whether RadNet's current price is justified by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales-based valuation question beyond RadNet, run the numbers across 36 healthcare AI stocks
Is RadNet Getting Expensive on Sales?
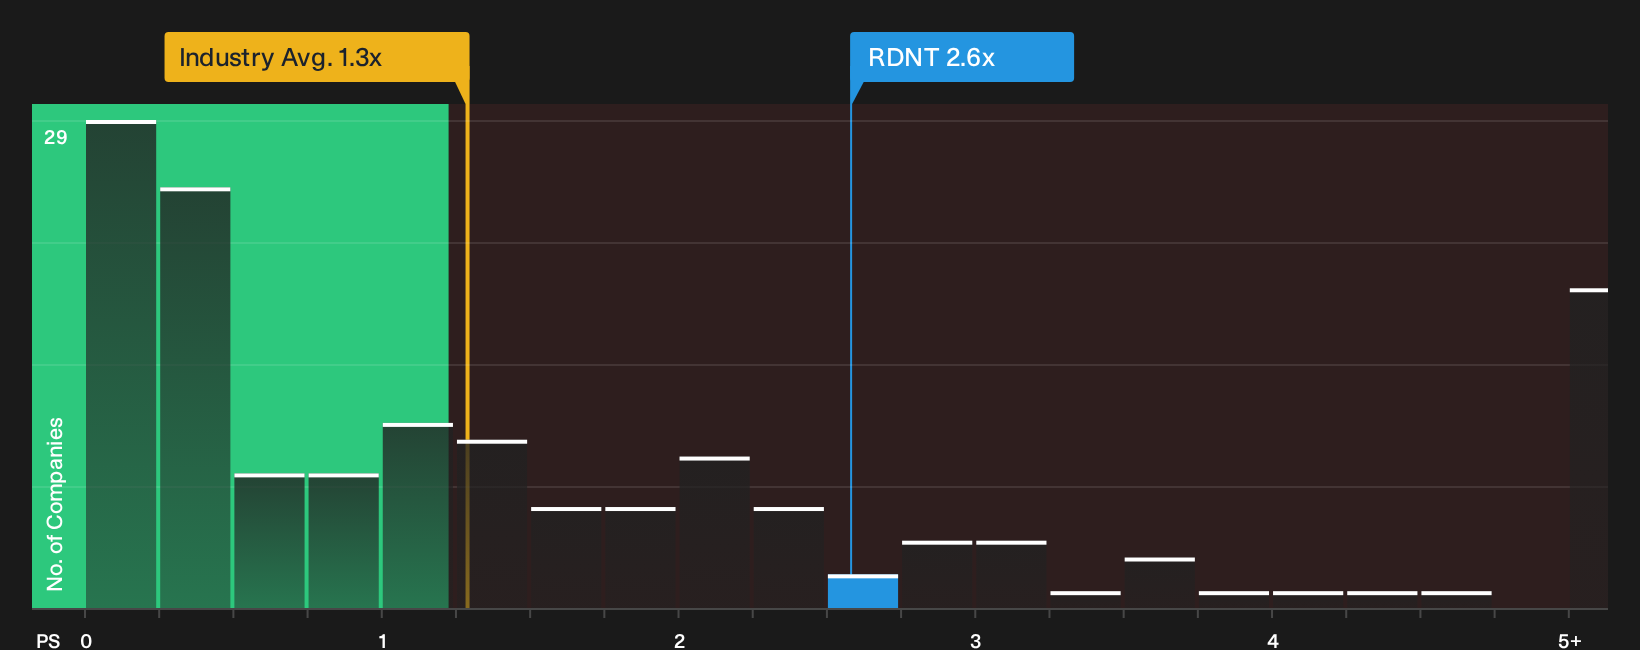
P/S fits RadNet because the business is still heavily judged on how much imaging revenue it can generate rather than on current earnings. On this yardstick, the stock trades on a P/S of 2.6x, which is above the broader Healthcare sector average of 1.3x and only slightly below the peer group at 2.7x. That tells you the market is already assigning RadNet a revenue multiple that reflects more than just a basic imaging operator.
Because the Fair Ratio framework adjusts the P/S multiple for RadNet’s own growth profile, margins, size and risk, the current 2.6x reading screens as overvalued against that tailored benchmark. Despite the record Q3 2026 revenue and raised guidance, the valuation already prices in a lot of good news on future sales productivity and integration of deals like ONRAD, which leaves less room for disappointment if execution or industry conditions do not match those expectations. Explore the numbers behind RadNet's P/S valuation.
The RadNet Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for RadNet leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the stock to be worth much more or meaningfully less than it is today on the market. Each scenario on the Community page ties a specific fair value estimate to a clearly framed set of potential catalysts and risks, so you can watch over time which storyline fits RadNet's actual progress.
One of the top narratives on RadNet: 18% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The key requirement is that RadNet converts its heavy AI and digital health investment, including acquisitions and joint ventures with health systems, into sustainably higher margins and free cash flow..."
Discover why this Narrative puts RadNet at 18% undervalued.
One more RadNet check before you make a move
Current pricing tells only part of the story. Professional models a few years out provide a separate benchmark to compare with today’s sales-based view. Explore where analysts expect RadNet to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com